GXS Bank vs Maribank Singapore 2026: Which Digital Bank Pays More?
A complete side-by-side comparison of savings rates, features, and who each bank suits best — with verified November 2026 figures.
GXS Bank and Maribank are Singapore’s two most popular full digital banks, both holding MAS Full Digital Bank Licences and backed by major tech companies (Grab/Singtel and Sea Limited/Shopee respectively). For most savers in November 2026, GXS Bank offers higher long-term rates — up to 2.40% p.a. on its Holiday Boost Pocket — while Maribank’s 3.08% p.a. new-user bonus tops the charts for the first 30 days. Which wins for you depends on how much flexibility and ecosystem loyalty matter.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Quick Answer: GXS Bank vs Maribank
Both GXS Bank and Maribank launched as Singapore’s first full digital banks under a MAS Full Digital Bank Licence, and both offer savings rates well above what traditional banks pay. But they serve slightly different audiences and have meaningfully different rate structures.
GXS Bank (backed by Grab and Singtel) is built around pocketed savings with flexible lock-in periods. Its Boost Pockets let you earn up to 1.75% p.a. on 18-month placements with no minimum deposit, rising to 2.40% p.a. on its Holiday Boost 4-month pocket (available until 30 November 2026 for fresh funds of S$10,000–S$100,000). For new users, GXS’s First Boost offers a promotional 3.10% EIR on up to S$5,000 for 3 months. See the full GXS Bank complete guide for a breakdown of every pocket type.
Maribank (backed by Sea Limited and Shopee) uses a stacked-bonus model where your base rate of 0.88% p.a. can be topped up with a new-user bonus (+1.60% p.a. for 30 days), a ShopeeVIP bonus (+0.40% p.a.), and a salary crediting bonus (+0.20% p.a.). For a brand-new user who is ShopeeVIP and credits their salary, the combined rate reaches 3.08% p.a. for the first 30 days — the highest headline rate of any digital bank in Singapore right now. After those 30 days, the maximum drops to 1.48% p.a. See our Maribank complete guide for eligibility details on each bonus.
The short verdict: if you are a new user and an active Shopee shopper, Maribank wins on rate for the first month. For the second month onwards — or if you have S$10,000+ to park — GXS Bank’s Boost Pockets deliver more consistent, higher returns without any ecosystem conditions.
Key Differences at a Glance
| Feature | GXS Bank | Maribank |
|---|---|---|
| Backed by | Grab + Singtel | Sea Limited (Shopee) |
| MAS Licence | Full Digital Bank | Full Digital Bank |
| SDIC Protection | Up to S$100,000 | Up to S$100,000 |
| Base Savings Rate | 0.88% p.a. (Main Account) | 0.88% p.a. |
| Best Standard Rate | 1.75% p.a. (18-month Boost Pocket) | 1.48% p.a. (ShopeeVIP + salary) |
| Best Promotional Rate | 2.40% p.a. (Holiday Boost, until 30 Nov 2026) | 3.08% p.a. (new user, first 30 days only) |
| Minimum Balance | None (most pockets) | None |
| Lock-in Required | Optional (1–18 months for Boost Pockets) | No |
| Interest Accrual | Daily | Daily |
| Debit Card | Visa debit (Grab ecosystem perks) | Mastercard debit |
| Referral Code | YONG477 | 2DCT80WQ |
Source: GXS Bank and Maribank product pages + TKN verification, November 2026. Rates subject to change.
Savings Rates Comparison (November 2026)
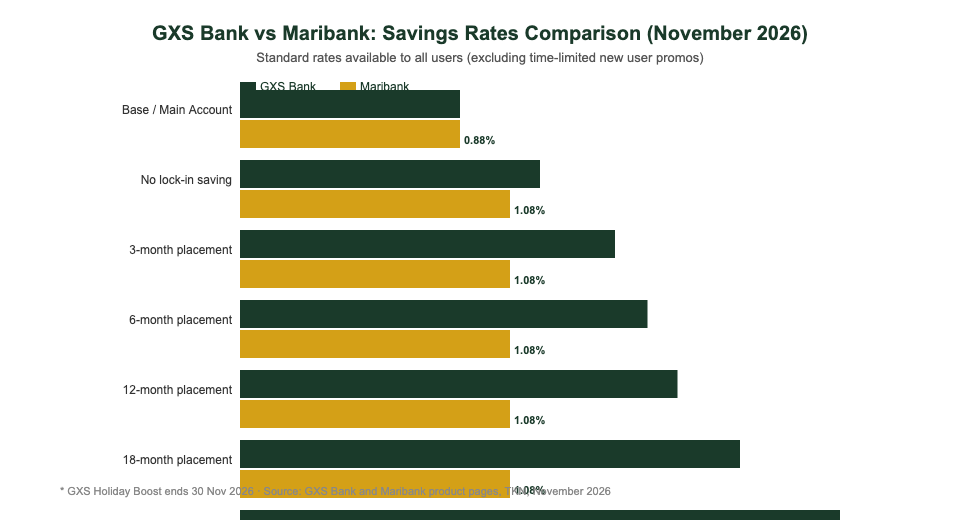
The rate structures of GXS Bank and Maribank are quite different, which is why a direct comparison requires some nuance. GXS Bank uses Pockets — goal-based savings containers with optional lock-in periods. Maribank uses a stacked-bonus model on a single savings account where your rate depends on how many bonuses you qualify for.
GXS Bank Rates (November 2026)
| Product | Rate | Conditions |
|---|---|---|
| Main Account | 0.88% p.a. | Fully liquid, daily interest, no minimum |
| Saving Pocket | 1.20% p.a. | No lock-in, goal-based, daily interest |
| Shell Saving Pocket | 1.38% p.a. | Min S$10,000; 6-month voucher promo |
| Boost Pocket (1 month) | 1.01% p.a. | Lock-in for 1 month |
| Boost Pocket (3 months) | 1.50% p.a. | Lock-in for 3 months |
| Boost Pocket (4 months) | 1.60% p.a. | Lock-in for 4 months |
| Boost Pocket (8 months) | 1.70% p.a. | Lock-in for 8 months |
| Boost Pocket (12 months) | 1.75% p.a. | Lock-in for 12 months |
| Boost Pocket (18 months) | 2.00% p.a. | Lock-in for 18 months |
| Holiday Boost (3 months)* | 2.30% p.a. | Fresh funds S$10K–S$100K; ends 30 Nov 2026 |
| Holiday Boost (4 months)* | 2.40% p.a. | Fresh funds S$10K–S$100K; ends 30 Nov 2026 |
| First Boost (new users only) | 3.10% EIR | Up to S$5,000; 3 months; first placement only |
* Holiday Boost promotion — fresh funds only, minimum S$10,000, maximum S$100,000. Source: TKN GXS Holiday Boost guide, verified 13 November 2026. Use referral code YONG477 for a sign-up bonus. See the GXS Holiday Boost November 2026 guide for full eligibility rules.
Maribank Rates (November 2026)
| Rate Component | Rate | Eligibility |
|---|---|---|
| Base rate | 0.88% p.a. | All users, always |
| + New user bonus | +1.60% p.a. | First 30 days only, new Mari Savings account |
| + ShopeeVIP bonus | +0.40% p.a. | Active ShopeeVIP status + linked Maribank account + claimed in app |
| + Salary crediting bonus | +0.20% p.a. | ≥S$500 eligible salary credited to Mari Savings |
| Maximum (new user, all bonuses) | 3.08% p.a. | First 30 days only |
| Maximum (existing user, all bonuses) | 1.48% p.a. | ShopeeVIP + salary crediting (ongoing) |
Source: Maribank product page and Seedly community post, November 2026. Use referral code 2DCT80WQ when signing up for the new user bonus. No minimum balance required. Rates subject to change.
One important distinction: GXS Bank’s rates are fixed for the duration of your chosen Boost Pocket tenure once you lock in. Maribank’s rates (except the base) are conditional and can change if your Shopee VIP status lapses or your employer changes your salary crediting bank. For long-term planning, GXS’s locked rate gives more certainty.
If you are looking for alternatives beyond digital banks — such as Singapore Government Securities yielding around 3%+ — the Singapore Savings Bonds guide and our Singapore T-bills 2026 guide cover risk-free options backed by the Singapore government.
Interest Earned: Real SGD Scenarios
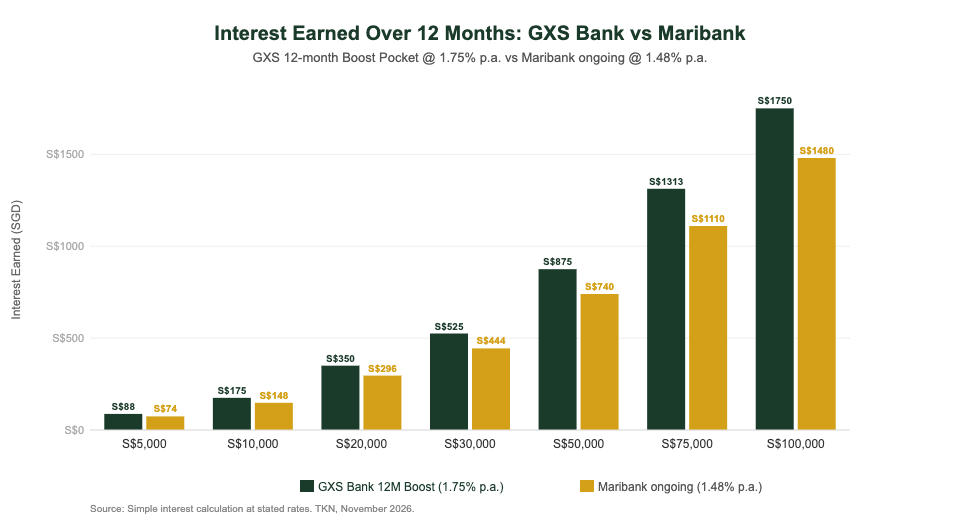
Let’s put actual numbers to these rates. The calculations below assume you deposit funds at the start of the period and leave them untouched. For GXS Bank, we use the 12-month Boost Pocket (1.75% p.a.) as the most practical long-term rate for comparison. For Maribank, we use 1.48% p.a. (existing user, ShopeeVIP + salary) as the ongoing rate after the first 30-day new user bonus expires.
| Scenario | GXS 12M Boost (1.75% p.a.) |
Maribank Ongoing (1.48% p.a.) |
GXS Advantage |
|---|---|---|---|
| S$5,000 for 12 months | S$87.50 | S$74.00 | +S$13.50 |
| S$10,000 for 12 months | S$175.00 | S$148.00 | +S$27.00 |
| S$30,000 for 12 months | S$525.00 | S$444.00 | +S$81.00 |
| S$50,000 for 12 months | S$875.00 | S$740.00 | +S$135.00 |
Calculations based on simple interest at stated p.a. rates. GXS rate = 1.75% p.a. (12-month Boost Pocket, no minimum). Maribank rate = 1.48% p.a. (ShopeeVIP + salary crediting, ongoing). Both banks accrue interest daily. SDIC deposit insurance protects up to S$100,000 at each institution.
Use the Singapore retirement calculator to see how compounding these interest rates over years affects your long-term savings goals.
Note: if you are comparing these digital bank rates with fixed deposits at traditional banks or government securities, we also track digital bank FD rates in Singapore across GXS, MariBank, Trust Bank, and others for a broader market view.
Other Features: Cards, Transfers, Loans
Savings rates are the main event when comparing GXS Bank and Maribank, but both banks offer a broader product range that could sway your decision depending on your day-to-day banking needs.
GXS Bank: Beyond the Pockets
GXS Bank offers a Visa debit card that integrates with the GrabPay ecosystem — useful if you are an active Grab user who earns GrabRewards points. Transfers between GXS accounts and to other Singapore banks (via PayNow and FAST) are free and instant. The app allows you to create multiple Saving Pockets with individual goals and labels — a useful feature for anyone who prefers to segregate funds by purpose (holiday fund, emergency fund, house renovation, etc.).
GXS also offers GXS FlexiLoan, a flexible credit line for eligible customers, and a GXS Card (credit card product, subject to eligibility). The bank does not charge fall-below or monthly maintenance fees, making it genuinely free to hold alongside your existing bank account.
Maribank: Shopee Ecosystem Integration
Maribank’s debit card is a Mastercard that can be used for purchases including on Shopee — which also qualifies it for cashback promotions run by Shopee from time to time. Transfers via PayNow and FAST are free. The bank’s most notable feature beyond savings is the Mari Credit Line, offering flexible borrowing for eligible users, and the Maribank credit card (by invitation for eligible applicants).
For Shopee-first users, the ShopeeVIP bonus rate is a genuine perk — it ties your savings rate to your Shopee spending, so active Shopee shoppers effectively get a loyalty reward on their savings. The flip side: if you stop being a ShopeeVIP, your savings rate drops from 1.48% to 1.08% p.a. (base + salary only). That rate dependency on a shopping platform may not suit everyone.
Safety and Regulation
Both banks are regulated by the Monetary Authority of Singapore (MAS) under Full Digital Bank Licences. Both are members of the Singapore Deposit Insurance Corporation (SDIC) scheme, which insures deposits up to S$100,000 per depositor per institution. This is the same protection level as DBS, OCBC, and UOB, so there is no additional risk to holding savings with these digital banks within that threshold.
Who Should Pick Which?
Choose GXS Bank if:
- You want consistently higher rates (1.60–2.40% p.a.) without depending on a specific shopping ecosystem
- You have S$10,000 or more and want to take advantage of the Holiday Boost Pocket (2.40% p.a. on 4-month placement) before 30 November 2026
- You prefer rate certainty — once you place funds in a Boost Pocket, the rate is locked for the tenure
- You are an active Grab user and want your debit card to earn GrabRewards
- You want to split savings into goal-based pockets (travel, emergency fund, renovation) each earning different rates
- You are a new GXS user and can place up to S$5,000 in the First Boost at 3.10% EIR for 3 months
Choose Maribank if:
- You are a new user who is ShopeeVIP and credits salary — the 3.08% p.a. for 30 days is the highest available anywhere
- You are an active Shopee shopper who naturally maintains ShopeeVIP status and wants a 0.40% p.a. bonus baked into your savings
- You want complete liquidity with no lock-in at all — Maribank’s savings account has zero restrictions on withdrawals
- You primarily bank on the Shopee/Sea ecosystem and want one app for shopping, banking, and payments
Consider using both:
There is no rule against holding accounts at both GXS Bank and Maribank. A common strategy: use Maribank for the first 30 days to capture the new-user bonus rate, then shift larger amounts into GXS Bank’s Boost Pockets for better ongoing returns. SDIC insurance protects up to S$100,000 at each institution separately, so splitting balances across both banks doubles your insured coverage to S$200,000.
If you are still building an emergency fund and want to understand how different savings vehicles fit into your overall financial picture, the Singapore retirement planning calculator can help you see how small rate differences compound over time.
Disclaimer: Interest rates and product features are accurate as at November 2026 but subject to change. This article is for educational reference only and does not constitute financial advice. All deposits with GXS Bank and Maribank are covered by SDIC insurance up to S$100,000 per depositor per institution.
Frequently Asked Questions
Is GXS Bank or Maribank better for saving money in Singapore?
For most savers in November 2026, GXS Bank offers better ongoing rates — up to 1.75% p.a. on its 12-month Boost Pocket and 2.40% p.a. on its Holiday Boost 4-month pocket (for fresh funds of S$10,000–S$100,000, until 30 November 2026). Maribank’s 3.08% p.a. maximum rate is higher, but it only applies for the first 30 days for new users who qualify for all three bonus layers (base + new user + ShopeeVIP + salary). After those 30 days, Maribank’s maximum ongoing rate drops to 1.48% p.a. for users who maintain ShopeeVIP and salary crediting — still competitive, but lower than GXS’s Boost Pockets for lump-sum placements.
What is the difference between GXS Bank and Maribank?
Both are MAS-licensed full digital banks with SDIC deposit insurance up to S$100,000. GXS Bank is backed by Grab and Singtel and uses a pocket-based savings system with optional lock-in periods to earn higher rates. Maribank is backed by Sea Limited (the company behind Shopee) and uses a stacked-bonus model on a single savings account, with bonuses tied to your Shopee activity and salary crediting. GXS suits those who prefer rate certainty and ecosystem-independent earning; Maribank suits active Shopee shoppers who want a fully liquid account with loyalty rewards baked into the rate.
Are GXS Bank and Maribank safe? Are my deposits insured?
Yes. Both GXS Bank and Maribank hold MAS Full Digital Bank Licences, which is the highest category of digital banking licence in Singapore. Both are members of the Singapore Deposit Insurance Corporation (SDIC), which insures deposits of up to S$100,000 per depositor per institution. This is the same protection level as traditional Singapore banks like DBS and OCBC. If you hold accounts at both banks, your deposits at each are insured separately — giving you a combined protected amount of up to S$200,000.
Can I use my CPF or SRS funds with GXS Bank or Maribank?
No. Neither GXS Bank nor Maribank currently participates in the CPF Investment Scheme (CPFIS) or accepts Supplementary Retirement Scheme (SRS) funds directly. CPF and SRS monies can only be invested or deposited with institutions and products approved under their respective schemes. For CPF-eligible options, you would need to use products from approved banks and investment platforms. Both GXS Bank and Maribank accounts can be linked to your existing bank accounts for transfers, but they are funded with cash savings only, not CPF or SRS monies.
How do I open a GXS Bank or Maribank account?
Both banks are app-only. Download the GXS Bank app (iOS or Android) and complete onboarding with your Singpass — the process typically takes under 10 minutes. For GXS Bank, enter referral code YONG477 during sign-up for a sign-up bonus. For Maribank, download the Maribank app and open a Mari Savings account — use referral code 2DCT80WQ to unlock the new-user rate bonus for your first 30 days. You will need to be a Singapore citizen, PR, or EP/SP holder aged 18 and above to apply.
Does GXS Bank's Holiday Boost still apply if I already have a GXS account?
Yes — the GXS Holiday Boost is available to both new and existing GXS Bank users. The key conditions are that the funds deposited must be “fresh funds” (not transferred from an existing GXS Pocket), the minimum is S$10,000, the maximum is S$100,000 per customer, and the promotion ends on 30 November 2026. If you place S$10,000 in a 4-month Holiday Boost Pocket, you earn 2.40% p.a. for that period. See the full GXS Holiday Boost November 2026 guide for step-by-step instructions.
Is Maribank's 3.08% rate really that high?
Yes, but with important caveats. Maribank’s 3.08% p.a. is the maximum possible rate and requires all three bonuses to stack simultaneously: the new-user bonus (only available for the first 30 days of a brand-new account), active ShopeeVIP status (requires meeting Shopee spending thresholds), and salary crediting of at least S$500 per month to your Maribank account. If even one of these conditions is not met, the rate drops. For a first-time Maribank user who ticks all three boxes, it is genuinely one of the highest cash savings rates in Singapore — but as a comparison point, the 3.10% EIR on GXS Bank’s First Boost (for new users, up to S$5,000, 3 months) is similarly competitive for smaller amounts.
Open GXS Bank or Maribank Today
Use our referral codes for sign-up bonuses. GXS Bank: YONG477 | Maribank: 2DCT80WQ
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.