GXS Bank vs MooMoo Cash Plus 2026: Which Is Better for Parking Your Spare Cash?
Digital bank Boost Pocket versus brokerage cash sweep — here is what the numbers actually look like in November 2026.
GXS Bank’s Boost Pocket currently earns 1.5%–1.6% p.a. standard — or up to 2.4% p.a. during the Holiday Boost promo running until 30 November 2026 — and your deposits are SDIC-insured up to S$100,000. MooMoo Cash Plus sweeps idle brokerage cash into the Fullerton SGD Cash Fund at roughly 1.32% p.a. with no lock-in and no deposit insurance. For a pure savings rate, GXS wins; for investors who want idle cash to work while staying ready to deploy, MooMoo Cash Plus fits better.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
At a Glance: Key Differences
These two products solve different problems. GXS Bank is a full MAS-licensed digital bank offering a savings account with a lock-in savings product (Boost Pocket). MooMoo Cash Plus is a cash-sweep feature inside a brokerage account that automatically earns money market fund returns on uninvested cash. Neither is strictly better — the right choice comes down to your situation.
| Feature | GXS Bank | MooMoo Cash Plus |
|---|---|---|
| Product type | Full digital bank savings account | Brokerage cash sweep (money market fund) |
| MAS licence | Full digital bank licence (Grab + Singtel) | Capital Markets Services licence |
| SDIC deposit insurance | Yes — up to S$100,000 per depositor | No — not a bank deposit |
| Current best rate (Nov 2026) | Up to 2.4% p.a. (Holiday Boost, until 30 Nov) | ~1.32% p.a. (variable, based on fund NAV) |
| Standard ongoing rate | 1.5%–1.6% p.a. (Boost Pocket) | ~1.32% p.a. (variable) |
| Lock-in required? | Yes — 1 to 18 months (Boost Pocket) | No — fully liquid, no lock-in |
| Minimum amount | S$1 (main account); S$10,000 (Holiday Boost) | No minimum |
| Best for | Savers who want SDIC-insured higher returns | Brokerage investors parking idle trading cash |
Source: GXS Bank, moomoo Singapore, November 2026. Rates subject to change.
What Is GXS Bank?
GXS Bank is Singapore’s digital bank backed by Grab and Singtel, holding a full digital bank licence issued by the Monetary Authority of Singapore (MAS). Unlike traditional banks, GXS is entirely app-based — no branches, no physical cards by default — but it operates under the same MAS framework as DBS, OCBC and UOB, which means your deposits are insured by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor.
The GXS Bank complete guide covers the full product in detail. For this comparison, the key product is the Boost Pocket.
GXS Savings Account Rates
Your main GXS Savings Account earns a base rate of 0.88% p.a. on your everyday balance — better than most traditional bank savings accounts, but below what you can earn by opening a Boost Pocket. The main account balance is fully flexible and can be accessed instantly via PayNow, FAST transfers, or the GXS Visa debit card.
GXS Boost Pocket: The Lock-In Savings Product
A Boost Pocket is essentially a mini fixed deposit embedded in your GXS Savings Account. You choose a tenor (1 month to 18 months), lock in a lump sum, and earn a significantly higher rate than the main account. As at November 2026, standard Boost Pocket rates sit at 1.5%–1.6% p.a. depending on the tenor you select. You can hold up to eight Boost Pockets simultaneously, with separate principal amounts and maturities.
The trade-off: once you open a Boost Pocket, that money is locked in. Early withdrawal is not supported — you would have to wait for the Boost Pocket to mature before accessing your funds.
Holiday Boost Promo: Up to 2.4% p.a. Until 30 November
GXS is currently running a Holiday Boost promotion that significantly lifts the effective return on a 3- or 4-month Boost Pocket. The November 2026 Holiday Boost gives you an effective return of up to 2.4% p.a. on a 4-month Boost Pocket — achieved by blending Boost Pocket interest of 1.5%–1.6% p.a. with an additional cashback bonus. The minimum deposit is S$10,000, and you must name the Boost Pocket exactly “HOLIDAY BOOST” (all caps) to qualify. This promo ends 30 November 2026.
What Is MooMoo Cash Plus?
MooMoo Cash Plus is not a bank account. It is a cash-sweep feature inside the moomoo Singapore brokerage platform that automatically places uninvested cash into the Fullerton SGD Cash Fund — a MAS-authorised money market fund managed by Fullerton Fund Management. When your trading cash sits idle in your moomoo account, Cash Plus ensures it earns a money market yield rather than zero. As at November 2026, the estimated yield is approximately 1.32% p.a., though this fluctuates daily with short-term Singapore interest rates and the fund’s portfolio composition.
For a deeper look at moomoo as a brokerage, see the full moomoo Singapore review.
How MooMoo Cash Plus Works
Once enabled in the moomoo app, any SGD cash you hold in your brokerage account is automatically swept into units of the Fullerton SGD Cash Fund at the end of each trading day. When you buy shares, the cash is automatically swept back out. There is no minimum investment amount, no lock-in period, and no manual management required. The fund distributes income daily as additional units rather than as cash, so your compounding happens automatically.
Critically, Cash Plus is not covered by the Singapore Deposit Insurance Scheme (SDIC). It is a unit trust, not a bank deposit. Your principal is not guaranteed — although money market funds are considered among the lowest-risk mutual funds, the absence of deposit insurance is a meaningful legal distinction.
CPFIA and SRS Access
One advantage unique to moomoo Cash Plus: the platform integrates directly with CPF Investment Account (CPFIA) and Supplementary Retirement Scheme (SRS) accounts. If you are using moomoo to invest your CPF-OA or SRS funds in ETFs or REITs, Cash Plus lets those uninvested balances earn a yield while you decide what to buy — something a standalone digital bank like GXS cannot replicate.
Rates Compared: What You Actually Earn in November 2026
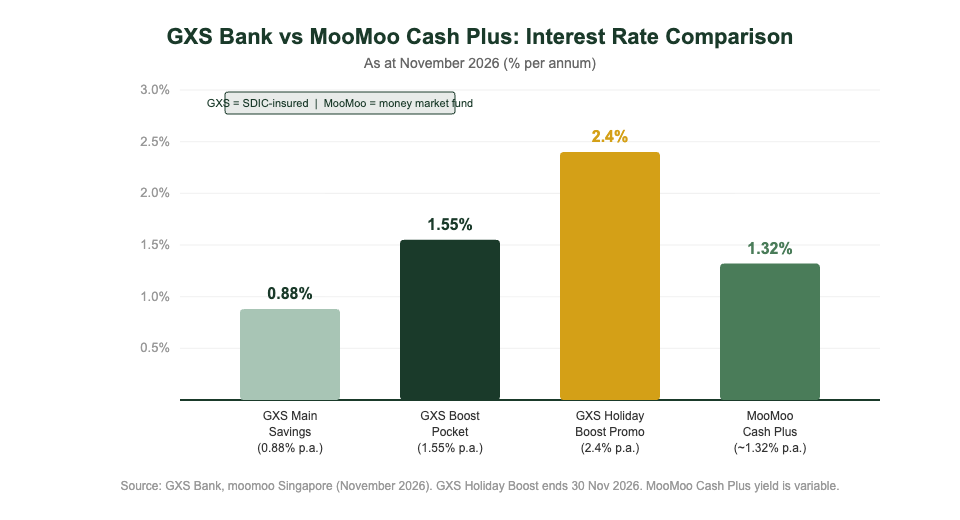
Rate comparisons between a fixed-tenor product like Boost Pocket and a variable money market fund like Cash Plus need careful framing. The table below shows four scenarios, from the highest available GXS rate to the standard ongoing options.
| Scenario | Rate | Lock-in? | SDIC Insured? |
|---|---|---|---|
| GXS Holiday Boost (4-month, until 30 Nov) | Up to 2.4% p.a. | Yes — 4 months | Yes |
| GXS Holiday Boost (3-month, until 30 Nov) | Up to 2.3% p.a. | Yes — 3 months | Yes |
| GXS Standard Boost Pocket (post-promo) | 1.5%–1.6% p.a. | Yes — 1 to 18 months | Yes |
| GXS Savings Account (main, no Boost Pocket) | 0.88% p.a. | No — fully flexible | Yes |
| MooMoo Cash Plus (Fullerton SGD Cash Fund) | ~1.32% p.a. | No — fully liquid | No |
Source: GXS Bank, moomoo Singapore (November 2026). MooMoo Cash Plus yield is based on the Fullerton SGD Cash Fund 7-day annualised yield and fluctuates daily. GXS Holiday Boost ends 30 November 2026.
Dollar Impact at Different Deposit Sizes
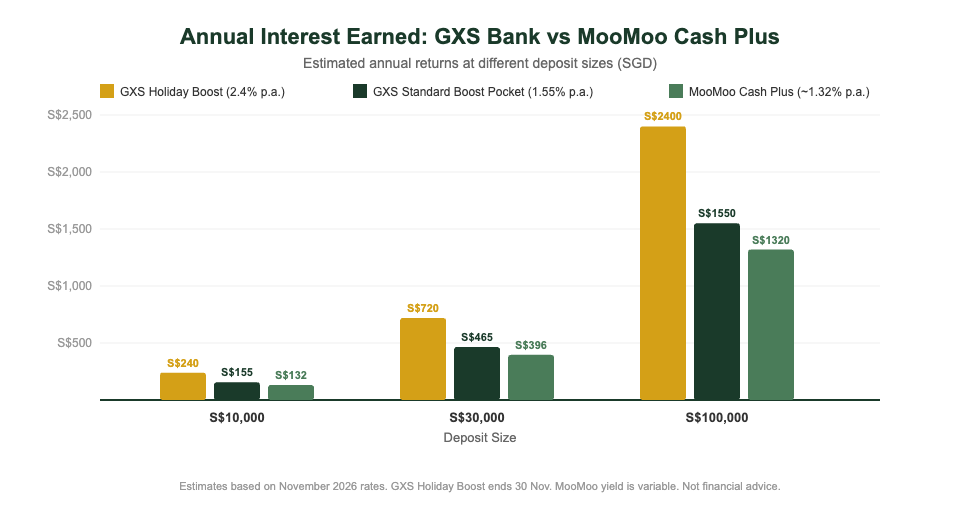
To make the rates concrete, here is the estimated annual interest at three common deposit sizes. These use the GXS Holiday Boost at 2.4% p.a. versus MooMoo Cash Plus at 1.32% p.a. — the difference compounds meaningfully at higher balances.
| Deposit Size | GXS Holiday Boost (2.4% p.a.) | GXS Standard Boost (~1.55% p.a.) | MooMoo Cash Plus (~1.32% p.a.) |
|---|---|---|---|
| S$10,000 | ~S$240 / yr | ~S$155 / yr | ~S$132 / yr |
| S$30,000 | ~S$720 / yr | ~S$465 / yr | ~S$396 / yr |
| S$100,000 | ~S$2,400 / yr | ~S$1,550 / yr | ~S$1,320 / yr |
Estimates only. GXS Holiday Boost ends 30 Nov 2026; standard Boost Pocket rate applies thereafter. MooMoo Cash Plus yield fluctuates daily. These figures are pre-tax. Not financial advice.
Safety and Insurance: A Critical Difference
This is where GXS Bank and MooMoo Cash Plus diverge most fundamentally. It is not simply about rates — it is about the legal nature of your money.
GXS Bank holds a full digital bank licence from MAS. When you deposit money into a GXS Savings Account, it is a bank deposit protected under the Deposit Insurance Scheme. SDIC insures each depositor up to S$100,000 across all accounts at the same bank. If GXS Bank were to fail, you would receive your principal and accrued interest back (up to the S$100k cap) through SDIC. This is the same protection you get at DBS or OCBC.
MooMoo Cash Plus sweeps your cash into the Fullerton SGD Cash Fund, which is a MAS-authorised unit trust under moomoo’s Capital Markets Services licence. Unit trusts are not bank deposits and are not covered by SDIC. Your cash is instead protected under the Securities and Futures Act (SFA) framework — your assets are held in segregated accounts separate from moomoo’s own balance sheet, so they are protected in the event of moomoo becoming insolvent. However, the Fullerton fund’s NAV is not guaranteed; in theory, it can fall. In practice, MAS-authorised SGD money market funds have an excellent safety record, but the absence of deposit insurance is a material difference for risk-averse savers.
Bottom line: If you are parking an emergency fund or money you absolutely cannot afford to lose, GXS Bank’s SDIC insurance is a significant advantage. If you are parking surplus investing cash in a brokerage account, the absence of SDIC is an acceptable trade-off given the fund’s low risk profile.
Liquidity and Access: Lock-In vs Always-On
Liquidity is the second major axis of this comparison. The two products are structured very differently.
GXS Bank main account: Fully flexible. Your everyday GXS Savings Account balance earns 0.88% p.a. and is accessible via PayNow, FAST transfers, and the GXS Visa debit card at any time. No lock-in, no notice period.
GXS Boost Pocket: When you open a Boost Pocket, that specific sum is locked for the full chosen tenor (1 to 18 months). There is no early withdrawal option. If you need money urgently, you cannot break a Boost Pocket — you would have to wait until maturity or use the remaining flexible balance in your main account. This is the core liquidity trade-off for the higher rate.
MooMoo Cash Plus: Fully liquid. When you sell units to buy shares or withdraw cash, the redemption typically settles within the same trading day. There is no lock-in, no notice period, and no minimum holding period. This makes Cash Plus significantly more flexible than any Boost Pocket arrangement.
For savers who might need their money unexpectedly, MooMoo Cash Plus’s liquidity is a real advantage over Boost Pockets. The main GXS account (at 0.88% p.a.) is also flexible, but its rate is below Cash Plus’s current yield. So for liquid savings above the SDIC concern, MooMoo Cash Plus actually competes more directly with the GXS main account than with the Boost Pocket.
For comparison, see also how Trust Bank compares to moomoo and how MariBank compares to moomoo — the same liquidity trade-offs apply across all digital bank comparisons.
Who Should Choose Which?
There is no universal winner. These two products target different users and different use cases.
Choose GXS Bank Boost Pocket if you:
- Want SDIC deposit insurance on your savings
- Can commit a lump sum for 1–18 months without needing it
- Want to earn more than Singapore T-bills or most fixed deposits (especially with the Holiday Boost promo running until 30 Nov 2026)
- Prefer a standalone digital bank for everyday payments and PayNow transfers
- Are building an emergency fund or saving for a goal with a defined timeline
Choose MooMoo Cash Plus if you:
- Already have a moomoo brokerage account and want idle cash to earn something between trades
- Use moomoo for CPFIA or SRS investing and want those uninvested balances to earn a yield
- Need instant access to your cash for investing opportunities without any lock-in penalty
- Are comfortable with a money market fund that is not SDIC-insured but is MAS-authorised
- Do not want to open a separate bank account just for parking cash
The pragmatic answer for many Singapore investors: use both. Park your emergency fund in a GXS Boost Pocket for the higher SDIC-insured rate, and let your brokerage idle cash sit in MooMoo Cash Plus for instant deployment into ETFs or REITs. The two products are not mutually exclusive — they serve different pools of money.
How to Sign Up (Referral Codes for 2026)
Open GXS Bank
Download the GXS Bank app and sign up with your SingPass. When prompted for a referral code, enter YONG477 to unlock a welcome bonus for new accounts. The sign-up process takes around 5 minutes via SingPass MyInfo — no paperwork, no branch visit. If you are targeting the Holiday Boost, open your account before 30 November 2026 and set up a Boost Pocket named exactly “HOLIDAY BOOST” with a minimum of S$10,000.
Open MooMoo Singapore
Download the moomoo app and sign up. Use TKN’s referral link to access the latest sign-up offer — bonuses change frequently, so check the current offer at the time of your application. Once your account is funded, enable Cash Plus in the app settings under “Account” > “Cash Plus” and idle SGD balances will start sweeping automatically.
For more detail on moomoo’s platform, fees and features, see the full moomoo Singapore review.
Frequently Asked Questions
Is GXS Bank or MooMoo Cash Plus safer for parking cash in Singapore?
Can I use GXS Bank if I am not a Grab or Singtel customer?
Does MooMoo Cash Plus count towards SDIC protection?
What happens to my GXS Boost Pocket if I need the money before it matures?
Is the 2.4% p.a. GXS Holiday Boost a fixed guaranteed rate?
Can I use MooMoo Cash Plus for CPF-OA or SRS funds?
How does GXS Bank vs MooMoo compare to MariBank and Trust Bank?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.