Endowus vs IBKR Singapore 2026: Which Wins for Long-Term Investors?
Managed robo-advisor vs fully self-directed broker — fees, CPF/SRS support, and who each one actually suits.
Endowus is a managed robo-advisor charging 0.15%-0.60% a year for expert-built portfolios and CPF, SRS and cash access, while Interactive Brokers (IBKR) is a fully self-directed broker charging near-zero account fees but giving you no advice, no CPF support, and the job of picking every holding yourself. For most Singapore investors, the right answer is not “which is better” but “which job do you want done for you.”
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless otherwise noted.
Table of Contents
Quick Answer
Endowus and IBKR solve two different problems, so there is no single winner. Endowus is best described as an outsourced investment office: you tell it your goal (Cash, CPF OA/SA or SRS), it builds and auto-rebalances a diversified portfolio of institutional-class funds, and charges an all-in access fee of 0.15% to 0.60% a year depending on account size and product. IBKR is the opposite: a brokerage with no advice layer and close to zero account fees, giving you direct access to stocks, ETFs and bonds across 160 markets in 36 countries — but every buy, sell, rebalance and currency conversion is a decision you make and execute yourself. A Singapore investor who wants CPF and SRS put to work with zero effort tends to prefer Endowus. A Singapore investor who already has a portfolio strategy, wants the lowest possible running cost on a large cash sum, and is comfortable executing trades, tends to prefer IBKR.
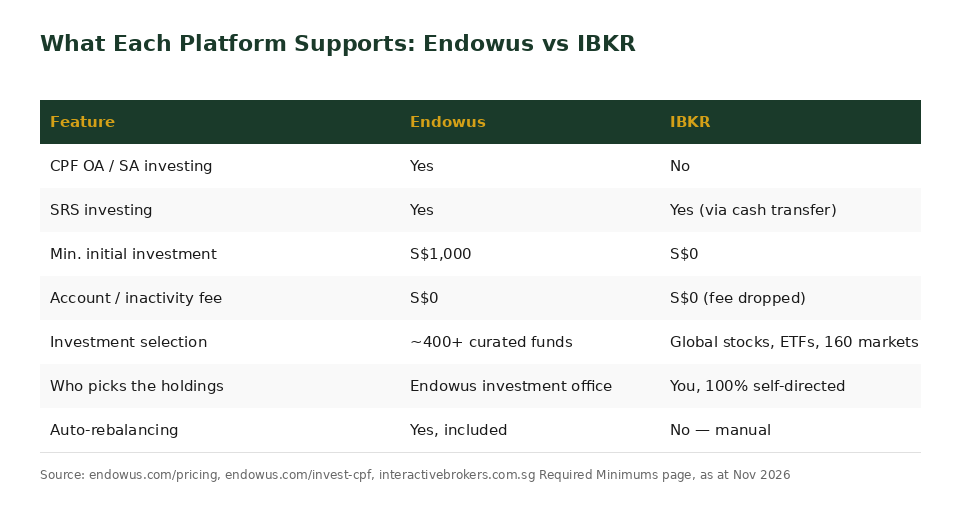
Key Differences at a Glance
| Feature | Endowus | IBKR |
|---|---|---|
| Category | Managed digital wealth platform | Self-directed global brokerage |
| Regulator | MAS CMS Licence 101051, exempt FA | MAS CMS Licence CMS100917 |
| Minimum investment | S$1,000 | S$0 — no minimum |
| Account / inactivity fee | S$0 (covered by access fee) | S$0 — inactivity fee removed |
| Investment selection | Expert-built portfolios or 400+ curated funds | Stocks, ETFs, options, bonds, FX across 36 countries |
| Who decides what to buy | Endowus investment office (evidence-based, conflict-free) | You, 100% self-directed |
| Rebalancing | Automatic, included in fee | Manual — you place every trade |
| Sales / transaction charge | 0% — no sales charge, ever | Per-trade commission (SG: 0.08%, min S$2.50) |
| CPF OA / SA investing | Yes — flat 0.40% (multi-fund) or 0.30% (single fund) | No — IBKR does not accept CPF funding |
| SRS investing | Yes — same tiers as CPF | Yes, via SRS-operator cash transfer (DBS/OCBC/UOB) |
Source: endowus.com/pricing and interactivebrokers.com.sg (Required Minimums, Commissions pages), verified November 2026.
Fee Structure Compared
Endowus charges a single “Endowus Fee” that covers advice, platform access, brokerage and rebalancing — there is no separate sales charge, and it rebates 100% of any trailer fees from fund managers back to the client. As at November 2026, cash invested in advised portfolios (Flagship, Income, ESG) or multi-fund Fund Smart picks is charged 0.60% a year below S$200,000, stepping down to 0.50% (S$200K-S$1M), 0.30% (S$1M-S$5M) and 0.25% (above S$5M). A single-fund Fund Smart pick is charged the lower of 0.30% or your applicable tier. Short-term cash parked in Cash Smart money market funds is a flat 0.15% a year. CPF OA/SA and SRS money is priced separately from Cash and does not combine for tiering — advised CPF/SRS portfolios are a flat 0.40% a year, single-fund CPF/SRS picks are 0.30%.
IBKR’s fee model works the opposite way: there is no advisory fee at all, because there is no advice. You pay a commission only when you trade — for Singapore-listed stocks, 0.08% of trade value with a S$2.50 minimum; for US-listed stocks and ETFs, commissions start from US$1 per order under IBKR Pro, or S$0 under IBKR Lite for US stocks and ETFs. There is no account minimum and, importantly, IBKR confirms on its own Required Minimums page that both account minimums and monthly inactivity fees are now S$0 for individual, joint and trust accounts — a change from the US$10/month inactivity fee some older comparison sites still quote. Currency conversion, where needed, is charged separately at roughly 0.03%-0.20% depending on size, well below most Singapore banks’ FX spreads.
CPF, SRS and Account Access
This is the single biggest practical difference between the two platforms. Endowus was built from the ground up as a CPF- and SRS-compatible platform — you can invest your CPF Ordinary Account and Special Account savings, and your SRS contributions, directly through Endowus’s advised portfolios or Fund Smart, with the Endowus Fee deducted automatically from your holdings each quarter. IBKR has no CPF integration whatsoever: CPF savings sitting in your CPF Investment Account cannot be routed to IBKR under current CPF Investment Scheme (CPFIS) rules, because IBKR is not an approved CPFIS agent bank or platform. SRS money can still reach IBKR, but indirectly — you withdraw or transfer SRS funds from your SRS Operator (DBS, OCBC or UOB) as cash into your own bank account first, which forfeits the point of keeping the money inside the SRS tax-deferred wrapper unless you’re careful about how you fund the trade.
In practice, this means an investor weighing CPF investment strategy options has really only one of these two platforms to choose from for CPF money — Endowus. IBKR only becomes relevant once you’re working with cash outside CPF, or SRS funds you’ve already consolidated.
Worked Example: SGD 50,000 Portfolio
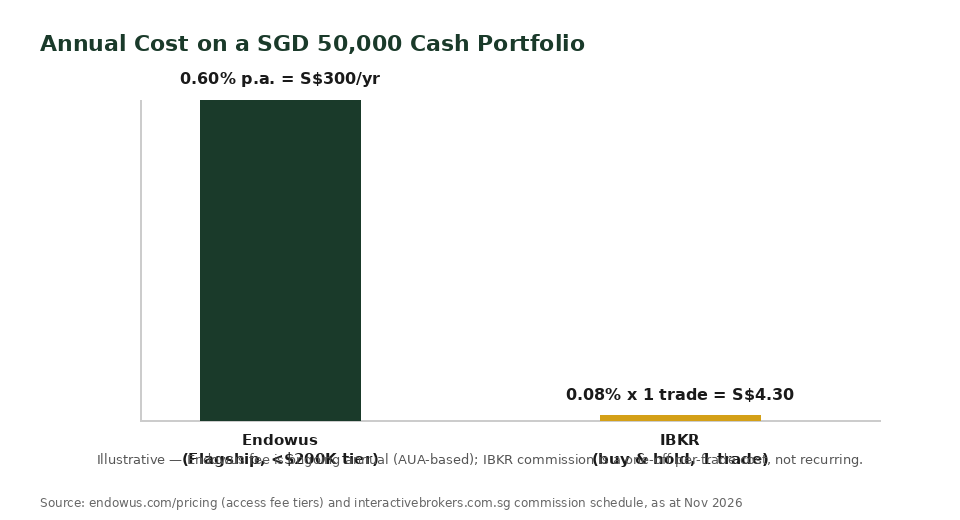
Take a Singapore investor with SGD 50,000 in cash they intend to hold for the long term, buying once and letting the position run for a year with no further trading. On Endowus, sitting below the S$200,000 tier in an advised Flagship portfolio, the Endowus Fee at 0.60% a year works out to roughly S$300 for the year — covering fund selection, quarterly rebalancing, and all platform services, with no separate transaction cost. On IBKR, the same investor buying a single lump-sum ETF position pays the one-off SG commission of 0.08% (or the US equivalent, from US$1), which on a S$50,000 trade comes to roughly S$4.30 — but that single trade gives no ongoing advice, no rebalancing, and no fund research; the investor is fully responsible for deciding what to buy, when to rebalance, and how to react to market moves.
| Scenario | Endowus | IBKR |
|---|---|---|
| S$50,000, one-time buy, held 1 year | ~S$300 (0.60% p.a., ongoing) | ~S$4.30 (0.08%, one-off) |
| What the fee buys | Fund selection, auto-rebalancing, advice, cashback on trailer fees | Trade execution only — no advice or rebalancing included |
| Effort required from investor | Low — set goal, fund account, done | High — research, select, place, monitor, rebalance manually |
Source: endowus.com/pricing and interactivebrokers.com.sg commission schedule, illustrative example, November 2026. Excludes fund-level TER (0.05%-1%) which applies on Endowus-held funds regardless of platform choice, and excludes any underlying ETF/fund TER on IBKR-held positions.
Who Should Pick Which?
Endowus tends to suit you if: you have CPF OA/SA or SRS money sitting idle and want it professionally invested without picking funds yourself; you prefer automatic rebalancing over manual portfolio management; you’re investing cash for the long term (3+ years) and value having an advisory layer; or you want a single platform that unifies Cash, CPF and SRS investing under one fee structure.
IBKR tends to suit you if: you already have a clear investment strategy and don’t need advice; you’re investing a large cash sum where a flat percentage-of-AUM fee becomes expensive relative to a one-off trade commission; you want direct access to specific global stocks, ETFs or bonds that Endowus’s curated fund list doesn’t carry; or you’re comfortable doing your own research, rebalancing, and tax reporting.
Many Singapore investors in fact use both — Endowus for CPF, SRS and a core long-term cash sleeve, and IBKR for a separate satellite portfolio of individual stock or ETF positions they want direct control over. If retirement income planning is the end goal, our Singapore retirement calculator can help size how much of your CPF and SRS actually needs to be invested versus left in cash, and our passive income Singapore guide covers how a Cash sleeve on either platform can be put toward a dividend or income goal instead.
If you decide Endowus is the better starting point, the easiest way in is our Endowus referral code and sign-up bonus page, which also walks through account opening. Investors who want a second managed option to compare against Endowus before committing can also read our Syfe referral code and sign-up bonus breakdown, or see how a fully self-directed low-cost broker stacks up against both in our FSMOne referral code page.
Not financial advice. Fee structures and account terms can change — always verify current rates on each platform before investing. All figures in this article are for educational reference only, correct as at November 2026.
Frequently Asked Questions
What is the main difference between Endowus and IBKR?
Endowus is a managed robo-advisor that builds and rebalances a portfolio for you and charges an all-in access fee of 0.15%-0.60% a year. IBKR is a self-directed brokerage with near-zero account fees where you choose and trade every holding yourself, paying only a per-trade commission.
Can I invest my CPF savings with IBKR instead of Endowus?
No. IBKR is not an approved CPF Investment Scheme (CPFIS) platform, so your CPF Ordinary Account or Special Account savings cannot be routed there. Endowus is one of the few platforms that supports CPF investing directly, which is why it remains the default choice for Singapore investors who want their CPF savings professionally managed.
Which is cheaper, Endowus or IBKR?
It depends on your holding period and trading frequency. For a buy-and-hold lump sum, IBKR’s one-off commission is far cheaper than Endowus’s ongoing annual fee in the first year. But Endowus’s fee includes advice, fund selection and automatic rebalancing every year, while IBKR’s low cost assumes you do all of that work yourself for free.
Does IBKR still charge an inactivity fee in Singapore?
No. As at November 2026, IBKR’s own Required Minimums page confirms that both the account minimum and the monthly inactivity fee are S$0 for individual, joint and trust accounts under both IBKR Pro and IBKR Lite. Older comparison articles quoting a US$10 or US$20 monthly inactivity fee are out of date.
Can I use my SRS funds on IBKR?
Not directly. SRS funds sit with an SRS Operator (DBS, OCBC or UOB) and must be withdrawn or transferred as cash before they can reach an IBKR account, which can trigger tax consequences if not handled correctly. Endowus accepts SRS investment directly through its platform without this extra step.
Is Endowus or IBKR better for a beginner investor?
Endowus is generally easier for a first-time investor because it removes the need to select individual funds, size positions, or rebalance — you choose a goal and risk level, and the platform does the rest. IBKR gives more control and lower running costs but assumes you already know what you want to buy and how to manage a portfolio over time.
Put Your CPF, SRS or Cash to Work
Whichever platform fits your style, here’s where to start.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.