Critical Illness Insurance for Couples in Singapore: Joint vs Separate Policies? (2026)
Each spouse needs their own individual CI policy — here’s how to plan your coverage togetherIn Singapore, couples cannot purchase a joint critical illness insurance policy — every CI plan is individually underwritten and tied to one life assured. A term CI policy for a non-smoking 30-year-old starts from around S$680–S$750 per year for S$300,000 in coverage. Buying together as a couple means coordinating sum assureds, locking in premiums while young, and nominating each other as beneficiaries — but each policy stands independently, guaranteeing a full lump-sum payout if either spouse is diagnosed with a covered critical illness.
Not financial advice. All figures are for educational reference only, verified as at November 2026. Consult a licensed financial adviser before purchasing any insurance product.
Why Singapore Has No Joint Critical Illness Policies
Unlike certain UK or Australian markets where some insurers offer joint life-and-CI policies covering two lives under one plan, Singapore’s insurance market operates on a strictly individual-underwriting basis. Every critical illness policy issued here is tied to one life assured — one premium schedule, one sum assured, one payout event.
For couples, this has several important implications:
- Independent coverage: If your spouse claims on their CI policy due to a cancer diagnosis, your own policy is completely unaffected. Both policies continue independently — the family remains protected even after one claim.
- Separate underwriting: Each spouse is assessed individually on age, gender, smoking status, body mass index, and medical history. A pre-existing condition in one partner does not affect the other’s policy.
- Greater flexibility: Each partner can choose a plan type, provider, and coverage amount best suited to their individual income, health profile, and career stage.
Financial planners often cite “planning individually instead of jointly” as one of the most common mistakes couples make — not because individual plans are wrong, but because couples fail to coordinate their separate policies into a coherent household strategy. That coordination is exactly what this guide covers.
For a full overview of the CI landscape, see our Singapore life insurance guide (2026).
How Much CI Coverage Does Each Spouse Need?
Singapore financial planners generally recommend a CI sum assured of 3 to 5 times your annual income, plus a dedicated treatment cost buffer. A serious critical illness typically means:
- The insured person stops working for months to years
- The household loses that income stream entirely
- Treatment costs are significant — late-stage cancer in Singapore runs S$100,000–S$200,000 per year (Great Eastern, June 2026)
For couples, calculate each partner’s coverage separately. Example: Husband earns S$7,000/month (S$84,000/year). Wife earns S$4,500/month (S$54,000/year).
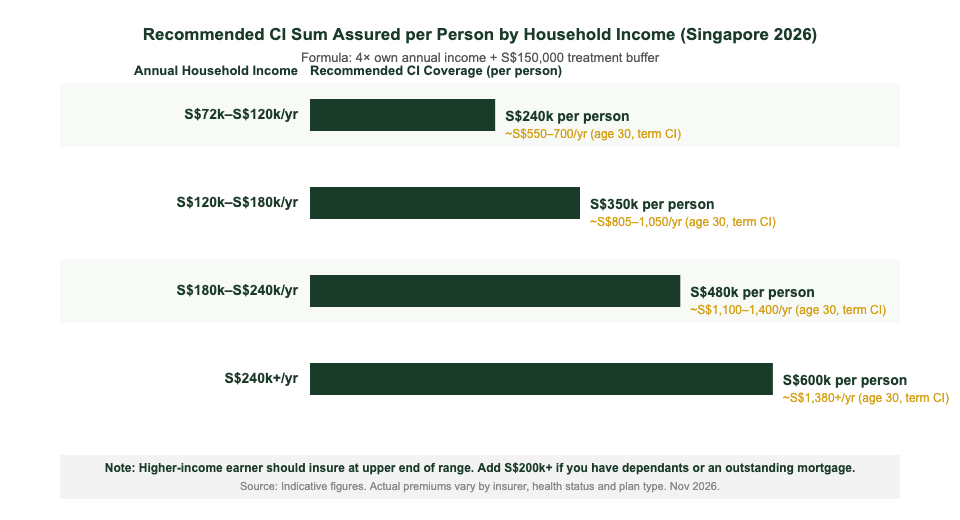
- Husband’s recommended CI: S$84,000 × 4 + S$150,000 = S$486,000 → round to S$500,000
- Wife’s recommended CI: S$54,000 × 4 + S$150,000 = S$366,000 → round to S$400,000
Crucially, the stay-at-home spouse or lower-income partner also needs adequate CI coverage. If the breadwinner falls ill, the other partner faces higher costs: covering household expenses, childcare, domestic help, and potentially reducing their own work hours. A minimum of S$150,000 CI cover per person is a reasonable floor. Use our Singapore retirement calculator to factor your CI coverage needs into your long-term financial plan.
Recommended CI Sum Assured by Household Income (Singapore 2026)
| Annual Household Income | Recommended CI per Person (Est.) | Combined Annual Premium (Both, Age 30) |
|---|---|---|
| S$72,000–S$120,000 | S$200,000–S$250,000 per person | ~S$900–S$1,150/yr (combined) |
| S$120,000–S$180,000 | S$300,000–S$350,000 per person | ~S$1,380–S$1,600/yr (combined) |
| S$180,000–S$240,000 | S$400,000–S$500,000 per person | ~S$1,840–S$2,300/yr (combined) |
| S$240,000+ | S$500,000–S$600,000 per person | ~S$2,300–S$2,760/yr (combined) |
Source: Indicative estimates. Formula: 4× own annual income + S$150,000 treatment buffer. Premiums based on term CI, non-smoker couples, both aged 30. Nov 2026.
Premium Planning for Couples: Smart Strategies
Because each partner buys a separate policy, couples have several planning levers that single buyers do not. Here is how to maximise your combined premiums.
1. Buy Early, Together
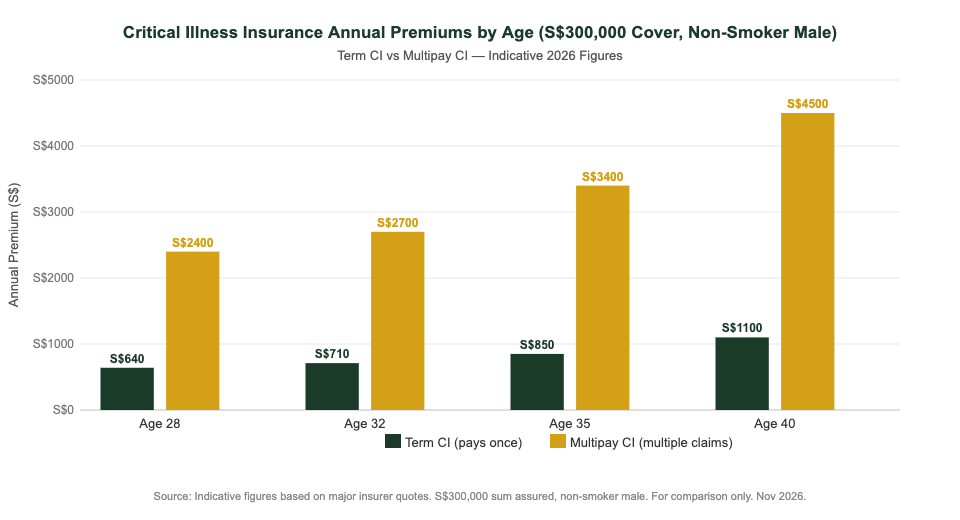
CI premiums rise steeply with age. A couple who buys at 28–32 locks in significantly lower lifetime premiums than one who defers to 40. A non-smoking male aged 35 pays roughly S$850/year for S$300,000 of term CI coverage; the same coverage costs ~S$1,100/year at age 40 — a 29% increase in just five years. Acting together also ensures both partners qualify before any health conditions emerge.
2. Term CI vs Multipay CI: Know the Cost Trade-Off
For couples on a combined budget, two term CI policies (one per spouse) typically deliver more aggregate coverage per dollar than one multipay CI plan. A term CI policy for S$300,000 coverage costs around S$850/year at age 35 (male, non-smoker). A comparable multipay plan costs ~S$3,400/year — four times the premium for the same sum assured. However, multipay plans cover multiple claims across different critical illnesses, which may be valuable for households with a family history of multiple conditions. Read our breakdown of early stage vs late stage CI insurance to decide if early CI coverage is worth the additional premium for your household.
3. Review Coverage Together Annually
As your household grows — mortgage taken on, children born, promotions received — your CI needs evolve. Schedule a joint annual review of both policies after any major life event.
Indicative CI Annual Premiums by Age, Gender and Plan Type (S$300,000 Cover, Non-Smoker)
| Age at Entry | Gender | Term CI (Annual) | Multipay CI (Annual) |
|---|---|---|---|
| 28 | Male | ~S$640 | ~S$2,400 |
| 28 | Female | ~S$580 | ~S$2,100 |
| 32 | Male | ~S$710 | ~S$2,700 |
| 32 | Female | ~S$630 | ~S$2,350 |
| 35 | Male | ~S$850 | ~S$3,400 |
| 35 | Female | ~S$760 | ~S$3,000 |
| 40 | Male | ~S$1,100 | ~S$4,500 |
| 40 | Female | ~S$990 | ~S$4,000 |
Source: Indicative figures based on major insurer quotes. S$300,000 sum assured. Premiums vary by insurer, health declaration and plan features. Nov 2026.
5 Key Factors Couples Must Discuss Before Buying CI Insurance
Before sitting down with a financial adviser, align on these five household-level decisions first.
1. Pre-Existing Conditions
If one partner has a diagnosed condition — hypertension, high cholesterol, a family history of cancer — their application will be individually underwritten. The insurer may approve coverage with a premium loading, exclude specific conditions, or defer coverage. The healthy partner’s application proceeds at standard rates. Buying earlier, before conditions develop, remains the single most effective way to secure clean underwriting for both spouses.
2. Income Asymmetry and the Primary Breadwinner
The higher earner typically needs more CI coverage — their absence creates a larger income shortfall. But do not underinsure the lower-income partner: if they fall ill, the working spouse may need to reduce hours, pay for childcare or domestic help, and cope with emotional strain, all with financial consequences. A minimum of S$150,000 CI cover per person is a sensible floor regardless of income level.
3. Dependants and Outstanding Mortgage
If you have children or a significant outstanding home loan, standard income-replacement calculations underestimate your CI need. Add the outstanding loan balance and estimated child-rearing costs to your coverage target. Families with an S$800,000 mortgage and young children often need individual CI policies of S$500,000 or more per partner.
4. Smoker Surcharges and Lifestyle Factors
Smoking status asymmetry is common in Singapore couples. If one partner smokes, their CI premiums will run 50–100% higher than non-smoker rates. Factor this into your combined budget. Some insurers re-rate premiums downward after two years of confirmed cessation — a meaningful incentive to quit.
5. Standalone CI vs CI Rider on a Life Policy
CI can be purchased as a standalone plan or as a rider on a whole life or term life policy. For couples who already hold base life insurance, adding a CI rider may reduce per-dollar premium cost. However, standalone CI plans offer higher sum assureds and broader plan choice. Our guide on when to buy critical illness insurance covers optimal timing for different life stages, including how CI fits your household before and after age 40.
Beneficiary Nomination for Your Spouse in Singapore CI Plans
CI policies in Singapore pay out to the life assured — the policyholder — while they are alive. This is different from life insurance, where the payout goes to beneficiaries on death. For CI, beneficiary nominations matter primarily if the policyholder passes away before making a CI claim and the policy carries a death benefit (some plans include a small one).
That said, keeping nominations current matters for your broader insurance estate plan:
- Section 49M (revocable) nomination: Simple and flexible. You name your spouse as the beneficiary for any death benefit, and can change the nominee at any time without their consent. Payouts bypass your estate and go directly to the nominee.
- Section 73 (trust) nomination: Creates a statutory trust for your spouse and/or children. Irrevocable without the beneficiaries’ consent. Payouts are protected from creditors and bypass probate — useful for couples with significant outstanding debts.
After marriage, divorce, or the birth of a child, revisit all existing CI and life policies to update nominees. Failure to do so is one of the most common estate-planning oversights in Singapore. To understand how your CI insurance strategy fits into a broader long-term plan alongside CPF, see our overview of CPF investment strategies.
Best CI Plans for Couples in Singapore (2026 Framework)
Rather than prescribing a specific plan — premiums and features change frequently — here is a decision framework by household profile:
| Couple Profile | Recommended Plan Type | Reason |
|---|---|---|
| Budget-conscious, both under 35 | Term CI, S$300,000+ each | Maximum coverage per dollar; build emergency savings separately |
| One partner with family cancer history | Early CI (ECI) plan for that partner | ECI covers early-stage cancers; standard term CI typically does not |
| Both over 40, planning for retirement | Whole life CI rider on existing policy | Lifelong guaranteed coverage; premiums level out over time |
| High earners with multiple health risk factors | Multipay CI plan | Pays for multiple claims across different illnesses over policy life |
All CI policies in Singapore compliant with LIA’s framework cover the same 37 standardised severe-stage critical illnesses (effective 1 October 2025). Plan choice affects premiums, payout structure, and early-stage coverage — not the core 37 conditions.
Frequently Asked Questions
Can couples in Singapore buy a joint critical illness insurance policy?
Should husband and wife have the same CI sum assured?
What happens to a CI policy after divorce?
Is there a discount for buying two CI policies from the same insurer?
What is the best age for couples to buy critical illness insurance in Singapore?
Do all critical illness plans cover the same conditions in Singapore?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.