Endowment Plan vs High-Yield Savings Account Singapore 2026: Which Earns More?
A data-driven comparison of guaranteed returns, liquidity, and real SGD earnings — so you can decide where to park your savings in 2026.
An endowment plan in Singapore typically offers guaranteed returns of 1.44%–2.80% p.a. on a 2-year lock-in, while high-yield savings accounts such as OCBC 360 and UOB One can match or beat that rate — but only if you meet salary crediting, spending, or product conditions. For savers who want certainty without conditions, the right endowment plan can still win. For those with salary credit set up and regular card spend, a savings account usually edges ahead.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026 unless noted.
Table of Contents
Contents — Click to expand
Quick Answer: Which Earns More?
Both products serve different financial needs, and the answer depends on three things: your holding period, whether you can meet the conditions to unlock a savings account’s bonus tiers, and how much capital you are parking.
If you credit your salary and spend regularly on a linked card, high-yield savings accounts from DBS, OCBC, or UOB can pay 1.90%–4.45% p.a. — beating most endowment plans outright. But if you prefer unconditional, locked-in certainty, the OCBC 2-Year Endowment’s 2.80% p.a. guaranteed rate beats the base rates of all three digital banks (MariBank, GXS, Trust Bank) and rivals UOB One’s simple tier without any conditions attached.
Before comparing further, it helps to understand what each product is actually designed to do.
What Is an Endowment Plan?
An endowment plan is a life insurance savings product regulated by the Monetary Authority of Singapore (MAS). You commit a lump sum (or regular premiums) for a fixed tenor — typically 1 to 5 years — and receive a guaranteed maturity payout, sometimes topped up with a non-guaranteed bonus from the insurer’s participating fund.
Key characteristics of endowment plans in Singapore:
- Guaranteed element: The guaranteed return is contractually fixed. Whether the insurer’s investment portfolio performs or not, you receive that amount.
- Lock-in period: Early surrender means you get back less than you put in. Most plans penalise early withdrawal heavily in years 1–2.
- Capital protection: If you hold to maturity, the guaranteed sum assured is protected. Your principal is not at risk if the policy reaches its term.
- Minimum amounts: Short-term endowment plans typically require S$5,000–S$20,000 minimum premium.
- SDIC coverage: Singapore Deposit Insurance Corporation (SDIC) covers life insurance policies up to S$500,000 per insured life for the guaranteed portion.
Short-term endowment plans (1–3 years) are the closest substitute for a fixed deposit or high-yield savings account. They are structured savings vehicles, not investment products, so the Singapore T-bills 2026 guide and Singapore Savings Bonds guide cover complementary alternatives if you want flexibility with government-backed capital safety.
What Is a High-Yield Savings Account?
A high-yield savings account (HYSA) is a bank deposit account that pays above-base interest when you meet certain conditions — most commonly salary crediting, minimum monthly spending on a linked card, or holding additional products (insurance, investments) with the same bank.
In Singapore, there are two broad categories:
Traditional bank bonus-interest accounts — DBS Multiplier, OCBC 360, UOB One — require you to do several things with the same bank to unlock the highest tiers. The potential rates are generous (up to 4.10%–4.45% p.a. as at October 2026), but realising that rate requires active management.
Digital bank savings accounts — MariBank Save, GXS Save, Trust Bank TRUST+ — offer simpler structures. Their base rates are lower (0.88%–1.48% p.a.), but some offer lock-in pockets that rival short-term endowment returns.
Unlike endowment plans, savings accounts are fully liquid — there is no penalty for withdrawing. All three digital banks and the three traditional bank accounts above are SDIC members and protect deposits up to S$100,000 per depositor per bank. For Singapore investors balancing liquidity with return, the endowus referral code page and the Singapore retirement calculator can help you model how much you need accessible versus locked away.
Key Differences at a Glance
| Feature | Endowment Plan | High-Yield Savings Account |
|---|---|---|
| Rate type | Guaranteed (+ non-guaranteed bonus) | Variable (base + conditional bonus) |
| Liquidity | Locked (penalties for early exit) | Fully liquid anytime |
| Rate range (2026) | 1.44%–2.80% p.a. (guaranteed) | 0.88%–4.45% p.a. (varies by conditions) |
| Conditions needed | None — hold to maturity | Salary credit, card spend, product linkage |
| Minimum amount | S$5,000–S$20,000 (varies by plan) | S$0–S$1,000 typical minimum |
| Insurance coverage | Yes — death / TPD benefit included | No insurance element |
| SDIC / MAS protection | SDIC up to S$500k (guaranteed portion) | SDIC up to S$100k per depositor per bank |
| Rate certainty | Fixed at sign-up (guaranteed component) | Can change with bank’s announcement |
| Best tenor | 1–3 years (short-term plans) | Ongoing / revolving |
Source: MAS-licensed insurer factsheets; bank websites; SDIC (Singapore Deposit Insurance Corporation), October 2026.
Interest Rate Comparison 2026
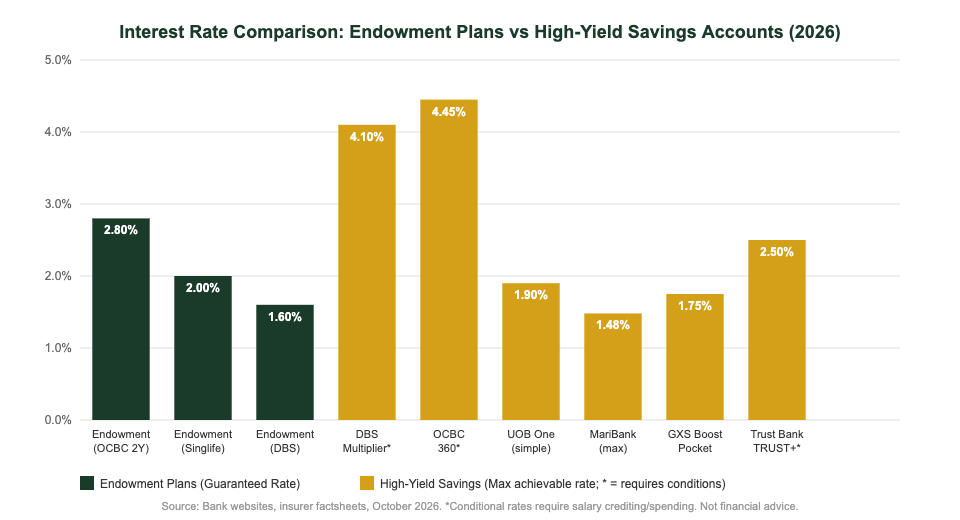
The chart above compares the headline rates available from endowment plans and savings accounts in Singapore as at October 2026. The critical nuance: savings accounts’ highest rates (shown with an asterisk) are conditional — you need to tick specific boxes to earn them every month. Endowment plan rates are guaranteed from day one, no conditions attached beyond holding to maturity.
Endowment Plan Rates (October 2026)
| Plan | Tenor | Guaranteed Rate | Total Illustrated | Min. Premium |
|---|---|---|---|---|
| OCBC 2-Year Endowment | 2 years | 2.80% p.a. | 2.80% p.a. | S$20,000 |
| Singlife Max Saver II | 2 years | 2.00% p.a. | 2.00% p.a. | S$20,000 |
| DBS SavvyEndowment | 2 years | 1.44% p.a. | 1.60% p.a. (incl. non-guar.) | S$5,000 |
Source: Insurer product pages, October 2026. Rates subject to change. Verify current rates with insurer before purchasing.
High-Yield Savings Account Rates (October 2026)
| Account | Max Rate | Easy-Tier Rate | Key Conditions |
|---|---|---|---|
| DBS Multiplier | up to 4.10% p.a. | ~1.80%–2.20% p.a. | Salary + multiple DBS product categories |
| OCBC 360 | up to 4.45% p.a. (cut from 5.45% May 2026) | ~1.95% p.a. | Salary + Save + Spend easy trio |
| UOB One | up to 1.90% p.a. | 1.90% p.a. | Salary ≥ S$1,600 + S$500 card spend/month |
| Trust Bank TRUST+ | up to 2.50% p.a. | ~1.50% p.a. | NTUC FairPrice spend + Trust card use |
| GXS Save (Boost Pocket) | up to 1.75% p.a. | 0.88% p.a. | Boost Pocket: 12-month lock-in, S$5,000 min |
| MariBank Save | up to 1.48% p.a. | 0.88% p.a. | Salary credit + ShopeeVIP membership |
Source: DBS, OCBC, UOB, Trust Bank, GXS, MariBank product pages, October 2026. Rates subject to change without notice.
Worked SGD Examples: What You Actually Earn
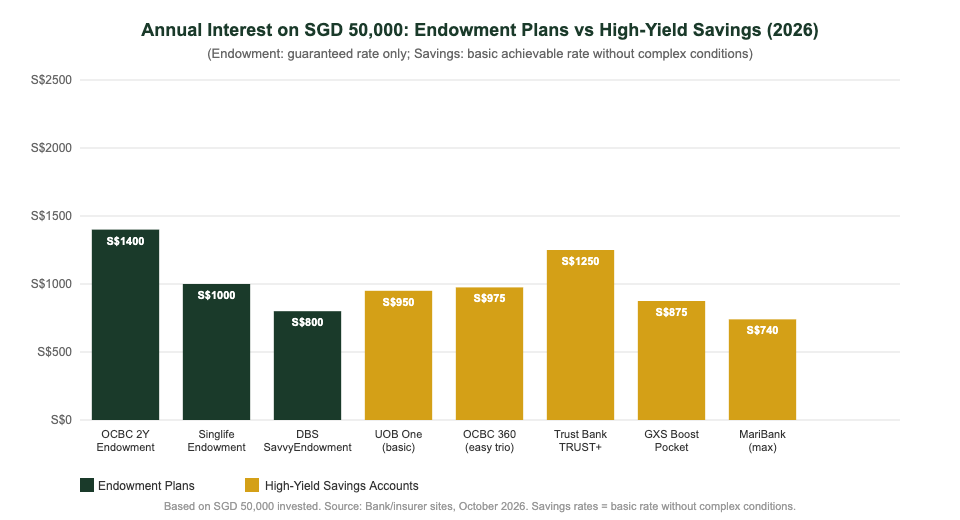
Percentages tell part of the story. Here is what a Singapore investor would actually pocket annually on three common capital amounts, comparing the best endowment plan (OCBC 2-Year at 2.80% guaranteed) against three savings accounts at their easy-to-achieve rates.
| Product | Rate Used | Annual on S$20,000 | Annual on S$50,000 | Annual on S$100,000 |
|---|---|---|---|---|
| OCBC 2Y Endowment | 2.80% (guaranteed) | S$560 | S$1,400 | S$2,800 |
| UOB One (1.90%) | 1.90% (salary + spend) | S$380 | S$950 | S$1,900 |
| OCBC 360 Easy Trio | 1.95% (salary + save + spend) | S$390 | S$975 | S$1,950 |
| Trust Bank TRUST+ | 2.50% (NTUC spend) | S$500 | S$1,250 | S$2,500 |
| MariBank (max 1.48%) | 1.48% (salary + ShopeeVIP) | S$296 | S$740 | S$1,480 |
| GXS Boost Pocket | 1.75% (12-month lock-in) | S$350 | S$875 | S$1,750 |
Source: Calculated from published rates as at October 2026. Endowment plan rate is guaranteed; savings account rates are indicative and require conditions to be maintained monthly. Savings accounts: interest calculated on full balance at quoted rate for illustration only — actual interest may accrue on tiered bands.
The table makes clear that for savers who cannot or do not want to meet monthly conditions, the OCBC 2-Year Endowment at 2.80% guaranteed outperforms all savings accounts shown on an unconditional basis. On S$50,000, that is S$1,400 per year locked in with certainty — versus S$950–S$975 for UOB One or OCBC 360 on a straightforward condition set.
However, if you regularly shop at NTUC FairPrice and use the Trust Bank card — already part of your lifestyle — Trust Bank TRUST+ at 2.50% gets you S$1,250 on the same capital without any lock-in, with the option to withdraw if rates change or you need funds urgently.
When to Choose an Endowment Plan
An endowment plan makes sense when you can clearly answer yes to these questions:
- Do you have surplus savings you will not need for 2–3 years? The lock-in is only a disadvantage if you need the money early. If this capital is genuinely for a future goal — a renovation, a child’s school fees, or a retirement buffer — the lock-in costs you nothing.
- Do you want a guaranteed rate, no strings attached? If monthly conditions (salary credit, spending targets) feel like financial housekeeping you would rather avoid, an endowment plan gives you certainty from day one.
- Is your capital S$20,000 or above? Most competitive endowment plans start at S$20,000. If you are parking S$5,000 or less, the DBS SavvyEndowment at S$5,000 minimum is worth considering, though its 1.44% guaranteed rate is less compelling.
- Do you want a small insurance element alongside savings? Every endowment plan includes a basic death benefit. For younger savers who want to tick both boxes without a separate term plan, this is a minor but real benefit.
For a broader view of guaranteed and low-risk options in Singapore, the Singapore T-bills 2026 guide covers a direct competitor — T-bills currently yielding around 3.0%+ for 6-month tenors, which many investors now prefer for the government-backed nature and the flexibility to roll over every six months. You can also compare with the endowment plan vs money market fund analysis for another liquid alternative.
When to Choose a High-Yield Savings Account
A high-yield savings account is the better choice when:
- You need the money to be accessible. Emergency funds, short-term expense buffers, or capital you expect to deploy in 6–12 months should never be locked into an endowment plan.
- You already meet the conditions without changing your behaviour. If your salary lands in a DBS or OCBC account, and you spend on their credit card anyway, you are already earning the bonus tier — there is nothing more to do.
- You want flexibility as rates change. Savings account rates can be raised (as happened in 2024–2025 as SORA climbed) or cut (as OCBC did in May 2026). You can switch accounts. An endowment plan locks in today’s rate for the entire tenor — great when rates are high, less so if you commit when rates later rise.
- Your savings balance is below the endowment plan minimum. Most competitive plans need S$20,000. If you are building savings below that threshold, a high-yield savings account — including the accessible Endowus cash management option or a Syfe Cash+ account — keeps your money liquid and working harder than a standard savings account.
The bottom line: endowment plans win on certainty of return at competitive capital sizes. High-yield savings accounts win on flexibility, accessibility, and the potential to earn more if you actively manage your banking relationships. Most Singapore savers in their 30s–50s benefit from holding both — a liquid savings account tier for 3–6 months of expenses, and a short-term endowment plan for surplus capital beyond that. Use the Singapore retirement calculator to work out how much you need in each bucket for your timeline.
Frequently Asked Questions
Is an endowment plan better than a high-yield savings account in Singapore?
It depends on your needs. An endowment plan offers a higher guaranteed rate (up to 2.80% p.a. for OCBC’s 2-year plan) with no conditions attached, but locks your capital in for 2+ years with penalties for early surrender. A high-yield savings account offers full liquidity and potentially higher rates (up to 4.45% for OCBC 360) but requires you to meet monthly conditions like salary crediting and card spending. If you have surplus funds you will not touch for 2 years, the top endowment plan often wins on a purely guaranteed, condition-free basis.
Can I put my emergency fund in an endowment plan?
No. Emergency funds must be liquid — accessible immediately without penalty. An endowment plan imposes surrender charges in the first 1–2 years, meaning you would receive less than you put in if you exit early. Keep 3–6 months of expenses in a liquid high-yield savings account or a money market fund, and only invest surplus capital beyond that in an endowment plan.
What happens if I surrender my endowment plan early?
If you surrender an endowment plan before its maturity date, you receive its surrender value, which is typically less than the total premiums paid — especially in the first 1–2 years. The surrender value is published in your policy illustration. Some plans return close to par in year 2 or 3, but it is rarely favourable to exit early. Always treat an endowment plan as illiquid capital for the full tenor stated at sign-up.
Are high-yield savings account rates fixed or can they change?
High-yield savings account rates are variable and can be changed by the bank at any time with notice. OCBC cut its 360 account cap from 5.45% to 4.45% in May 2026 as SORA rates declined. Endowment plan guaranteed rates, by contrast, are fixed at the time you buy the policy and remain contractually locked for the full tenor — giving them a rate-lock advantage in a falling interest rate environment.
Are Singapore digital bank accounts (MariBank, GXS, Trust Bank) safe?
Yes. MariBank, GXS, and Trust Bank are all MAS-licensed digital full banks and SDIC members. Your deposits are insured up to S$100,000 per depositor per bank under the Singapore Deposit Insurance Scheme. This is the same protection as deposits with DBS, OCBC, and UOB. The key difference versus endowment plans: SDIC covers deposits to S$100k; endowment plan guaranteed benefits are protected up to S$500k per insured life for the surrender and death benefit portions under the MAS Policyholder Protection Scheme.
Can I use SRS or CPF funds to buy endowment plans or high-yield savings accounts?
SRS funds can be used to purchase approved endowment policies in Singapore — this is a popular strategy for tax-efficient retirement savings. CPF Ordinary Account funds can also be used for certain approved insurance products, though the range is restricted and you must first check the CPF Investment Scheme’s approved product list. Standard bank high-yield savings accounts (DBS Multiplier, OCBC 360, MariBank, etc.) cannot be funded directly from SRS or CPF — those accounts only accept cash deposits from your linked bank account.
Maximise Your Savings — Start With the Right Account
Whether you choose an endowment plan or a high-yield savings account, sign up through our referral links to claim your welcome bonus.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.