TribeCar + Endowus + MariBank + FSMOne + IBKR: The Change-of-Mind Cost Ladder (2026)
Five platforms for your freed-up TribeCar cash, ranked by what it actually costs you to pull the money back out early.
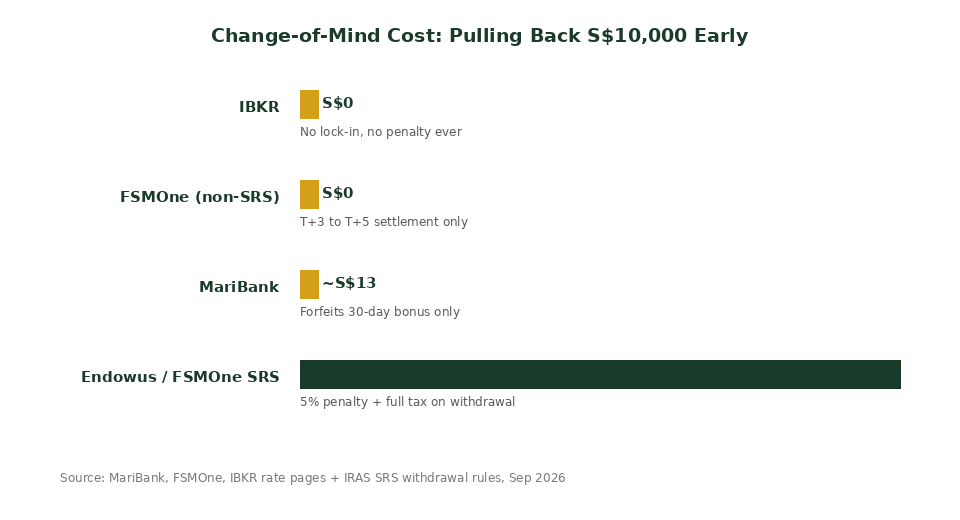
TribeCar frees up S$600 to S$1,200 a month once you stop owning a car. Where you park that cash matters less than what happens if you need it back. IBKR costs nothing to withdraw early. Pulling S$10,000 out of an SRS account before retirement age costs a 5% penalty plus tax on the full amount, no matter which platform holds it.
Not financial advice. All figures are for educational reference only, and your own tax rate, timeline and risk tolerance will differ. Rates and rules current as at September 2026 unless otherwise noted.
Table of Contents
Contents — Click to expand
- What TribeCar Frees Up
- Why “Which Platform Pays More” Misses the Point
- Rung 1: IBKR — Zero Cost, Ever
- Rung 2: MariBank — You Only Lose the Bonus
- Rung 3: FSMOne Outside SRS — Just a Wait
- Rung 4: SRS at Endowus or FSMOne — The Expensive One
- The Ladder in Dollars
- A Logical Routing Order
- Frequently Asked Questions
What TribeCar Frees Up
Owning a mid-range car in Singapore runs roughly S$1,800 to S$2,500 a month once you count COE, loan, insurance, road tax, petrol and parking. Even a heavy TribeCar user spending S$600 to S$900 a month on rentals still comes out S$1,000 to S$1,500 ahead.
That freed-up cash needs somewhere to go every month, and four platforms compete for it here: Endowus, MariBank, FSMOne and IBKR. A companion article in this series already ranked these platforms by how fast money moves in. This one looks at the opposite direction: what it costs to pull money back out before you planned to.
Why “Which Platform Pays More” Misses the Point
Every ladder in this series so far has ranked platforms by rate, speed, insurance cover or KYC friction. This one ranks them by something nobody checks until it’s too late: what it costs you to change your mind.
Plans shift. A retrenchment, a wedding, a flight deal, a medical bill. The platform you picked for its headline rate might be the platform that punishes you hardest for needing the money back early, and the size of that punishment varies more than most people expect.
Rung 1: IBKR — Zero Cost, Ever
IBKR charges nothing to sell and withdraw, at any time. There’s no lock-in period and no early-exit fee on a VWRA or CSPX position. SGD cash balances earn 0% below S$14,000, and USD cash earns 0% below US$10,000, so idle cash sitting there does little either way.
The only real cost is market timing. If VWRA is down 8% the week you need cash, selling locks in that loss. That’s an investing risk, not a platform penalty, and it applies however long you’ve held the position.
Rung 2: MariBank — You Only Lose the Bonus
MariBank pays a 0.88% p.a. base rate, plus a 1.60% p.a. new-user bonus for your first 30 days, 2.48% p.a. combined before any ShopeeVIP or salary-credit stacking. Withdraw before day 30 and you forfeit the bonus portion for the days you didn’t complete.
On S$10,000, that’s about S$13 in lost bonus interest, calculated daily. Your principal and the 0.88% base rate are untouched, and deposits are SDIC-insured up to S$100,000 regardless of when you withdraw.
Rung 3: FSMOne Outside SRS — Just a Wait
Money in FSMOne’s Cash Balance, unit trusts or ETFs outside an SRS account has no lock-in at all. Selling and receiving the cash typically takes T+3 to T+5 business days, standard settlement time, not a penalty.
FSMOne charges 0% sales charge on SRS-linked unit trusts and a 0.08% fee, minimum S$8.80, on ETF trades. The only real friction outside SRS is a few days’ wait and whatever bid-ask spread you cross on the way out.
Rung 4: SRS at Endowus or FSMOne — The Expensive One
SRS is where the ladder gets steep, and it has nothing to do with whether you use Endowus or FSMOne. Withdraw from SRS before your statutory retirement age and IRAS charges a flat 5% penalty on the amount withdrawn, then adds 100% of that amount to your taxable income for the year. Wait until the qualifying age and only 50% is taxable, with no penalty at all. Your SRS cap is S$15,300 a year either way.
One detail catches people out. Your penalty-free withdrawal age is locked to the statutory retirement age in force when you made your first SRS contribution, not the age in force today. The statutory retirement age rises to 64 from 1 July 2026, but that change doesn’t retroactively raise the goalposts for money already contributed under an earlier rule. Read the full mechanics in our SRS withdrawal strategy guide.
Switching your SRS relationship from Endowus to FSMOne, or the reverse, changes none of this. The penalty sits with the scheme, not the platform.
The Ladder in Dollars
The four rungs side by side, cheapest change-of-mind cost first:
| Platform | Lock-In | Cost to Withdraw Early | Why |
|---|---|---|---|
| IBKR | None | S$0 | Market timing risk only, not a penalty |
| FSMOne (non-SRS) | None | S$0 | T+3 to T+5 settlement time only |
| MariBank | 30-day promo window | ~S$13 on S$10,000 (forfeited bonus only) | Base rate + principal untouched, SDIC-insured |
| Endowus / FSMOne SRS | Until statutory retirement age | 5% penalty + full tax on the amount | Set by IRAS, identical at every SRS operator |
Source: MariBank fees & rates page, FSMOne referral code page, IBKR pricing page, IRAS SRS withdrawal rules — September 2026.
Scaling that up by withdrawal size, using an illustrative 15% marginal tax rate for the SRS column since your actual rate depends on total income:
| Amount Withdrawn Early | MariBank (lost bonus only) | SRS 5% Penalty | SRS Penalty + Tax at 15% (illustrative) |
|---|---|---|---|
| S$5,000 | ~S$7 | S$250 | ~S$1,000 |
| S$10,000 | ~S$13 | S$500 | ~S$2,000 |
| S$15,300 (full SRS cap) | ~S$20 | S$765 | ~S$3,060 |
Illustrative only. Your actual marginal tax rate can range from 0% to 24% depending on total chargeable income; MariBank figures assume the full 1.60% p.a. bonus forfeited for the remaining days in the 30-day window.
A Logical Routing Order
There’s a sensible order for freed-up TribeCar cash once you think about it as a change-of-mind ladder rather than a rate table. Cash you might need back within a few months sits better in IBKR or MariBank’s base rate, since pulling it out costs nothing beyond a forfeited bonus.
Cash you’re fairly sure about for a year or two can sit in FSMOne’s non-SRS funds, where the only cost of changing your mind is a few days’ wait. Cash you’re certain you won’t touch until retirement is the only kind worth routing into the SRS cap, precisely because undoing that decision is the most expensive mistake on this list. A CPF and SRS investment strategy built around this kind of tiering, and checked against a retirement calculator, tends to hold up better than one built around the headline rate alone.
Where to Sign Up
Frequently Asked Questions
Does switching my SRS account from Endowus to FSMOne avoid the early withdrawal penalty?
What counts as my statutory retirement age for SRS purposes?
Does IBKR ever charge a penalty for withdrawing cash or selling early?
What happens if I withdraw from MariBank before the 30-day new-user bonus period ends?
Is there a penalty for selling FSMOne unit trusts or ETFs outside an SRS account?
How much does the SRS early withdrawal penalty actually cost in dollars?
Sources: IRAS — Tax on SRS Withdrawals, MariBank Fees & Rates, IBKR Interest Rates. Not financial advice — figures are for educational reference only and may change; verify current rates directly with each platform before acting.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.