Medisave for Family Members 2026: Using CPF to Pay for Parents, Spouse & Children
A complete guide for Singapore residents — who qualifies, what’s covered, and how to claim step by step.
Your Medisave isn’t just for you. CPF members in Singapore can use their Medisave to pay for immediate family members’ hospitalisation, approved outpatient treatments, and Integrated Shield Plan (ISP) premiums. Eligible family members include your spouse, children, parents, parents-in-law, and grandparents and siblings who are Singapore Citizens or Permanent Residents. The same withdrawal limits apply whether you’re paying for yourself or a family member.
Not financial advice. All figures are for educational reference only. Data verified as at 19 September 2026 against official CPF Board and MOH sources.
- You can use your Medisave for your spouse, children, parents, grandparents (SC/PR) and siblings (SC/PR) — for hospitalisation and most outpatient programmes.
- The BHS in 2026 is $79,000 — once your Medisave hits this, excess flows to your Special Account, earning 4% p.a.
- ISP premiums must be paid from the insured person’s own Medisave — you cannot use your Medisave to pay for a family member’s ISP.
Table of Contents
Contents — Click to expand
Who Qualifies as a Family Member for Medisave?
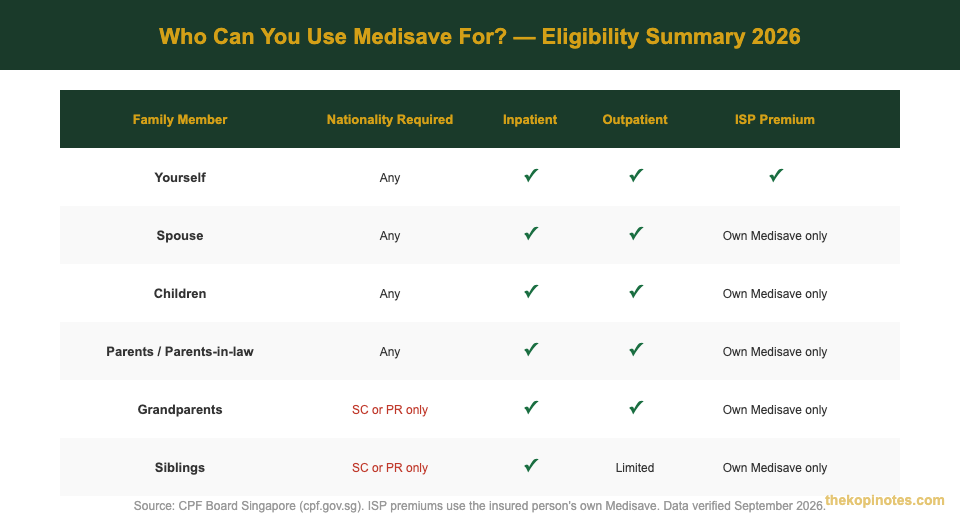
CPF Board allows you to use your Medisave for a defined list of immediate family members. Here’s exactly who qualifies:
| Family Member | Nationality Requirement |
|---|---|
| Spouse | Any nationality |
| Children | Any nationality |
| Parents & Parents-in-law | Any nationality |
| Grandparents & Grandparents-in-law | Singapore Citizen or PR only |
| Siblings | Singapore Citizen or PR only |
Source: CPF Board Singapore (cpf.gov.sg), September 2026
The key rule to remember: your spouse, children, and parents can be of any nationality — including foreigners on Employment Pass or Long-Term Visit Pass — and you can still use your Medisave for their inpatient bills. However, for grandparents and siblings, they must be Singapore Citizens or Permanent Residents.
You also need to be a CPF member yourself. Non-citizens who haven’t contributed to CPF don’t have a Medisave account and cannot use their own Medisave — but their Singapore citizen or PR family member can use their own Medisave to pay for them.
What Can You Use Medisave For?
The types of care you can use Medisave for fall into three main buckets:
1. Inpatient hospitalisation — Any stay in a Singapore hospital or approved medical institution, whether public (restructured hospital) or private. This covers ward charges, daily treatment fees, investigations, and medicines billed during the stay. You can use your Medisave to pay for a qualifying family member’s inpatient bills, subject to the withdrawal limits below.
2. Day surgery — Same-day operations where your family member is admitted and discharged on the same day. Medisave can cover both the ward fee and the surgical procedure fee (up to defined limits per procedure type).
3. Approved outpatient treatments — This category is more restricted. You can use Medisave for outpatient care under approved government schemes, including:
- Chronic Disease Management Programme (CDMP) — covering 23 chronic conditions such as diabetes, hypertension, high cholesterol, and asthma
- Approved vaccinations — for flu, pneumococcal, and other recommended vaccines
- Approved health screenings — under the Screen for Life programme
- Approved outpatient scans — from 1 January 2026, the annual limit doubled from $300 to $600 per year
You cannot use Medisave for general outpatient GP visits, dental care (with limited exceptions), or cosmetic procedures.
Medisave Withdrawal Limits for Family Members
The same withdrawal limits that apply to your own treatment apply when you pay for a family member. The limits exist to ensure Medisave balances last through retirement.
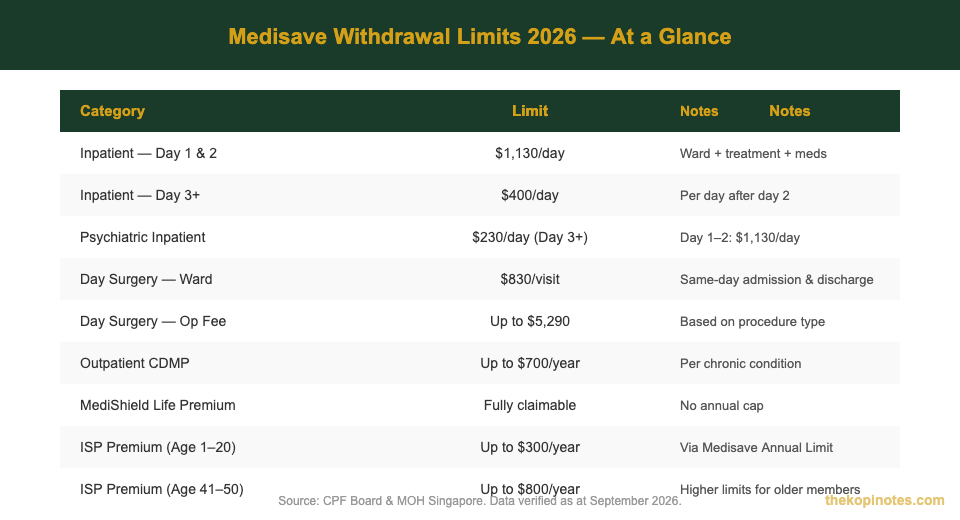
Inpatient Hospitalisation Limits
| Stay Duration | Daily Medisave Limit | Covers |
|---|---|---|
| Day 1 & 2 | $1,130 per day | Ward, treatment, investigations, medicines |
| Day 3 onwards | $400 per day | Same categories |
| Psychiatric (Day 1 & 2) | $1,130 per day | Psychiatric inpatient treatment |
| Psychiatric (Day 3+) | $230 per day | Continued psychiatric care |
Source: CPF Board Singapore. Applies to admissions in approved hospitals. Data as at September 2026.
For a practical example: if your mother is hospitalised for 5 days at a public restructured hospital, you could use Medisave for up to ($1,130 × 2) + ($400 × 3) = $3,460 in ward and treatment charges. Any remaining bill after Medisave and MediShield Life would be paid in cash. Check the Medisave hospitalisation coverage guide 2026 for a detailed worked example.
Day Surgery Limits
| Day Surgery Component | Medisave Limit |
|---|---|
| Ward / Facility charges | Up to $830 per visit |
| Surgical procedure fee | $240 – $5,290 depending on procedure (see MOH Table) |
Source: MOH Singapore. Total Medisave claimable for day surgery varies by procedure. As at September 2026.
How to Pay a Family Member’s Bills Using Medisave
The process is straightforward. Most Singapore hospitals handle the Medisave claim for you at the point of billing — you don’t need to file a separate claim form in most cases. Here’s how it works step by step:
Step 1: Inform the hospital at admission. Tell the admissions staff that you want to use your Medisave (or a family member’s Medisave) to pay for the bill. They will ask for the patient’s relationship to the Medisave account holder and may request identification.
Step 2: Provide your NRIC and the patient’s details. The hospital links your Medisave account to the patient’s bill. For family members, the hospital verifies the relationship on their system.
Step 3: Hospital submits the Medisave claim directly to CPF Board. Once the bill is finalised, the hospital files the claim electronically. CPF deducts from your Medisave and pays the hospital directly — you never handle the funds yourself.
Step 4: CPF sends you a notification. You’ll receive an SMS or notification through your CPF online account showing the amount deducted and the claim reference.
For outpatient claims (CDMP, vaccinations, screenings), the GP or polyclinic handles the Medisave deduction at the point of billing. You authorise it by providing your NRIC or using your SingPass login at the clinic kiosk.
You can also view all Medisave transactions in your Medisave payment guide 2026 overview, or log in to my.cpf.gov.sg to see a real-time record of every claim.
ISP Premiums: Can You Use Your Medisave for Family Members’ ISP?
This is one of the most common questions — and the answer is no, but with nuance.
ISP (Integrated Shield Plan) premiums can only be paid from the insured person’s own Medisave account. You cannot use your Medisave to pay for your spouse’s or child’s ISP premium. Each person’s ISP premium must be deducted from their own Medisave.
However, what you can do is top up a family member’s Medisave to help them afford their ISP premiums. Once you top up their account (up to their BHS of $79,000 in 2026), the premium deduction happens automatically each year from their account.
The Medisave Annual Withdrawal Limit (AWL) — how much can be used for ISP premiums each year — varies by age. Here’s a simplified breakdown:
| Age Group (Insured) | Approx. Medisave AWL for ISP |
|---|---|
| Age 1–20 | Up to ~$300/year |
| Age 21–30 | Up to ~$500/year |
| Age 31–40 | Up to ~$600/year |
| Age 41–50 | Up to ~$800/year |
| Age 51–60 | Up to ~$1,000/year |
| Age 61–70+ | Up to ~$1,600/year (premiums rise significantly) |
Note: AWL figures are approximate and vary by ISP plan tier (Plan A, B, B+). Consult your insurer’s premium schedule for exact figures. Source: MOH Singapore, September 2026.
If an ISP premium exceeds the Medisave AWL for that age group, the remainder must be paid in cash. This is why many Singaporeans top up a parent’s Medisave — it helps offset the rising ISP premiums as parents age into their 60s and 70s. Read the full Medisave AWL 2026 ISP premiums guide for the complete breakdown by plan.
Tips to Maximise Medisave Coverage for Your Family
Here are practical strategies for Singapore families to stretch Medisave coverage further:
1. Top up a parent’s Medisave before the BHS. In 2026, the BHS is $79,000. If your parent’s Medisave balance is below this, you can do a cash top-up to their account. The top-up counts toward your CPF Cash Top-Up Tax Relief (up to $8,000 per calendar year for topping up family members’ accounts). This strategy is especially valuable if your parent has rising ISP premiums.
2. Understand MediShield Life’s role. Before Medisave kicks in to cover a hospital bill, MediShield Life pays first — after the deductible and co-insurance. Check the Medisave cap and BHS guide to understand how the three layers (MediShield Life + Medisave + ISP) work together for family members.
3. Don’t assume ISP covers everything. ISP riders and co-payment rules changed in April 2023 — some riders no longer cover the full deductible. This means even with an ISP, your family member may still need to pay some cash out-of-pocket. Use your Medisave to cover the portion that MediShield Life and ISP don’t cover.
4. Use the CDMP for chronic diseases. If your parent has diabetes or hypertension, make sure their GP is enrolled in CDMP. Up to $700/year per chronic condition can be claimed via Medisave at CDMP-enrolled GP clinics — far better than paying full cash for each visit.
5. Review the Q4 checklist annually. The Medisave Q4 2026 checklist covers what to review before the year ends — ISP renewal, CDMP registration, vaccination claims, and Medisave top-up tax relief planning. Building a habit of annual review keeps your family’s healthcare finances in order.
For a side-by-side comparison of ISP plans for your family members, the ISP comparison guide 2026 covers all five Singapore insurers — AIA, Great Eastern, Prudential, Singlife, and NTUC Income — with premiums by age.
Frequently Asked Questions
Can I use my Medisave to pay for my foreign spouse's hospitalisation in Singapore?
Yes. Your spouse can be of any nationality — including a foreigner on an Employment Pass, S Pass, or Long-Term Visit Pass — and you can still use your Medisave to pay for their inpatient hospitalisation at an approved Singapore hospital. The standard withdrawal limits apply: $1,130/day for the first two days and $400/day thereafter for ward, treatment, and medication charges.
Can I use my Medisave for my parents if they are not Singapore citizens?
Yes. Parents and parents-in-law can be of any nationality for inpatient hospitalisation purposes. You can use your Medisave to help pay for their hospital bills in Singapore regardless of their citizenship status. The restriction on nationality applies only to grandparents and siblings — who must be Singapore Citizens or Permanent Residents for you to use your Medisave for their bills.
Is there a limit on how many family members I can claim Medisave for?
There is no fixed cap on the number of family members you can pay for using your Medisave. However, your total Medisave withdrawals for all family members combined are constrained by your actual Medisave balance. Each individual claim is subject to the per-day or per-procedure withdrawal limits. If your Medisave runs low, you’ll need to pay remaining bills in cash.
Can I use my Medisave to pay my parent's ISP premium?
No. ISP (Integrated Shield Plan) premiums must be paid from the insured person’s own Medisave account. You cannot use your Medisave to pay for a parent’s ISP premium. However, you can top up your parent’s Medisave with cash (up to the BHS of $79,000 in 2026), and they can then use their own account for the ISP premium. The cash top-up may also qualify for CPF Cash Top-Up Tax Relief of up to $8,000 per year for family members.
What is the Basic Healthcare Sum (BHS) in 2026 and how does it affect family Medisave?
The BHS in 2026 is $79,000 — up from $75,500 in 2025. This is the maximum balance allowed in a Medisave Account for CPF members below age 65. Once a member’s Medisave hits $79,000, any further CPF contributions or top-ups are redirected to their Special Account (which also earns 4% p.a.). The BHS is relevant for families because it caps how much you can top up a parent’s Medisave. Once they hit $79,000, further cash top-ups are not possible — but existing balances continue to earn interest and can still be used for hospitalisation.
Can I use Medisave to pay for a family member's dental treatment?
Generally no. Medisave cannot be used for routine dental treatment for yourself or family members. The exception is specific dental procedures that are medically necessary and performed in a hospital setting, such as wisdom tooth surgery under general anaesthesia. These may qualify under the day surgery withdrawal limits. Check with your hospital’s billing team before the procedure to confirm whether Medisave applies.
Plan Your Family’s Healthcare Coverage
Compare Integrated Shield Plans for your family members and ensure everyone has the right coverage. Use our tools to plan your CPF retirement strategy alongside healthcare costs.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.