INVESTMENT INSURANCE · 15 SEPTEMBER 2026
Income Endowment Plan Singapore 2026: Regular Cash Payouts, Top Plans & FOMC Timing Guide
If you want your endowment to work like a salary — paying you every year rather than one lump sum at the end — an income endowment plan may be the right fit. This guide compares the best income-paying endowment plans in Singapore for 2026, explains how annual cash payouts work, and explains why the FOMC meeting on 17–18 September 2026 could push new-tranche yields lower within weeks.
Data verified as at 15 September 2026. Endowment plan rates and tranche availability change frequently. Always confirm current rates with the insurer or a MAS-licensed financial adviser before applying.
What Is an Income Endowment Plan?
An income endowment plan is a life insurance savings product that pays you a stream of cash benefits at regular intervals — typically once a year — rather than a single payout at maturity. The plan still covers you against death throughout the policy term, and most also return your capital at maturity. The key difference from a standard endowment is the ongoing income it generates while the policy is still active.
Singaporeans use income endowment plans to supplement salary or CPF income during semi-retirement, fund recurring expenses without drawing down savings, and build a predictable income layer that does not depend on market performance.
Most income endowment plans in Singapore are participating (par). Annual cash payouts include a guaranteed portion plus a non-guaranteed bonus tied to how the insurer’s par fund performs. A smaller number are non-participating (non-par), with every dollar of every payout fully guaranteed from day one.
Income Endowment vs Lump-Sum Endowment: Key Differences
With a standard lump-sum endowment you pay a single or regular premium, and collect everything at maturity in one payment. An income endowment flips this structure — you receive smaller payouts throughout the term and then collect a final benefit at maturity. The trade-off is that each individual payout is smaller than the lump sum you would have received, but you access money sooner and do not need to wait years.
| Feature | Income Endowment | Lump-Sum Endowment |
|---|---|---|
| Cash flow | Annual or monthly payouts | Single payout at maturity |
| Policy term | Typically 5–20 years | Typically 2–5 years |
| Return structure | Guaranteed + non-guaranteed bonus | Often fully guaranteed (non-par) |
| Rate sensitivity | Par fund smooths rate movements | New tranches reset quickly after rate cuts |
| SDIC protection | Yes — up to S$500k per insurer | Yes — up to S$500k per insurer |
| SRS eligible? | Select plans only | Many plans accept SRS funds |
Top Income Endowment Plans in Singapore 2026
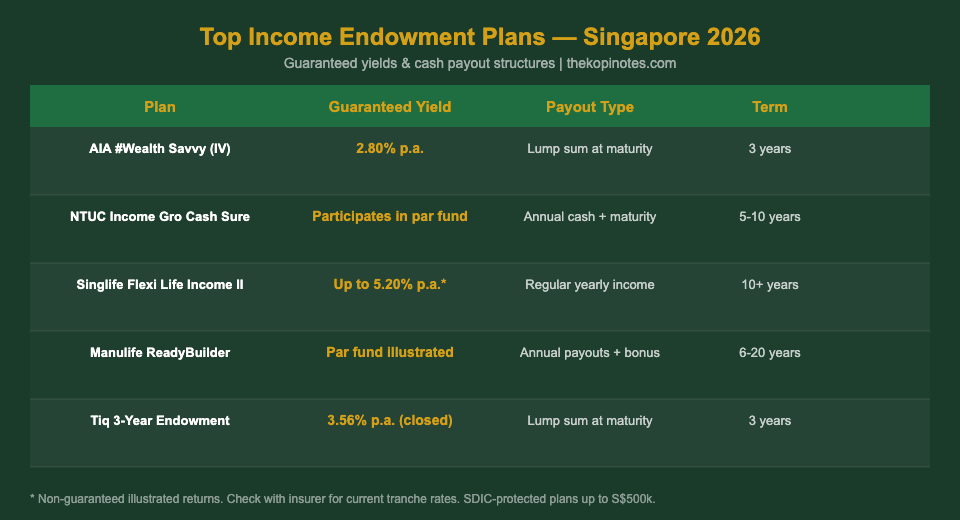
Income endowment plans are participating plans with annual cash payouts — the table below shows the main options available or recently open in Singapore. Always verify availability and rates directly with the insurer, as tranches open and close with little notice.
| Plan | Insurer | Payout Frequency | Key Feature |
|---|---|---|---|
| Gro Cash Sure | NTUC Income | Annual or monthly | Payouts for life after premium term; par plan |
| Flexi Life Income II | Singlife | Yearly cash benefit | Up to 5.20% of sum assured p.a. (illustrated) |
| ReadyBuilder | Manulife | Annual reversionary bonus | Participating plan with bonus accumulation |
| SmartWealth Builder | AIA | Annual cash benefit | Participating plan with flexible premium terms |
Note: Illustrated returns above are non-guaranteed and based on the Life Insurance Association (LIA) benchmark rates. Actual returns depend on par fund performance. Capital and guaranteed portions are protected under SDIC up to S$500,000 per person per insurer.
How the Par Fund Affects Your Annual Payouts
Income endowment plans are almost always participating (par) plans. When you buy a par plan, your premiums go into a pooled par fund alongside thousands of other policyholders. The insurer invests this pool across bonds, equities and property. Each year, it declares a bonus — called a reversionary bonus or cash benefit — that is added to your policy.
The critical point is that par fund bonuses are not guaranteed. Insurers smooth returns over time, which means your bonus does not crash when markets fall — but it also does not spike when markets rally. For income endowment plans, this smoothing matters: even if interest rates fall sharply after a rate cut, your annual payout is unlikely to drop overnight. However, the insurer may gradually reduce bonus rates over subsequent years as the par fund adapts to the new rate environment.
This is one reason income endowment plans behave differently from short-term lump-sum endowments, where a new lower-rate tranche directly reprices your return if you buy after a rate cut.
The guaranteed portion of an income endowment payout — specified in the policy schedule — is protected by SDIC and will not change regardless of what happens in markets or interest rates.
FOMC September 2026 & What It Means for Income Endowment Plans
The US Federal Reserve meets on 17–18 September 2026. As at the time of writing, market pricing assigns significant probability to a rate cut. For Singapore endowment plan buyers, the FOMC decision matters for two reasons.
Short-term lump-sum endowments reprice quickly. Non-par lump-sum endowments (like the AIA #Wealth Savvy IV at 2.80% p.a. for 3 years) are issued in tranches. Once a tranche closes, the insurer launches a new one at a rate that reflects the new interest rate environment — typically within 4 to 8 weeks of a FOMC decision. If rates are cut, the next new-tranche yield will almost certainly be lower.
Income endowment plans are more insulated — but not immune. Because income endowment plans are par plans, they smooth rate changes through the par fund. If you already hold one, your payouts do not immediately drop after a rate cut. However, if you are thinking of starting a new income endowment plan, the illustrated (non-guaranteed) rates in the product illustration you receive from the insurer reflect current par fund conditions — which in turn are influenced by prevailing interest rates. A period of sustained low rates will eventually flow through to lower bonus declarations.
The takeaway: If you plan to start an income endowment plan, doing so before FOMC locks you in at current par fund contribution rates and illustrated bonus projections, rather than the lower projections that may follow a sustained rate cut.
Should You Buy an Income Endowment Plan Now or Wait?
There is no single right answer — it depends on your income needs and timeline. Here is a practical framework.
Buy now if: You have identified a specific income need starting in the next 5–10 years. You want to lock in current illustrated bonus rates and par fund performance assumptions before they are revised downward. You prefer predictable annual payouts over managing market-linked investments.
Wait if: You are still building up your emergency fund and cannot commit to a multi-year premium schedule. You expect income needs to shift significantly over the next 1–2 years. You want to see whether rates stabilise after FOMC before committing to a long-term policy.
One important nuance: unlike short-term lump-sum endowments — where you can sometimes wait a few weeks for a higher-yielding tranche — income endowment plans are long-term commitments. Timing the market precisely is far less useful than choosing the right plan structure, premium term and payout frequency for your goals.
If you are comparing an income endowment plan against other income options in Singapore, read our related guides: 7 types of Singapore savings plans ranked, should you lock in your endowment before the rate cut, and the single premium endowment plan guide.
How to Apply for an Income Endowment Plan in Singapore
Most income endowment plans in Singapore can be applied for directly through the insurer’s website or through an Endowus or Syfe investment account for plans offered via those platforms. Here is what to expect.
Step 1 — Compare plans. Use the comparison table above as a starting point. Ask for a Benefit Illustration (BI) from each insurer. The BI shows the guaranteed payout, the illustrated (non-guaranteed) payout at 3.25% p.a. and 4.75% p.a. return scenarios, and the surrender value at each year. Always compare BIs on the same premium amount and term.
Step 2 — Check SRS eligibility. If you want to use Supplementary Retirement Scheme funds, confirm the specific plan accepts SRS top-ups. Not all income endowment plans do.
Step 3 — Apply with your insurer or platform. For Endowus, use referral code 2V343 when signing up to get a fee waiver. For Syfe, use code SRPRFFFCD. Both platforms give access to a range of insurance savings plans alongside investment products.
Step 4 — Complete the health declaration. Income endowment plans typically require a simple health declaration rather than a full medical exam. This is usually completed online.
Step 5 — Fund and activate. Pay your first premium via PayNow, FAST bank transfer or GIRO. Your policy becomes active once the insurer confirms receipt and issues your policy schedule.
Start Your Income Endowment Plan — Use Our Referral Codes
Frequently Asked Questions
What is the difference between a par and non-par income endowment plan?
Are income endowment plan payouts protected by SDIC?
Can I use SRS funds to pay for an income endowment plan?
What happens if I surrender my income endowment plan early?
How does the FOMC rate cut affect income endowment plans?
Is an income endowment plan better than a Singapore Savings Bond for regular income?
This article is for general information only and does not constitute financial advice. Endowment plan rates, bonus declarations and tranche availability change frequently. Consult a MAS-licensed financial adviser before making any insurance or investment decision. The Kopi Notes may receive referral fees when you use our referral codes, at no extra cost to you.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.