How to Invest in Singapore: Building an S-REIT Portfolio for Passive Income (2026)
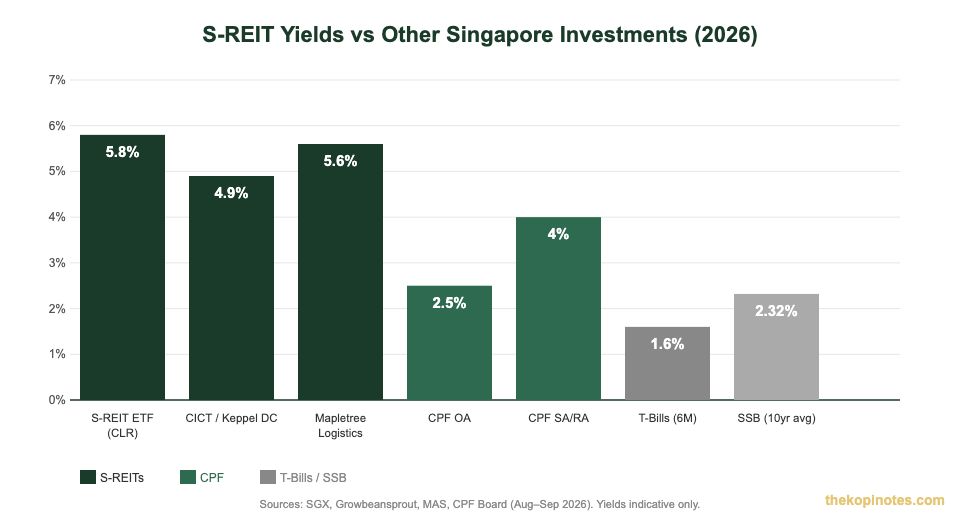
S-REITs (Singapore Real Estate Investment Trusts) are one of the most accessible ways to build passive income in Singapore. They are listed on the SGX, pay distributions quarterly or semi-annually, and these distributions are tax-exempt for individual investors. The typical yield ranges from 4.9% to 6.2% per annum, significantly higher than CPF OA (2.5%), T-bills (around 1.60%), or Singapore Savings Bonds. Best of all, there is no capital gains tax in Singapore — so any price appreciation you earn is entirely yours to keep.
Not financial advice. All figures are for educational reference only. Data verified as at 11 September 2026.
- S-REITs pay tax-exempt distributions to individual investors — what you see is what you keep.
- Typical yields of 5–6% p.a. far exceed CPF OA, T-bills, and SSB in 2026.
- You can start with as little as the price of one lot (100 units) on SGX via IBKR, moomoo, or FSMOne.
What Is an S-REIT?
A REIT is a company that owns income-generating real estate. It pools money from investors to buy properties — shopping malls, office buildings, data centres, hospitals, warehouses — and pays out the rental income as distributions.
In Singapore, REITs are regulated by MAS and listed on the SGX. There are over 40 S-REITs and property trusts covering nearly every real estate sector. They are required by MAS rules to distribute at least 90% of their taxable income each year to maintain their tax-exempt status. That rule is why S-REIT yields are so consistently high compared to ordinary stocks.
Key terms you will encounter:
- DPU (Distribution Per Unit) — how much cash each unit pays you per distribution period. Multiply this by the number of units you own to find your income.
- Distribution yield — DPU ÷ unit price × 100. A 5% yield on a $2.00 unit means 10 cents DPU per year.
- Gearing ratio — total debt ÷ total assets. MAS sets the standard limit at 45% (extendable to 50% if the REIT’s Interest Coverage Ratio is at least 2.5×).
- NAV (Net Asset Value) — the book value of the REIT’s property portfolio per unit. Trading below NAV means you may be buying properties at a discount.
The Tax Advantages of S-REITs
This is the part that surprises many first-time S-REIT investors. Unlike dividends from ordinary companies, S-REIT distributions paid to individual investors are fully tax-exempt in Singapore. You pay no income tax on the DPU you receive.
There is one condition: you cannot be receiving the distributions through a Singapore partnership or in the course of carrying on a trade or business. For a regular retail investor buying units through a brokerage account, you are fine.
On top of the income tax exemption, Singapore has no capital gains tax. If you buy CICT at $2.20 and sell at $2.50, the $0.30 gain is entirely yours — no tax to declare. This applies to all Singapore-listed investments, not just REITs.
Compare this to the UK, Australia, or the US, where REIT distributions are taxed as ordinary income. For a Singapore investor, S-REITs are genuinely one of the most tax-efficient income investments in the world.
Key S-REITs to Know in 2026
There are more than 40 S-REITs on the SGX. Here are four of the most widely held, spanning different property sectors, with their approximate indicative yields as at August 2026.
| REIT (SGX Code) | Sector | Indicative Yield | Gearing (approx.) |
|---|---|---|---|
| CapitaLand Integrated Commercial Trust (C38U) | Retail & Office | ~4.9% | ~38% |
| Mapletree Logistics Trust (M44U) | Logistics / Industrial | ~5.6% | ~40% |
| Keppel DC REIT (AJBU) | Data Centres | ~4.9% | ~35% |
| Parkway Life REIT (C2PU) | Healthcare | ~3.4% | ~36% |
Source: SGX, Growbeansprout, company announcements (August 2026). Yields are indicative and based on trailing DPU at market prices. Gearing figures approximate.
A few things to notice. First, yields vary quite a bit — from 3.4% for Parkway Life (defensive, consistent DPU growth) up to 5.6% for Mapletree Logistics Trust (which has faced some softness in Chinese logistics). Higher yield often means the market has some concern about the REIT’s outlook. Lower yield often signals stability and growth quality.
Second, all four REITs have gearing well below the MAS standard limit of 45%. That headroom matters — it means they can still raise debt for acquisitions without hitting the regulatory ceiling, which is important for future DPU growth.
Want a broader shortlist? Check out the best S-REITs in Singapore 2026 for a more detailed comparison across 10+ REITs.
S-REIT ETFs: A Simpler Way to Invest
Picking individual REITs takes research. You need to read quarterly reports, track DPU trends, and watch out for sector-specific risks. If that sounds like too much work, S-REIT ETFs offer instant diversification.
An S-REIT ETF is a fund that holds a basket of Singapore REITs, listed on the SGX just like any stock. You buy one unit and you are effectively invested across 20–30 different S-REITs at once. Two main options in 2026:
| ETF | SGX Code | TER | Indicative Yield | Distribution |
|---|---|---|---|---|
| Lion-Phillip S-REIT ETF | CLR | 0.60% p.a. | ~5.5–5.8% | Semi-annual |
| CSOP iEdge S-REIT Leaders ETF | SRT | ~0.54% p.a. | ~5.8–6.2% | Semi-annual |
Source: Growbeansprout, fund factsheets (September 2026). TER and yield are indicative; check official fund documents before investing.
The TER of 0.54–0.60% is the annual cost drag on your return, deducted automatically from the fund’s NAV. For a deeper dive, read the Singapore REIT ETF guide on TKN.
One practical note: the ETF route is great for beginners. Individual REIT picking is better once you have a feel for how different sectors — retail, industrial, healthcare, data centres — behave differently through economic cycles.
How to Buy S-REITs in Singapore
S-REITs are bought and sold on the SGX exactly like regular stocks. You need a brokerage account. Here are the main platforms Singapore investors use in 2026:
| Broker | SGX Commission | Min Trade Cost | Good For |
|---|---|---|---|
| IBKR Singapore | 0.05–0.08% | S$1.50 | Active / large trades |
| moomoo SG | 0.03% | S$0.99 | Low-cost frequent buyers |
| FSMOne | 0.08% | S$10 | RSP / auto-invest |
| Syfe Trade | 0.04–0.06% | S$1.98 | Beginners via Syfe app |
Source: Official broker pricing pages (September 2026). Commissions exclude platform fees, clearing fees, and GST. Verify directly with the broker before trading.
S-REITs are traded in lots of 100 units on the SGX. If CICT is priced at S$2.20 per unit, one lot costs S$220. That makes S-REITs accessible — you do not need tens of thousands to get started.
You can use your FSMOne referral code (P0544985) or Syfe referral code (SRPRFFFCD) if you are opening a new account. Both offer sign-up bonuses for new users. If you already use Endowus for your CPF or SRS investing, see the Endowus referral code (2V343) for the latest bonus offer.
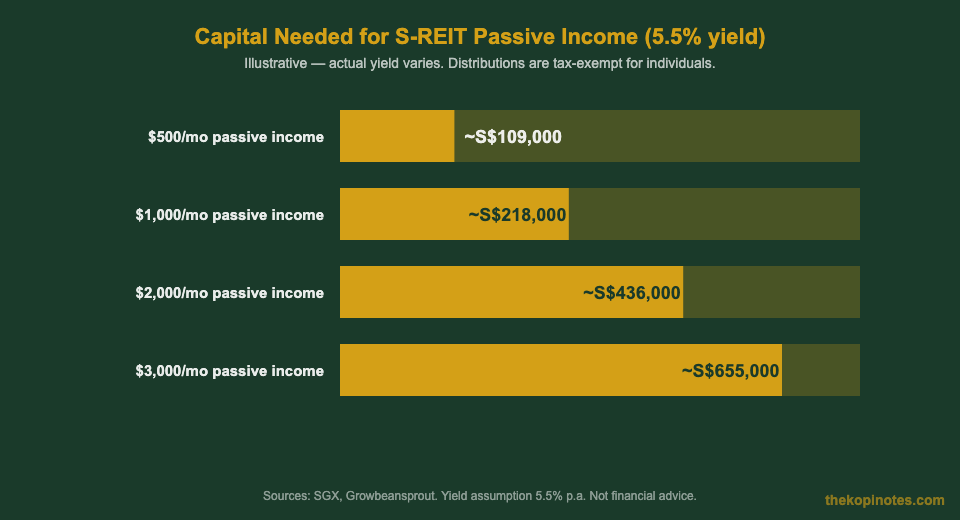
How Much Capital Do You Need?
At a 5.5% average yield, you need roughly S$218,000 invested to generate S$1,000 per month in S-REIT distributions. That is a realistic long-term target for most investors — not something you achieve in a year, but something you can build towards systematically over 5–10 years.
Consider a concrete example: invest S$500 per month into CLR via an FSMOne RSP. At 5.5% average yield and 2% average capital appreciation over 10 years, your portfolio could grow to around S$83,000, generating approximately S$380 per month in distributions. That is meaningful supplementary income, and it is tax-free.
The key insight is that you do not need to reach your full target capital before you start earning. S-REITs pay distributions as you go. Every S$10,000 invested at 5.5% generates S$550 per year — about S$46 per month. Small amounts compound into larger ones over time.
For a full breakdown of passive income targets and capital requirements across different asset classes, see the passive income Singapore 2026 guide. Use the Singapore retirement planning calculator to model how S-REITs fit into your overall retirement picture.
S-REITs vs CPF: Do Not Think Either/Or
A common question: should I top up CPF SA/RA instead of buying S-REITs? The answer depends on your age and goals. CPF SA earns 4.0% per annum (guaranteed through 31 December 2026) and SA top-ups earn tax relief up to S$8,000 per year. S-REITs yield more (5–6%) but carry market risk — your capital can go up or down.
The better framework is to do both. Use CPF for the guaranteed foundation. Use S-REITs for the higher-yielding layer on top. For more on the CPF side, read the CPF investment strategy guide.
Risks to Watch For
S-REITs are not risk-free. Here are the four main risks to understand before investing.
1. Interest Rate Risk
S-REITs borrow money to buy properties. When interest rates rise, their borrowing costs go up — that squeezes the DPU they can pay out. This is exactly what happened in 2022–2023 when the Fed hiked rates aggressively and many S-REITs saw DPU decline 5–15%. As of September 2026, global interest rates are on a declining trend, which is positive for S-REIT distributions in coming quarters.
2. Gearing Risk
MAS caps S-REIT gearing at 45% of total assets (extendable to 50% with an ICR of at least 2.5×). A REIT approaching 44–45% gearing has very little room for new acquisitions. If property values fall at the same time, a REIT could be forced to do a rights issue — selling new units at a discount and diluting your stake. Always check a REIT’s gearing ratio before buying. A gearing below 35–38% is generally comfortable.
3. Sector and Tenant Risk
A retail REIT with major tenants closing stores faces lower occupancy and lower DPU. A logistics REIT with Chinese warehouses faces overcapacity risk. Different S-REIT sectors move differently. Diversifying across sectors — retail, industrial, healthcare, data centres — reduces the risk of any one sector hurting your income.
4. Currency Risk
Many S-REITs own properties outside Singapore — Australia, Japan, the UK, the US. When those foreign currencies weaken against the Singapore dollar, the DPU translated back to SGD shrinks. Look at a REIT’s geographic mix to understand your currency exposure before buying.
Frequently Asked Questions
Are S-REIT distributions taxable in Singapore?
What is the minimum amount to invest in an S-REIT?
Can I invest in S-REITs using CPF?
What is a good S-REIT yield?
What is the MAS gearing limit for S-REITs?
Is now a good time to buy S-REITs in 2026?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.