Keppel DC REIT Share Price 2027: Analyst Targets, Valuation & Investment Thesis
Current price ~S$2.10 · Yield ~4.7% · P/NAV ~1.15x · FY2027E DPU 10.35¢Keppel DC REIT (SGX: AJBU) is Singapore’s largest pure-play data centre REIT, with a portfolio spanning 23 assets across 9 countries and a market cap above S$3.5 billion as at October 2026. With current price near S$2.10, a 4.7% forward yield, and analyst consensus pointing to a base-case target of S$2.25–S$2.45 for 2027, KDC REIT remains a core holding for Singapore investors seeking digital infrastructure exposure. This guide breaks down the key valuation drivers, DPU outlook, and analyst scenarios for 2027.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
KDC REIT At a Glance (October 2026)
Keppel DC REIT listed on the SGX in December 2014 as Asia’s first listed data centre REIT. Its portfolio has grown from 8 assets at IPO to 23 assets as of Q3 2026, with AUM exceeding S$4.2 billion. The REIT benefits from secular tailwinds: AI workload growth, cloud migration, and Southeast Asia’s rapid digitalisation.
| Metric | Value (Oct 2026) |
|---|---|
| SGX Code | AJBU |
| Share Price | ~S$2.10 |
| Market Cap | ~S$3.8 billion |
| Forward Yield (FY2026E) | ~4.7% |
| P/NAV | ~1.15x |
| Gearing Ratio | ~36.5% |
| WALE (by NLA) | ~7.8 years |
| Portfolio Occupancy | ~97.8% |
| No. of Assets | 23 across 9 countries |
Source: KDC REIT 2026 interim results, SGX filings, analyst estimates.
DPU History & 2027 Forecast
KDC REIT’s DPU trajectory reflects consistent organic rent escalation and accretive acquisitions. FY2025 delivered 9.51¢, a recovery from the slight FY2024 dip driven by FX headwinds on European assets. With new Singapore co-location contracts kicking in H2 2026 and AI demand underpinning pricing power, analysts forecast FY2026E at 9.85¢ and FY2027E at 10.35¢ — a +8.8% uplift from FY2025.
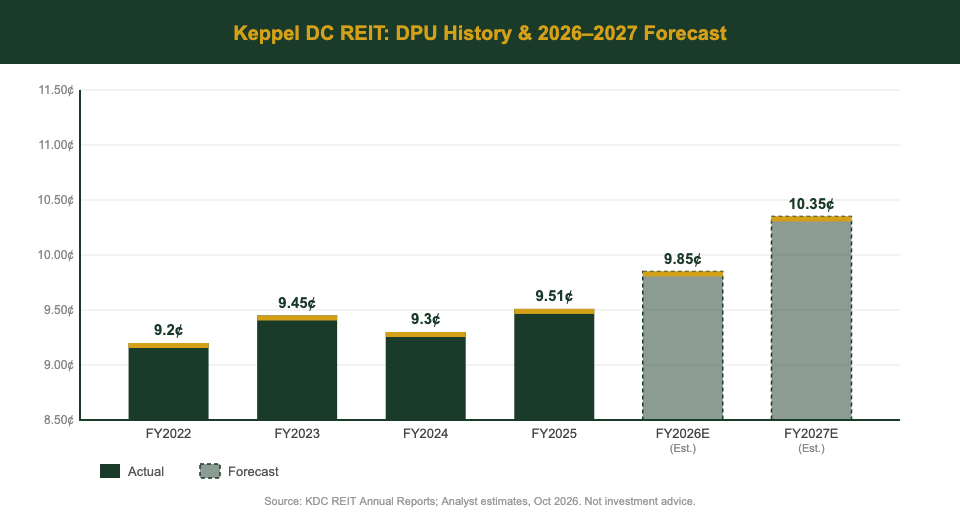
| Financial Year | DPU (Singapore Cents) | YoY Change |
|---|---|---|
| FY2022 (actual) | 9.20¢ | — |
| FY2023 (actual) | 9.45¢ | +2.7% |
| FY2024 (actual) | 9.30¢ | −1.6% |
| FY2025 (actual) | 9.51¢ | +2.3% |
| FY2026E (forecast) | 9.85¢ | +3.6% |
| FY2027E (forecast) | 10.35¢ | +5.1% |
Source: KDC REIT SGX filings (FY2022–FY2025); analyst consensus estimates (FY2026E–FY2027E). Forecasts are indicative only.
For context on what drives this DPU growth, see our detailed analysis of KDC REIT’s 5 key catalysts and investment case — covering AI demand, new capacity commitments, and Singapore co-location rent step-ups.
Analyst Price Target Scenarios for 2027
With the current share price around S$2.10, KDC REIT trades at a modest premium to NAV (~1.15x). Analyst consensus as at October 2026 clusters around three scenarios for 2027, reflecting divergent views on interest rate trajectories, AI-driven data centre demand, and European portfolio performance.
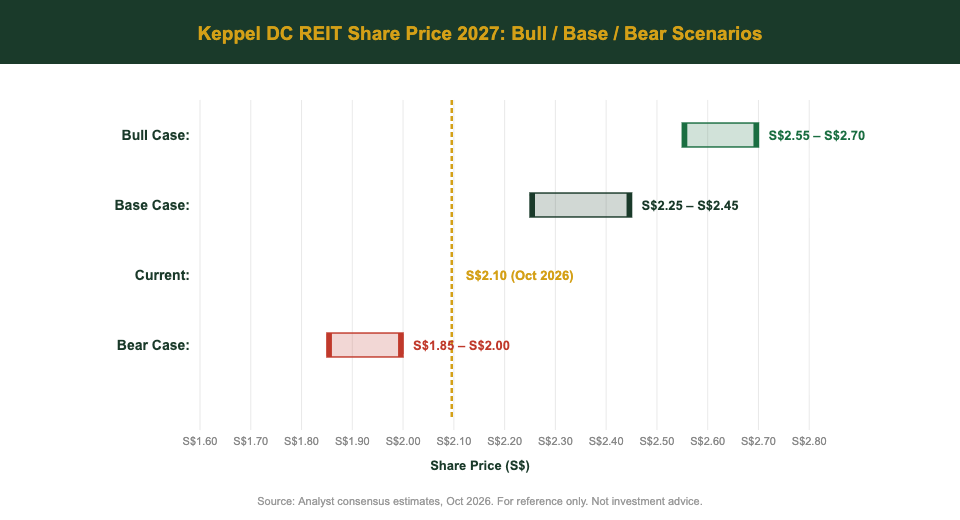
| Scenario | Price Target Range | Upside from S$2.10 | Key Assumption |
|---|---|---|---|
| Bull Case | S$2.55 – S$2.70 | +21% to +29% | Fed rate cuts + AI hyperscaler demand acceleration + Singapore asset revaluation |
| Base Case | S$2.25 – S$2.45 | +7% to +17% | Stable rates, organic DPU growth, moderate P/NAV re-rating to ~1.25x |
| Bear Case | S$1.85 – S$2.00 | −12% to −5% | Rates stay elevated, European asset devaluations, DPU misses on FX drag |
Source: Analyst consensus estimates, October 2026. Compiled from broker research. Not a recommendation.
The base case implies a 2027 forward yield of ~4.2–4.4% at the midpoint of S$2.35 — a slight compression from current levels but consistent with the historical KDC REIT yield band of 4.0–5.5%. Investors seeking yield-plus-growth exposure to the data centre theme may find the current entry attractive relative to the base scenario.
Valuation: P/NAV and Yield Spread Analysis
KDC REIT’s current P/NAV of ~1.15x is below its 3-year average of ~1.35x, suggesting the share price has not fully re-rated to reflect the portfolio’s higher earnings capacity. The yield spread over Singapore’s 10-year government bond yield (approximately 3.1% as at October 2026) sits at ~160 basis points — above the 5-year median of ~130 bps, indicating residual value relative to risk-free alternatives.
| Valuation Metric | Current | 3-Year Average | Assessment |
|---|---|---|---|
| P/NAV | 1.15x | 1.35x | Discount to avg |
| Forward Yield | 4.70% | 4.10% | Above avg |
| Yield Spread vs SGB 10Y | ~160 bps | ~130 bps | Wide (attractive) |
| EV/EBITDA (est.) | ~22x | ~24x | Below avg |
Source: SGX filings, MAS statistics, analyst consensus. Data as at October 2026.
For a deeper dive on KDC REIT’s gearing position and debt maturity profile — which directly impacts its capacity for accretive acquisitions that would drive the bull case — see our analysis of KDC REIT’s gearing and 2027 debt management.
Investment Thesis for 2027
The bull thesis for KDC REIT heading into 2027 rests on three structural pillars. First, AI compute demand continues to outpace new data centre supply in Singapore and Oceania, driving rental escalations above the REIT’s contractual step-ups. Second, Keppel’s pipeline of development assets — approximately 90MW of capacity under development across Singapore and Australia — provides a clear runway for DPU accretion upon completion in 2026–2027. Third, rate normalisation in the US and Europe reduces the REIT’s refinancing cost burden and expands the yield spread, making the stock more attractive relative to bonds.
For Singapore retail investors with a 3-year horizon, KDC REIT occupies a unique position: it is the only pure-play listed data centre REIT on the SGX, providing sector-specific exposure that cannot be replicated through diversified S-REIT ETFs. To understand how KDC REIT stacks up against other best S-REITs in Singapore for 2026, its data centre focus sets it apart from retail and industrial peers.
The REIT’s AI and power infrastructure angle is covered in depth in our piece on KDC REIT’s power capacity expansion and AI demand drivers.
Key Risks to Monitor in 2027
No investment comes without risk. For KDC REIT, the four risks most likely to drive the bear case are: (1) sustained elevated interest rates increasing the refinancing cost on ~S$1.3 billion of debt maturing in 2026–2028; (2) FX headwinds from EUR/AUD weakness reducing SGD-translated DPU from European and Australian assets; (3) hyperscaler build-outs of proprietary data centres reducing third-party co-location demand in key markets; and (4) Singapore government regulatory changes on data centre power consumption, which could constrain the REIT’s brownfield expansion pipeline.
Investors monitoring the passive income angle should also read our guide on building passive income in Singapore, which contextualises S-REIT yields relative to CPF and fixed income alternatives for retirement planning.
Portfolio Fit for Singapore Investors
KDC REIT is well-suited for growth-income investors who want thematic data centre exposure within an SGX-listed, SGD-denominated wrapper. At a ~4.7% yield, it sits below typical S-REIT averages (5–6%) but offers higher earnings growth potential. It is most appropriate as a 5–15% satellite allocation within a diversified S-REIT portfolio, complementing higher-yielding industrial or retail REITs.
For retirement planning purposes, the projected 2027 DPU of 10.35¢ on a S$50,000 investment at current prices (~23,810 units) would generate approximately S$2,464 per year in distributions — a useful passive income supplement. Use our Singapore retirement calculator to model how KDC REIT distributions could contribute to your retirement income goal.
How to Buy Keppel DC REIT in Singapore
KDC REIT (SGX: AJBU) trades on the Singapore Exchange and can be purchased through any SGX-connected brokerage. For Singapore retail investors, three platforms offer competitive pricing:
Syfe Trade — low commissions for SGX stocks with a clean mobile interface. New investors can use the Syfe referral code SRPRFFFCD for a fee waiver on first trades. FSMOne — integrates stocks, REITs and ETFs in one account. Sign up via the FSMOne referral code P0544985. Endowus — for CPF-OA investors seeking to invest CPF savings into KDC REIT via approved CPFIS; use the Endowus referral code 2V343 for a fee rebate.
Minimum lot size on SGX is 100 units (~S$210 at S$2.10), making KDC REIT accessible for investors dollar-cost averaging into the position over time.
Frequently Asked Questions
What is the Keppel DC REIT share price target for 2027?
Is Keppel DC REIT a good buy in 2026?
”What
”How
Start Investing in KDC REIT Today
Open a brokerage account and get exclusive sign-up bonuses through The Kopi Notes referral links.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.