MediSave Limit 2026: Retirement Healthcare Planning for Singapore Seniors
How to maximise your MediSave savings and build a bulletproof retirement healthcare plan using the 2026 BHS of $79,000, Integrated Shield Plans, and CareShield Life.
The MediSave limit in 2026 — formally known as the Basic Healthcare Sum (BHS) — is $79,000 for CPF members below 65 or turning 65 in 2026. Once your MediSave balance reaches this cap, excess contributions are redirected to your Special Account or Retirement Account. For Singapore seniors, knowing this limit is essential: it determines how much you can use for hospitalisation, Integrated Shield Plan premiums, rehabilitation, and CareShield Life top-ups throughout your retirement years.
Not financial advice. All figures are for educational reference only. Data verified against CPF Board and MOH official sources as at October 2026.
Table of Contents
- What Is the MediSave Limit in 2026?
- Understanding the Basic Healthcare Sum (BHS) in 2026
- How Seniors Use MediSave for Hospitalisation
- Integrated Shield Plan Premiums in Retirement
- Rehabilitation and Step-Down Care Limits
- MediSave Care for Severe Disability
- Top 5 Strategies to Maximise MediSave in Retirement
- Frequently Asked Questions
What Is the MediSave Limit in 2026?
In Singapore’s CPF system, MediSave is a dedicated healthcare savings account that all working Singaporeans and PRs contribute to. The “MediSave limit” commonly referred to is the Basic Healthcare Sum (BHS) — the maximum balance you can hold in MediSave before excess contributions are automatically redirected to your other CPF accounts.
The BHS is revised upward every year by the CPF Board to keep pace with rising healthcare costs and increasing life expectancy. For 2026, the BHS is set at $79,000 — up from $75,500 in 2025. This applies to all CPF members below 65 years old, as well as members who turn 65 in 2026.
A critical feature of the BHS: once you turn 65, your BHS is fixed for life at the prevailing rate in the year you turned 65. This has important implications for seniors:
- A member who turned 65 in 2024 has a fixed BHS of $71,500 — they do not benefit from future BHS increases.
- A member turning 65 in 2026 has a fixed BHS of $79,000 for the rest of their retirement.
- CPF members still below 65 will see their BHS ceiling rise each year until they turn 65.
The BHS also earns a guaranteed interest rate of 4% per annum — one of the most competitive risk-free rates in Singapore. Use our Singapore retirement calculator to project how your MediSave grows alongside your CPF OA and SA savings over time.
Understanding the Basic Healthcare Sum (BHS) in 2026
The BHS is calibrated by CPF Board actuaries to estimate the amount needed to cover a member’s expected healthcare expenses throughout retirement. Here is how the BHS has progressed across recent cohorts:
| Cohort | Fixed BHS | Status |
|---|---|---|
| Turned 65 in 2023 | $68,500 | Fixed for life |
| Turned 65 in 2024 | $71,500 | Fixed for life |
| Turned 65 in 2025 | $75,500 | Fixed for life |
| Turning 65 in 2026 | $79,000 | Fixed at 2026 BHS |
| Below 65 in 2026 | $79,000 | Current cap; rises annually |
Source: CPF Board, cpf.gov.sg/bhs (October 2026)
The practical implication: younger Singaporeans will retire with a higher fixed BHS, giving them more MediSave to draw upon. If you are approaching 65, it may be worth making voluntary top-ups to your MediSave now to maximise your balance before it becomes fixed.
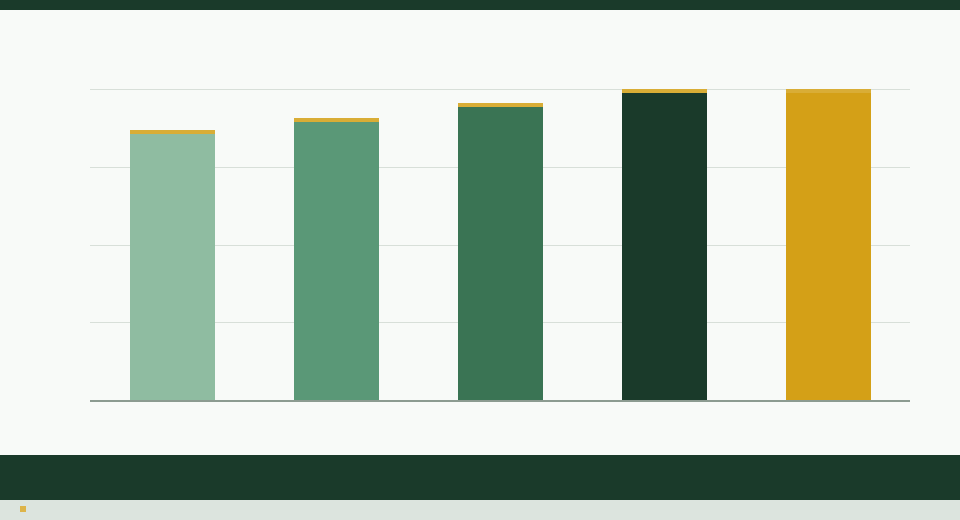
Members who turned 65 in prior years have their BHS fixed at that year’s level. The 2026 BHS of $79,000 applies to those turning 65 this year or below 65. Source: CPF Board.
How Seniors Use MediSave for Hospitalisation
The largest single draw on MediSave in retirement is hospitalisation. In 2026, the MediSave hospitalisation limits are:
| Service | MediSave Limit (2026) |
|---|---|
| Inpatient — first 2 days | $1,130/day |
| Inpatient — day 3 onwards | $400/day |
| Day surgery | Up to $830/day |
| Per-admission limit (below age 40) | $25,000 |
| Per-admission limit (ages 40–50) | $30,000 |
| Per-admission limit (ages 51–60) | $40,000 |
| Per-admission limit (ages 61–70) | $50,000 |
| Per-admission limit (above age 70) | $55,000 |
| Annual hospitalisation limit | $55,000 |
Source: CPF Board MediSave limits, cpf.gov.sg (October 2026)
In practice, a senior aged 70+ admitted for a 5-day inpatient stay would have MediSave cover: (2 days × $1,130) + (3 days × $400) = $3,460 toward ward fees, plus applicable surgical or procedure limits. MediShield Life and an Integrated Shield Plan then layer on top, covering the bulk of remaining eligible bills.
This is why maintaining a comprehensive integrated shield plan Singapore 2026 into retirement is so important — the MediSave daily limits cover only a fraction of actual private hospital ward charges, which can easily run to $800–$2,000 or more per day.
Integrated Shield Plan Premiums in Retirement
One of the most powerful retirement uses of MediSave is paying for Integrated Shield Plan (ISP) premiums. MediSave covers the full cost of the basic ISP plan, allowing retirees to maintain hospitalisation insurance coverage even after earned income ceases.
ISPs consist of two components: the basic plan (100% payable by MediSave) and a rider that waives or reduces your co-payment share. MediSave can only be used for rider premiums up to the Additional Withdrawal Limit (AWL), which increases with age:
| Age Group | AWL for ISP Rider | Cash for Any Excess |
|---|---|---|
| Ages 1–40 | $300/year | Rider premium above $300 |
| Ages 41–70 | $600/year | Rider premium above $600 |
| Ages 71 and above | $900/year | Rider premium above $900 |
Source: CPF Board, cpf.gov.sg (October 2026)
For a 72-year-old retiree with an ISP rider costing $1,500/year, MediSave covers $900 and the remaining $600 must be paid in cash. To compare which ISP offers the best protection-to-premium ratio for seniors, see our best integrated shield plan Singapore guide.
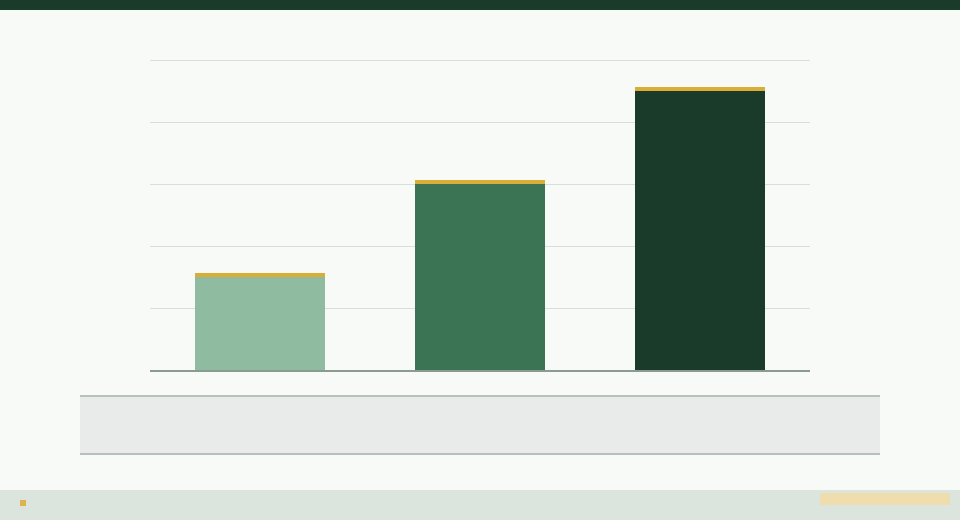
AWL for ISP rider premiums: $300/year (ages 1–40), $600/year (41–70), $900/year (71+). Source: CPF Board (October 2026).
Rehabilitation and Step-Down Care Limits
Seniors recovering from surgery, strokes, or falls often require extended rehabilitation. MediSave covers several step-down care settings:
- Community hospital inpatient rehabilitation: Up to $250/day
- Convalescent hospital (inpatient): Up to $50/day, capped at $3,000/year
- Day rehabilitation centre (outpatient): Up to $25/day per service type, capped at $1,500/year
- Day hospital outpatient complex care: Up to $150/day, capped at $3,000/year
Community hospitals — including St Luke’s Hospital, Ren Ci Hospital, and Bright Vision Hospital — charge $250–$400 per day for subsidised beds. MediSave’s $250/day limit covers a significant portion, though an ISP rider may also contribute depending on your plan’s benefits.
One key planning note: MediSave does not cover all outpatient rehabilitation. Standalone physiotherapy or occupational therapy sessions at GP clinics are generally not claimable unless packaged within an approved MediSave-claimable programme. For the bigger retirement financing picture, see our CPF investment strategy guide.
MediSave Care for Severe Disability
For seniors who become severely disabled — needing help with at least 3 out of 6 Activities of Daily Living (ADLs) — MediSave Care provides a monthly cash payout drawn from their own or their spouse’s MediSave savings. Key details in 2026:
- Monthly payout: Up to $200/month
- Eligibility: Assessed as needing assistance with ≥3 ADLs; minimum $5,000 in the MediSave account being drawn from
- Source: Can draw from your own MediSave or your spouse’s MediSave
MediSave Care complements CareShield Life (minimum $600/month for severe disability, indexed annually). For a full breakdown of CareShield Life, read our CareShield Life Singapore guide.
MediSave also covers hospice care at end of life: inpatient hospice at $250–$350/day, plus $2,500 lifetime for home or day hospice (payable from any immediate family member’s MediSave).
Top 5 Strategies to Maximise MediSave in Retirement
1. Make Voluntary Top-Ups Before Age 65
If your MediSave balance is below $79,000, you can make voluntary top-ups at any time, earning a guaranteed 4% per annum. Topping up before you turn 65 grows your fixed BHS and maximises the compounding runway before retirement.
2. Keep Your ISP Rider Throughout Retirement
Dropping your ISP rider to save on premiums is often a false economy. A single hospitalisation without co-payment coverage can cost tens of thousands more out-of-pocket than years of rider premiums combined. Use the MediSave AWL ($900/year for ages 71+) to offset rider costs, supplementing with cash only for the difference.
3. Claim MediSave for Chronic Disease Management (CDMP)
Under the Chronic Disease Management Programme, MediSave covers up to $500/year for outpatient treatment of chronic conditions — diabetes, hypertension, hyperlipidaemia, and more — claimable from your own or a family member’s MediSave.
4. Plan for Rehabilitation Costs in Your Healthcare Budget
Many seniors underestimate post-hospitalisation step-down care costs. At $250/day for community hospital rehabilitation, a 2-week stay costs $3,500 — partially MediSave-claimable. Build rehabilitation costs into your retirement healthcare budget and clarify coverage with your hospital’s medical social worker before discharge.
5. Pool Family Members’ MediSave When Needed
Singapore allows immediate family members to use their MediSave for your hospitalisation bills and some outpatient treatments. This family-pooling feature is especially valuable if your own MediSave is lower than the BHS. Read our guide on using MediSave for family members in Singapore for full eligibility rules.
Frequently Asked Questions
What is the MediSave limit in Singapore for 2026?
The MediSave limit in Singapore for 2026 is $79,000, which is the Basic Healthcare Sum (BHS) set by the CPF Board. This applies to CPF members below 65 years old and those turning 65 in 2026. Once your MediSave reaches $79,000, further CPF contributions are redirected to your Special Account or Retirement Account. Members who turned 65 before 2026 have their BHS permanently fixed at that year’s rate — for example, $75,500 for those who turned 65 in 2025.
How much MediSave can I use for an Integrated Shield Plan in retirement?
MediSave covers the full premium for the basic ISP plan with no cap. For the ISP rider, MediSave can be used up to the Additional Withdrawal Limit (AWL): $300/year for ages 1–40, $600/year for ages 41–70, and $900/year for ages 71 and above. Any rider premium above the AWL must be paid in cash. Note that all ISP riders sold from 2021 onwards require a mandatory 5% or 10% co-payment.
What happens to my MediSave BHS when I turn 65?
When you turn 65, your Basic Healthcare Sum is fixed for life at the BHS prevailing in that year. For example, turning 65 in 2026 permanently fixes your BHS at $79,000 — you do not benefit from future BHS increases. Your MediSave balance continues to earn 4% per annum interest and you can still make withdrawals for approved healthcare services throughout retirement.
Can I use family members' MediSave to pay my hospital bills?
Yes. MediSave rules allow immediate family members — spouse, children, parents, and grandparents — to use their MediSave to pay your hospitalisation bills, ISP premiums, and some outpatient treatments. The standard MediSave withdrawal limits still apply per admission, but pooling family MediSave balances significantly reduces your out-of-pocket cash expenses.
Is the MediSave BHS of $79,000 enough to cover all retirement healthcare costs?
The $79,000 BHS provides a meaningful healthcare reserve but is unlikely to cover all retirement healthcare costs — especially for extended private hospital stays, major surgeries, or long-term care needs. Seniors should supplement MediSave with: (1) an Integrated Shield Plan for hospitalisation, (2) CareShield Life for long-term disability, and (3) personal savings for uncovered expenses.
What can MediSave cover for long-term care and disability?
For severe disability (needing help with ≥3 ADLs), MediSave Care provides up to $200/month from your own or your spouse’s MediSave. For end-of-life care, MediSave covers inpatient hospice at $250–$350/day plus $2,500 lifetime for home or day hospice (from family MediSave). MediSave also pays CareShield Life and ElderShield premiums, and covers community hospital rehabilitation at up to $250/day.
Protect Your Retirement Healthcare
Your MediSave is powerful — but it works best paired with the right Integrated Shield Plan and CareShield Life coverage. Review your plan before premiums rise with age.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.