TribeCar + MariBank + Syfe + FSMOne + IBKR: The Minimum-Balance Free-Money Ladder (2026)
Zero-minimum platforms vs threshold-gated platforms — where should your freed-up TribeCar savings go first?
Skipping car ownership with TribeCar can free up S$500-700 a month. Route it by minimum-balance friction: MariBank and Syfe Cash+ pay you from dollar one with zero minimum, FSMOne is free for SRS but penalises small ETF trades, and IBKR pays S$0 interest until you cross S$14,000 SGD or US$10,000 — so batch transfers instead of drip-feeding it.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted. The Kopi Notes may earn a referral fee if you sign up through the links below.
- MariBank and Syfe Cash+ have zero minimum balance — your first freed-up dollar starts earning immediately.
- FSMOne is free for SRS, but ETF trades under S$11,000 pay a flat S$8.80 minimum fee — a soft penalty for small amounts.
- IBKR pays S$0 interest below S$14,000 SGD or US$10,000 — don’t drip money in weekly, save it up and transfer in one batch.
Table of Contents
What is the minimum-balance ladder?
Why TribeCar frees up cash
Step 1: MariBank (zero minimum)
Step 2: Syfe Cash+ (zero minimum)
Step 3: FSMOne (SRS free, ETF penalty)
Step 4: IBKR (the S$14,000 dead zone)
Putting it all together: the routing order
How this differs from our other 7 combos
FAQs
What is the minimum-balance ladder?
Most guides rank savings platforms by interest rate. That’s the wrong first question. Before rate, ask: does this platform pay you anything at all on the amount you actually have right now?
You could have S$500 sitting in an account with a headline 3% rate. But if that rate only kicks in above S$20,000, your S$500 earns S$0. Meanwhile, a platform paying a “boring” 0.88% from dollar one is actually earning you more today.
This article ranks four platforms — MariBank, Syfe Cash+, FSMOne, and IBKR — by exactly this: how much you need to park before the platform starts paying you anything. Two have zero minimum. One has a soft fee penalty for small amounts. One has a hard interest cliff.
Why TribeCar frees up cash in the first place
Owning a car in Singapore is expensive. Between COE, insurance, road tax, parking, and petrol, a typical car can cost you S$1,000-1,500 a month even before depreciation.
TribeCar’s car-sharing model lets you pay per use instead. If you drive less than a few times a week, switching from ownership to TribeCar can free up S$500-700 a month — sometimes more. New users get S$20 off their first booking with code zZDeg.
That’s real money. The question this article answers is: once TribeCar frees it up, where does it go first?
Step 1: MariBank — zero minimum, earns from dollar one
MariBank is a MAS-licensed Digital Full Bank. There’s no minimum balance requirement and no minimum salary crediting. You open an account, deposit S$1, and it starts earning 0.88% p.a. base rate immediately.
New users also get an enhanced rate — up to 2.48% p.a. for the first 30 days on new deposits — which decays back to the 0.88% base after the promotional window. Deposits are SDIC-insured up to S$100,000.
For your first tranche of TribeCar savings, this is the obvious landing spot. There’s no threshold to hit, no card spend to hunt, no salary crediting requirement. Use code 2DCT80WQ when signing up.
Step 2: Syfe Cash+ — also zero minimum, no lock-in
Syfe Cash+ Guaranteed is the second zero-minimum stop. It currently pays around 1.15-1.30% p.a. depending on tenor, with no minimum deposit and no lock-in — you can withdraw same-day via PayNow.
If Syfe Cash+ Guaranteed is full for your comfort level, Cash+ Flexi (around 1.6% p.a.) and Cash+ Enhanced (a bond-fund option, projected around 3.0% but carrying market risk, not SDIC-insured) sit above it as optional next tiers — but those aren’t “zero minimum, zero risk” anymore, so we keep this ladder’s first two rungs to the truly frictionless options.
Between MariBank and Syfe Cash+ Guaranteed, you’ve now placed your first S$1,000-2,000 of freed-up TribeCar savings without hitting a single minimum-balance wall.
Step 3: FSMOne — free for SRS, but a soft penalty on small ETF trades
FSMOne has no minimum balance to open an account, and Supplementary Retirement Scheme (SRS) investing through unit trusts carries a 0% sales charge. That makes it a genuinely zero-minimum option once your goal is parking SRS money (S$15,300 annual cap) for tax relief.
But FSMOne isn’t frictionless for everything. If you’re trading ETFs rather than unit trusts, the platform charges 0.08% per trade with a S$8.80 minimum fee. On a small trade, that minimum fee eats a disproportionate chunk of your money — the breakeven point where the percentage fee overtakes the flat minimum is around S$11,000 per trade.
So FSMOne belongs in Step 3 for two different reasons depending on your goal: SRS contributions can start immediately (zero minimum), but if you’re using it for ETF investing, hold off until each trade is large enough to clear that S$11,000 breakeven — otherwise you’re paying a proportionally high fee on a small amount, similar in spirit to IBKR’s threshold problem below.
Step 4: IBKR — the S$14,000 dead zone
Interactive Brokers (IBKR) is the platform with the hardest minimum-balance wall in this ladder. IBKR pays 0% interest on SGD cash balances below S$14,000, and 0% on USD cash balances below US$10,000. Below those lines, your idle cash earns nothing — not a lower rate, literally zero.
This is why IBKR should be the last stop, not the first. If you drip S$100-200 a month into IBKR the way you might into MariBank or Syfe, that money sits in the dead zone earning nothing for months or years before crossing the threshold.
Instead, let your MariBank and Syfe balances build up first, then transfer a lump sum into IBKR once you can clear S$14,000 SGD or US$10,000 in one go. Use referral code jianxiong368 when opening your account.
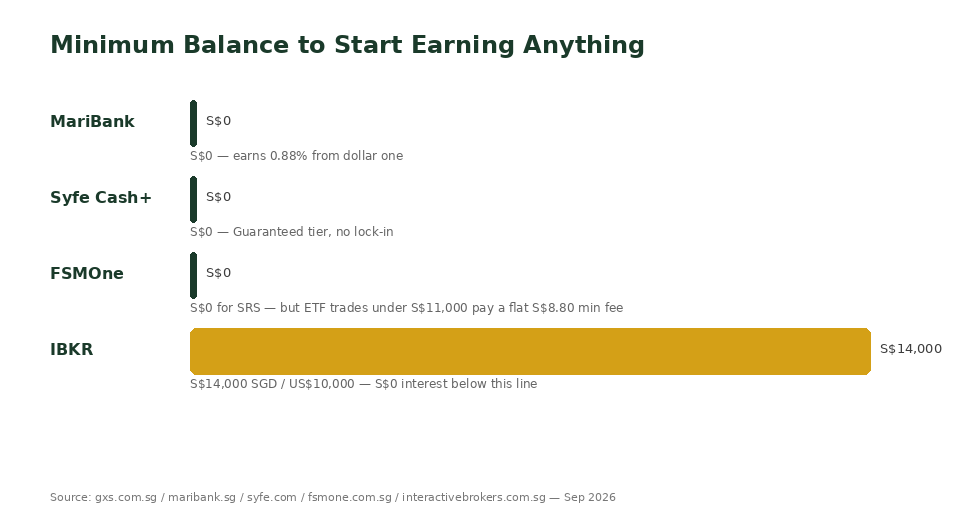
| Platform | Minimum to earn anything | Rate once earning |
|---|---|---|
| MariBank | S$0 | 0.88% base, up to 2.48% (30-day new-user) |
| Syfe Cash+ Guaranteed | S$0 | ~1.15-1.30% p.a. |
| FSMOne (SRS) | S$0 | 0% sales charge unit trusts |
| FSMOne (ETF trades) | ~S$11,000 per trade to clear fee breakeven | 0.08%, min S$8.80/trade |
| IBKR | S$14,000 SGD / US$10,000 | Tiered, 0% below threshold |
Source: maribank.sg, syfe.com, fsmone.com.sg, interactivebrokers.com.sg — verified September 2026.
Putting it all together: the routing order
Here’s how you should route each new dollar freed up by skipping car ownership, ranked purely by minimum-balance friction — not by rate, tax relief, or bonus size:
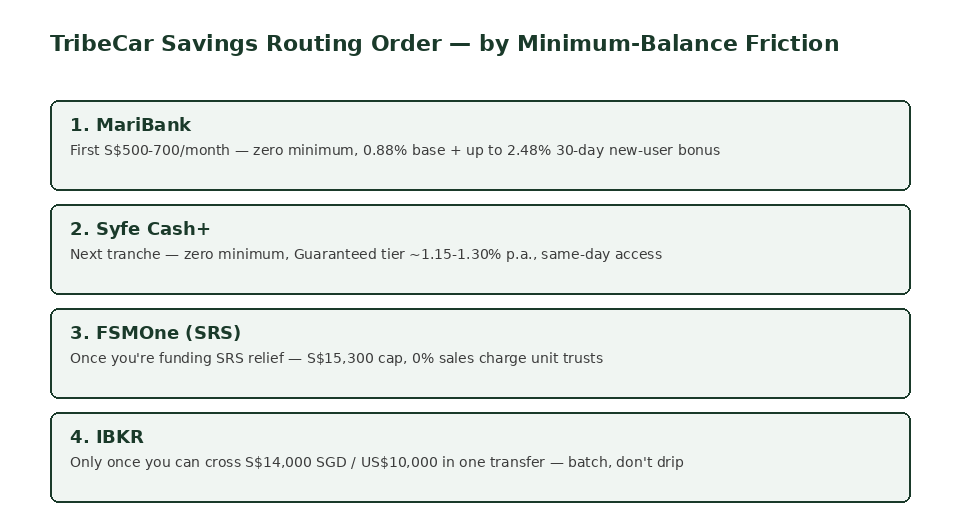
In practice, this means the first few months of TribeCar savings go entirely to MariBank and Syfe Cash+. Once you’re consistently saving and want to lock in SRS tax relief, direct new SRS contributions into FSMOne. Only once your combined idle cash can support a S$14,000-plus lump sum transfer should any of it move to IBKR.
That’s the “so what” of this whole ladder: don’t chase the highest headline rate first. Chase the platform that will actually pay you something on the amount you have today.
How this differs from our other 7 platform combos
This is our eighth 5-way platform combo built around TribeCar’s freed-up savings. Each one uses a different lens to decide the routing order:
- Purpose-tagged buckets (TribeCar + MariBank + FSMOne + GXS + Syfe)
- Next-dollar decision tree (TribeCar + Endowus + Trust Bank + FSMOne + IBKR)
- Real return after inflation (TribeCar + MariBank + Endowus + Syfe + Trust Bank)
- SRS year-end deadline calendar (TribeCar + FSMOne + GXS + Trust Bank + IBKR)
- Bonus-stacking sequence (TribeCar + MariBank + GXS + Endowus + Syfe)
- Withdrawal-speed tiering (TribeCar + Endowus + Syfe + GXS + IBKR)
- KYC/account-opening speed (TribeCar + MariBank + Trust Bank + FSMOne + GXS)
This eighth combo — TribeCar + MariBank + Syfe + FSMOne + IBKR — is the first to rank purely by minimum-balance and threshold friction: how much you need to park before a platform pays you anything at all, rather than by rate, tax cap, insurance tier, or speed.
Get started with each platform
Related reading on The Kopi Notes
If you’re building out a full cash and investing system, these guides pair well with this ladder:
- Use the Singapore retirement calculator to see how consistent monthly saving compounds over time.
- Once your SRS contributions are flowing through FSMOne, check our Singapore T-bills 2026 guide for another low-risk parking option.
- Compare fixed-income alternatives in our Singapore Savings Bonds guide.
- For the IBKR overflow tier, our Singapore REIT ETF guide covers how to deploy lump sums once you clear the interest threshold.
- See how this fits into a broader income strategy in passive income Singapore.
- If you’re weighing brokers beyond IBKR, our moomoo Singapore review is a useful comparison.
Frequently Asked Questions
Is TribeCar cheaper than owning a car in Singapore?
For most people who drive fewer than a few times a week, yes. Car ownership costs (COE, insurance, road tax, parking, depreciation) typically run S$1,000-1,500+ a month, while TribeCar charges per use. The exact savings depend on how often you drive.
Does MariBank really have no minimum balance?
Correct. MariBank has no minimum balance and no minimum salary crediting requirement. Your deposit earns the base rate of 0.88% p.a. from the first dollar, with SDIC insurance up to S$100,000.
What is Syfe Cash+ Guaranteed's interest rate right now?
As at September 2026, Syfe Cash+ Guaranteed pays approximately 1.15-1.30% p.a. depending on the tenor selected, with no minimum deposit and no lock-in period.
Why does FSMOne charge more on small ETF trades?
FSMOne charges 0.08% per ETF trade with a S$8.80 minimum fee. On trades below roughly S$11,000, that S$8.80 minimum represents a higher effective percentage than 0.08%, which is why small ETF trades are relatively more expensive there.
What happens if I keep less than S$14,000 in my IBKR SGD account?
You earn 0% interest on that SGD balance. IBKR only starts paying interest on SGD cash above S$14,000, and on USD cash above US$10,000. Below those thresholds, idle cash sits earning nothing.
Should I still open an IBKR account if I don't have S$14,000 yet?
You can open the account and use it for equity trades, but avoid parking idle cash there until you can transfer in a lump sum above the threshold. Build up your balance in MariBank or Syfe first.
Is FSMOne good for SRS contributions specifically?
Yes. SRS investing through FSMOne’s unit trusts carries a 0% sales charge, and there’s no minimum balance to open the account, making it a genuinely zero-minimum option for your annual S$15,300 SRS cap.
How is this combo different from your other TribeCar platform guides?
This is the eighth 5-way combo in our TribeCar savings series. Prior combos ranked platforms by purpose, tax deadlines, withdrawal speed, or account-opening speed. This one is the first built entirely around minimum-balance and threshold friction.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.