FSMOne vs MariBank Singapore 2026: Invest Your Cash or Just Park It?
MariBank pays a flat 0.88% p.a. on idle cash with zero conditions and SDIC insurance up to S$100,000. FSMOne charges 0% sales charge on unit trusts (plus a ~0.35% p.a. platform fee) and 0.08% (minimum S$8.80) on SGX stock and ETF trades — but it’s the only one of the two that lets you invest CPF and SRS money at all.
Not financial advice. All figures are for educational reference only and are correct as at November 2026 unless otherwise noted.
Why this comparison isn’t really “either/or”
FSMOne and MariBank get searched together because both show up on every “where do I put my spare cash” shortlist in Singapore — but they solve different problems. MariBank is a digital bank savings account: you deposit cash, it pays interest, and that’s the whole product. FSMOne (rebranded FSM Global) is an investing platform: you buy unit trusts, ETFs, bonds and SGX stocks, and your return depends on what those instruments do in the market.
The useful question isn’t “which pays more” — it’s “which job does each one do, and does either of them actually let you use CPF or SRS money, which MariBank structurally cannot.”
MariBank: the SDIC-insured savings account
MariBank’s Mari Savings Account pays a flat 0.88% p.a. on SGD balances with no minimum balance, no fall-below fee, and no conditions to unlock the rate — it applies to every dollar from day one. USD balances currently earn a promotional 1.88% p.a. until 31 December 2026, reverting to the 0.88% base rate after. Deposits are SDIC-insured up to S$100,000 per depositor, and all figures above are effective as at 18 October 2026 per MariBank’s own fees-and-rates page. New sign-ups can use the MariBank referral code 2DCT80WQ.
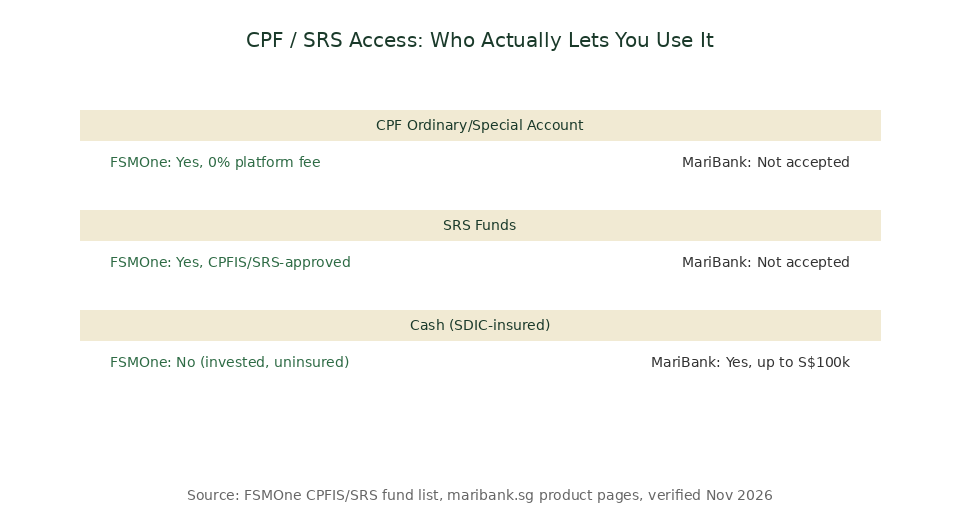
MariBank is cash-only. It does not accept CPF Ordinary Account, CPF Special Account, or SRS funds in any form — it’s a savings and spending account, not an investing one.
FSMOne: the CPFIS/SRS-approved investing platform
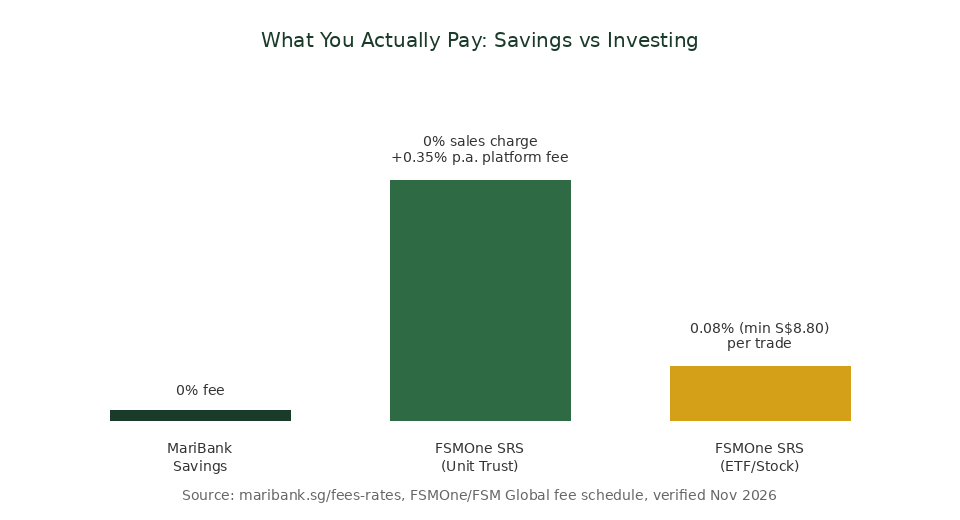
FSMOne charges a permanent 0% sales charge on its 1,500+ unit trusts — one of the first platforms in Singapore to do so. On top of that, cash and SRS holdings in equity and mixed unit trusts carry a platform fee of roughly 0.0875% per quarter (about 0.35% p.a.), while fixed income unit trusts are charged around 0.20% p.a. Unit trusts held inside a CPF account pay no platform fee at all. Direct SGX stock and ETF trades are charged separately at 0.08% of trade value with a S$8.80 minimum. New users can use the FSMOne referral code P0544985.
Unlike MariBank, FSMOne is CPFIS-approved and SRS-eligible, which is the entire reason it exists on a different shortlist from a pure savings account.
The CPF and SRS access gap
This is the differentiator that actually separates the two platforms, rather than a simple “who pays more” question. FSMOne lets you invest CPF Ordinary Account and CPF Special Account funds directly, and also accepts SRS contributions into unit trusts, bonds and other eligible instruments — with zero platform fee on the CPF-held portion. MariBank cannot touch CPF or SRS money at all; it only ever holds cash you’ve already taken out of those schemes (which, for CPF, generally isn’t possible except via CPFIS withdrawal routes, and for SRS would trigger tax and penalty consequences if withdrawn early).
Fee and rate comparison tables
| Feature | MariBank | FSMOne |
|---|---|---|
| Product type | Savings account | Investing platform |
| Headline rate / fee | 0.88% p.a. SGD (1.88% p.a. USD promo to 31 Dec 2026) | 0% sales charge UT + ~0.35% p.a. platform fee; 0.08% min S$8.80 on ETF/stocks |
| Minimum balance / fall-below fee | None | None |
| SDIC insured | Yes, up to S$100,000 | No (invested capital, not a deposit) |
| CPF OA/SA access | Not accepted | Yes, CPFIS-approved, 0% platform fee on CPF holdings |
| SRS access | Not accepted | Yes, SRS-eligible unit trusts, bonds and ETFs |
| Return type | Fixed interest rate | Market-linked, not guaranteed |
Source: maribank.sg/fees-rates/mari-savings-account (effective 18 Oct 2026) and FSMOne/FSM Global fee schedule, verified November 2026.
Which one fits your situation
If the money is an emergency fund or short-term cash you want fully insured and instantly accessible, MariBank’s flat 0.88% p.a. with no conditions does that job cleanly. If the goal is investing CPF or SRS money that would otherwise sit at the low CPF OA floor rate or earn nothing in an SRS account, FSMOne is the one that can actually touch those funds — and the 0% unit trust sales charge means the headline cost of doing so is lower than many investors expect. Many Singapore investors end up using both: MariBank for the cash buffer, FSMOne for the CPF/SRS-eligible portfolio sitting behind it.
Related reading: see the Endowus vs FSMOne comparison for how a managed robo-advisor stacks up against FSMOne’s self-directed model, or use the Singapore retirement calculator to see how CPF-eligible investing compounds over time.
FAQ
Is FSMOne or MariBank better for beginners?
Can I use MariBank for my CPF or SRS funds?
Does FSMOne charge a platform fee on CPF holdings?
Is my money safe in FSMOne the way it is in MariBank?
Can I use both FSMOne and MariBank at the same time?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.