Term Life Insurance for HDB Owners Singapore (2026 Guide)
HPS alone isn't enough. Here's how much coverage you really need.
HDB owners in Singapore are automatically covered by the Home Protection Scheme (HPS) for their outstanding mortgage — but HPS only pays the bank, not your family. A 35-year-old with a S$400,000 HDB loan and S$6,000 monthly income needs at least S$650,000 in standalone term life coverage on top of HPS to replace 9x annual income. Without it, your family loses your salary but keeps the mortgage paid. This 2026 guide explains why HPS is not enough, how much term life you need, and what it costs.
Not financial advice. All figures are for educational reference only. HPS data sourced from CPF Board, November 2026. Consult a licensed financial adviser before purchasing insurance.
Table of Contents
- What is HPS and What Does It Cover?
- The Income Protection Gap HPS Leaves Behind
- HPS vs Term Life Insurance: Full Comparison
- How Much Term Life Coverage Does an HDB Owner Need?
- Can Term Life Replace HPS? The HPS Exemption Explained
- Where to Get Term Life Insurance in Singapore
- Frequently Asked Questions
What is HPS and What Does It Cover?
The Home Protection Scheme (HPS) is a mortgage-reducing term insurance administered by the CPF Board. It is compulsory for most Singaporeans using CPF savings to service an HDB flat loan. When you die, become terminally ill, or suffer total permanent disability before the loan is fully repaid, HPS pays the outstanding mortgage balance directly to HDB.
Key facts about HPS (source: CPF Board, November 2026):
| Feature | Details |
|---|---|
| Coverage trigger | Death, terminal illness, total permanent disability |
| Payout recipient | HDB (not your family); clears outstanding mortgage |
| Coverage amount | Reduces annually as you repay the loan (mortgage-reducing) |
| Maximum coverage age | Age 65, or when loan is fully repaid — whichever comes first |
| Premium payment | Deducted automatically from CPF Ordinary Account (OA) annually |
| Critical illness | Not covered |
| Income replacement | Not covered — payout goes to HDB, not your family |
| Mandatory for | HDB flat buyers using CPF to service HDB concessionary or bank loans |
Source: CPF Board — Home Protection Scheme, November 2026. cpf.gov.sg
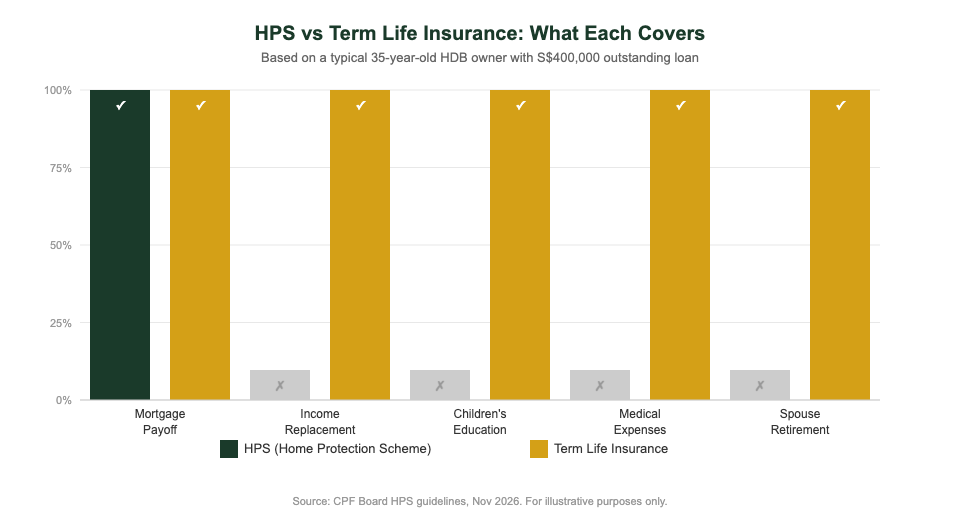
This is exactly what makes HPS so widely misunderstood: it protects the house, not the household. After an HPS claim, your family owns the flat mortgage-free — but they lose all of your income.
The Income Protection Gap HPS Leaves Behind
Consider a typical HDB owner: male, age 35, earning S$6,000 per month, with a spouse, two young children, and a S$400,000 outstanding HDB loan. If he passes away tomorrow:
- HPS pays: S$400,000 to HDB — mortgage cleared, family keeps the flat
- Family loses: S$72,000 per year in income — for potentially 25+ years
- Education costs: Two children’s university fees — estimated S$80,000–S$150,000 each by 2035
- Living expenses: S$3,000–S$5,000 per month minimum for a Singapore family of three
At S$6,000/month income, this family needs approximately S$650,000–S$1,000,000 in life insurance proceeds invested in low-risk instruments at 3–4% per annum to replace 15 years of income. HPS provides none of this. Without a term life plan, the family keeps the flat but faces immediate financial hardship. Many Singapore families discover this coverage gap only after a claim — when it is too late to do anything about it.
MAS MoneySense recommends Singaporeans carry life insurance of at least 9 times annual income. For S$72,000/year earners, that is S$648,000 — on top of HPS. For families with young children, 10x or higher is prudent. Use our retirement planning calculator to model your family’s specific income replacement needs.
HPS vs Term Life Insurance: Full Comparison
The key distinction is what gets paid and to whom. HPS protects the asset; term life protects your family’s financial future.
| Feature | HPS | Term Life Insurance |
|---|---|---|
| Purpose | Clears HDB mortgage | Replaces income, funds family’s needs |
| Payout goes to | HDB (reduces to zero by loan end) | Your family/nominated beneficiary |
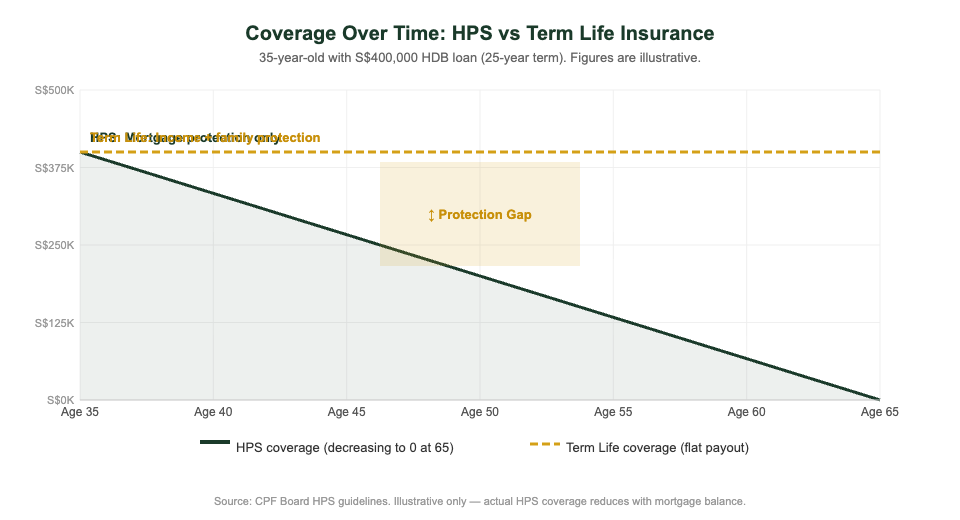
| Coverage amount | Decreasing (follows loan balance) | Level (stays S$500K–S$1M throughout) |
| Critical illness | No | Optional CI rider available |
| Total permanent disability | Yes (TPD) | Yes (included in most plans) |
| Premium payment | From CPF OA (no cash outlay) | Cash (monthly or annual) |
| Coverage after loan repaid | Coverage ends | Continues until policy expiry |
| Covers debts beyond HDB | No | Yes (family decides how to use payout) |
| Nomination | Mandatory (HDB is always recipient) | Flexible — nominate spouse, children, parents |
| Do I need both? | Yes, for complete protection. HPS handles the mortgage; term life handles everything else. | |
Source: CPF Board HPS guidelines + indicative market data, November 2026
How Much Term Life Coverage Does an HDB Owner Need?
A widely used guideline from financial planners and the MAS MoneySense framework is 9–10 times your annual income in life insurance coverage. For most Singaporean HDB owners, this translates to S$500,000–S$1,000,000 in standalone term life coverage, on top of HPS.
Here is a practical calculation for a 35-year-old HDB owner earning S$6,000 per month:
- Annual income: S$72,000
- Recommended coverage (9x): S$648,000 → round up to S$700,000
- HPS covers: S$400,000 (outstanding mortgage, declining to zero by age 65)
- Term life needed: at least S$500,000–S$700,000 (flat payout)
Note: HPS is not counted toward your income-replacement coverage, since it pays the mortgage directly. Your term life payout should be sufficient for your family to cover all expenses for 10–15 years without your income. As a cross-check, factor in young children’s university costs (S$80,000–S$150,000 each), and aging parents who depend on you.
Use our free Singapore retirement planning calculator to estimate your family’s exact income-replacement needs.
Indicative term life premiums for HDB owners (2026)
For a non-smoking male, age 35, 25-year level term policy:
| Sum Assured | Indicative Annual Premium | Monthly Cost |
|---|---|---|
| S$300,000 | S$280 – S$360 | S$23 – S$30 |
| S$500,000 | S$450 – S$560 | S$38 – S$47 |
| S$700,000 | S$620 – S$770 | S$52 – S$64 |
| S$1,000,000 | S$880 – S$1,100 | S$73 – S$92 |
Source: Indicative market range, Nov 2026. Non-smoker male, age 35, 25-year level term. Actual premiums vary by insurer, health, and riders. Obtain quotes from a licensed financial adviser.
Compared to HPS (deducted from CPF OA), term life premiums are paid in cash. For S$500K of coverage, the out-of-pocket cost is roughly S$38–S$47 per month — affordable protection for complete income security. For HDB owners also looking to grow wealth, platforms like Syfe (code: SRPRFFFCD) or Endowus (code: 2V343) can help optimise your CPF OA investments alongside your insurance planning.
Can Term Life Replace HPS? The HPS Exemption Explained
The CPF Board allows eligible HDB flat owners to apply for an HPS exemption if they already hold private insurance that provides equivalent coverage. According to the CPF Board’s official guidelines (November 2026), the following insurance types qualify: whole life insurance, term life insurance (level or decreasing term), endowment plans, and mortgage-reducing term assurance (MRTA) riders.
To qualify for an HPS exemption, your private insurance must: (1) cover the full outstanding HDB loan amount at all times; (2) remain in force until the loan is fully repaid or age 65, whichever comes first; and (3) cover death, terminal illness, and total permanent disability.
Important caveat: even if you obtain an HPS exemption using a term life plan, ensure the policy term and coverage amount continue to meet these conditions throughout the entire loan period. If your term life policy lapses or the coverage drops below your outstanding loan balance, CPF Board may reinstate compulsory HPS coverage.
For most HDB owners, the smarter approach is to keep HPS (premiums come from CPF OA at no cash cost) and layer a separate term life policy on top for income replacement. Read our in-depth guide on CPF investment strategy to understand how to optimise your CPF OA savings alongside housing and insurance decisions.
Where to Get Term Life Insurance in Singapore
Term life insurance in Singapore is sold by all major insurers including AIA, Prudential, Great Eastern, Manulife, and Singlife. You can buy through a licensed financial adviser (FA) for personalised advice across multiple insurers, or via online platforms for direct comparison:
- FSMOne referral code — offers a range of insurance and investment products for HDB owners
- Endowus referral code (code: 2V343) — CPF-eligible investments to build wealth alongside protection
- Syfe referral code and sign-up bonus (code: SRPRFFFCD) — passive investing platform for HDB owners growing wealth
When shopping for term life as an HDB owner, consider: a minimum coverage of 9x annual income; a policy term covering until your youngest child finishes university; a critical illness rider given Singapore’s high incidence of cancer, heart disease, and stroke; and whether the policy offers a conversion option to whole life later without medical underwriting.
Note: The Kopi Notes may earn a referral fee when you sign up via our links. This does not affect the recommendations above.
Frequently Asked Questions
Do HDB owners in Singapore need life insurance beyond HPS?
Can I use term life insurance instead of HPS?
How much term life insurance does an HDB owner need?
What are HPS premiums and how are they paid?
Does HPS cover critical illness?
When should an HDB owner buy term life insurance?
Is term life insurance premiums tax deductible in Singapore?
Summary: HDB Owner Life Insurance Checklist (2026)
As an HDB owner, here is your complete protection checklist:
- HPS — mandatory for most HDB owners with an HDB loan; covers the mortgage, premiums deducted from CPF OA
- Term Life Insurance — at least 9x annual income, separate from HPS; covers income replacement, dependants, education, and other debts
- Critical Illness rider or standalone CI — covers the living costs and income lost during major illness, which HPS does not
- MediShield Life / Integrated Shield Plan — for hospitalisation costs; consider a Rider for co-payments
The order of priority: get HPS sorted (usually automatic when you take an HDB loan), then immediately buy term life to cover income replacement, then add CI coverage. Your CPF OA handles HPS passively; your cash budget needs to cover term life and CI premiums.
For passive income planning to build financial resilience alongside your insurance stack, explore passive income strategies in Singapore, or use our retirement planning calculator to map out your financial timeline.
Not financial advice. Data as at November 2026. Consult a licensed financial adviser before purchasing insurance products.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.