INVESTMENT INSURANCE GUIDE
Endowment Plan Regular Premium vs Single Premium Singapore 2026: Which Should You Choose?
A Complete Singapore 2026 Comparison — Rates, Returns, and When to Use Each
📋 Table of Contents
A regular premium endowment plan spreads your insurance premiums over monthly or annual payments across a 10–25 year policy term, while a single premium endowment plan accepts one lump sum upfront for a shorter 1–5 year commitment. For Singaporeans with spare capital, single premium endowments currently offer guaranteed yields of 1.60–2.00% p.a. (Q3 2026). For those building long-term wealth and savings discipline, regular premium plans offer projected total returns of 3.0–4.5% p.a. over longer horizons. Both are insurance-savings hybrids — understanding the structure helps you pick the right one for your goals.
Not financial advice. All figures are for educational reference only. Data verified as at 27 October 2026 unless noted.
What is a Regular Premium Endowment Plan?
A regular premium endowment plan is a life insurance savings product where you pay a fixed premium — monthly, quarterly, half-yearly, or annually — over a defined policy term of typically 10 to 25 years. At maturity, you receive a guaranteed sum plus any non-guaranteed bonuses if the plan is a participating (par) policy.
Key characteristics of regular premium endowment plans:
- Premium structure: Smaller recurring payments spread over many years (from ~S$100–S$300/month)
- Policy term: Typically 10–25 years; some plans offer 5-year terms
- Coverage: Provides meaningful life insurance coverage (sum assured) throughout the premium-paying period
- Premium waiver: Most plans include a premium waiver benefit — if you become permanently disabled or pass away, future premiums are waived and the policy continues
- Cash value: Builds slowly in early years; may be lower than total premiums paid in the first 3–5 years due to insurance charges
- Projected returns: 3.0–4.5% p.a. total (including non-guaranteed bonuses) over a 15–25 year horizon
Regular premium endowment plans suit young professionals who want to build a disciplined savings habit alongside life insurance coverage. They are also commonly used for education planning — parents start a plan when a child is young and time the maturity to coincide with university entry.
What is a Single Premium Endowment Plan?
A single premium endowment plan requires one upfront lump-sum payment. In return, you receive a guaranteed maturity payout at the end of a shorter term — typically 1 to 5 years — plus basic life insurance coverage throughout.
Key characteristics of single premium endowment plans:
- Premium structure: One lump sum payment upfront
- Policy term: Short — typically 1, 2, 3, or 5 years
- Minimum premium: Usually S$5,000–S$20,000 depending on the product
- Returns: Guaranteed yield of 1.60–2.00% p.a. for most mainstream Q3 2026 plans, with potential non-guaranteed bonuses on participating products
- SRS eligible: Most single premium endowment plans qualify for Supplementary Retirement Scheme (SRS) funding
- Coverage: Typically 101–105% of single premium paid as death benefit
Single premium endowment plans function similarly to fixed deposits but are technically insurance products, making them eligible for SRS deployment. This is particularly attractive for Singaporeans who want income tax relief on SRS contributions while preserving capital with modest yields.
Key Differences: Regular vs Single Premium Endowment Plans
The choice between regular and single premium endowment plans ultimately comes down to three factors: how much capital you have available now, how long you can commit, and what return profile you are targeting. The chart below compares the two structures across the key decision dimensions.
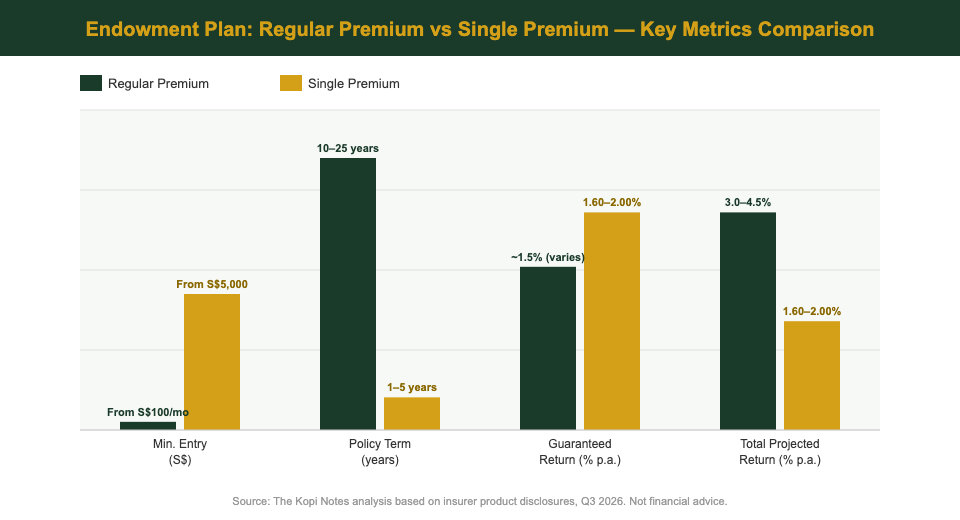
Source: The Kopi Notes analysis based on insurer product disclosures, Q3 2026. Not financial advice.
Side-by-Side Comparison Table
| Feature | Regular Premium | Single Premium |
|---|---|---|
| Premium Payment | Monthly/Annual instalments | One lump sum upfront |
| Minimum Entry | From S$100–S$300/month | From S$5,000–S$20,000 |
| Typical Policy Term | 10–25 years | 1–5 years |
| Guaranteed Returns | Varies (lower in early years) | 1.60–2.00% p.a. |
| Total Projected Returns | 3.0–4.5% p.a. (incl. non-guaranteed) | 1.60–2.00% p.a. (mostly guaranteed) |
| Life Coverage | Full sum assured throughout | 101–105% of premium |
| Premium Waiver | ✅ Usually included | ❌ Not applicable |
| SRS Eligible | ❌ Typically No | ✅ Most plans Yes |
| Early Surrender Penalty | Significant (especially years 1–5) | Minimal (short tenor) |
| Best For | Long-term savings discipline & coverage | Capital deployment + SRS |
Source: The Kopi Notes analysis based on major Singapore insurer disclosures (AIA, Prudential, Great Eastern, NTUC Income, Singlife, Manulife), Q3 2026.
Current Endowment Plan Rates Singapore 2026
As of Q3 2026, here are the verified rates for key single premium endowment plans available in Singapore, alongside alternatives:
| Product | Provider | Tenor | Yield (Guaranteed) | Min. Premium |
|---|---|---|---|---|
| Singlife Max Saver II | Singlife | 2 years | 2.00% p.a. | S$20,000 |
| DBS SavvyEndowment 22 | DBS Bank | 2 years | Up to 1.88% p.a. | S$5,000 |
| Manulife Goal 2026 (I) | Manulife / POSB | 2 years | Up to 1.60% p.a.* | S$5,000 |
| 6-Month T-Bill (Oct 2026) | MAS / SGS | 6 months | ~1.95% p.a. | S$1,000 |
| Singapore Savings Bond | MAS / SGS | Up to 10 years | ~2.70% p.a. (long-term avg) | S$500 |
| Fixed Deposit | Local banks | 12 months | ~1.80% p.a. | S$1,000+ |
| Regular Premium Plans (Projected) | AIA, GE, NTUC, Prudential | 10–25 years | 3.0–4.5% p.a. total** | From S$100/month |
*Manulife Goal 1.60% p.a. includes non-guaranteed bonus component. **Regular premium projected returns include non-guaranteed bonuses and are not guaranteed. Source: Insurer disclosures, MAS, MoneySmart, DBS/POSB sites. Data as at October 2026.
Key insight: Regular premium endowment plans — despite requiring a 10–25 year commitment — project 3.0–4.5% p.a. total returns that comfortably exceed the 1.95% T-bill, 2.70% SSB, and 1.80% FD rates. The trade-off is liquidity and commitment length. For short-term parking of capital, single premium plans at 1.60–2.00% compete with T-bills and beat FD rates.
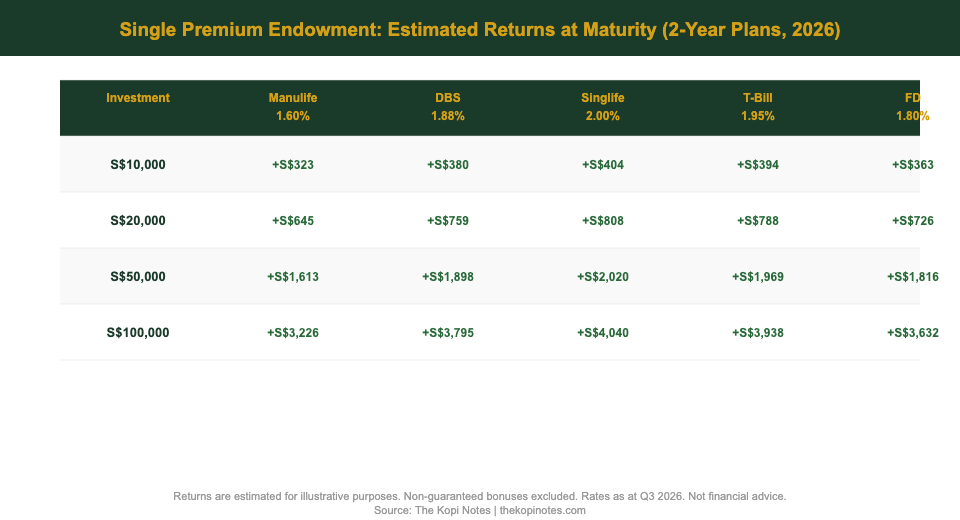
Source: The Kopi Notes. Estimated 2-year returns for illustrative purposes only. Rates as at Q3 2026. Not financial advice.
When to Choose a Regular Premium Endowment Plan
Choose a regular premium endowment plan when:
- You want to build a savings discipline — Monthly premiums enforce consistent saving, similar to an automatic unit trust top-up
- You need life insurance coverage alongside savings — Regular premium plans provide a meaningful sum assured (e.g. S$100,000+) with premium waiver on death or permanent disability
- You’re planning for a specific future milestone — University funding in 18 years, retirement in 25 years, or building a legacy for children
- You have a long investment horizon — The projected 3.0–4.5% p.a. total return over 15+ years beats T-bills, fixed deposits, and CPF Ordinary Account (2.50% p.a.) when achieved
- You’re a young working adult — Starting at age 25–30 maximises the compounding period and typically secures lower insurance premiums
Important caveat: Regular premium endowment plans carry significant early surrender penalties in years 1–5. Ensure you maintain a separate emergency fund (3–6 months of expenses) before committing to any long-term endowment. Use our Singapore retirement calculator to model your savings target before signing up.
When to Choose a Single Premium Endowment Plan
Choose a single premium endowment plan when:
- You have a lump sum to deploy — Bonuses, inheritance, property proceeds, or cash sitting in a low-yield account
- You want to deploy SRS funds strategically — Most single premium plans are SRS-eligible, giving you income tax relief on contributions up to S$15,300/year (Singapore Citizens) while earning guaranteed yields
- You want capital preservation with modest yield — Single premium plans at 1.60–2.00% p.a. guaranteed match or beat most fixed deposits (c. 1.80% p.a.) with similar lock-up
- You prefer short commitments — 1–3 year terms are highly predictable and suitable for pre-retirement capital preservation
- You’re approaching or in retirement — A retiree with S$200,000 in savings may prefer 2-year single premium laddering over committing to a 20-year regular premium plan
Singaporeans also using Singapore Savings Bonds should compare SSB’s ~2.70% p.a. (over 10 years) against single premium endowment yields. For 1–2 year capital, single premium endowments and Singapore T-bills compete closely. SSB wins for longer-term parking thanks to higher blended yields and full flexibility to redeem after any month.
Pros and Cons: Regular Premium vs Single Premium Summary
| Aspect | Regular Premium | Single Premium |
|---|---|---|
| Accessible for small savers | ✅ From S$100/month | ❌ Need S$5,000+ lump sum |
| Meaningful life coverage | ✅ Full sum assured | ⚠️ Minimal (101–105% premium) |
| Short-term commitment | ❌ 10–25 years | ✅ 1–5 years |
| Higher potential returns | ✅ 3.0–4.5% p.a. projected | ❌ 1.60–2.00% p.a. guaranteed |
| SRS fund compatibility | ❌ Usually not eligible | ✅ Most plans eligible |
| Return transparency | ⚠️ Non-guaranteed portion opaque | ✅ Clear guaranteed yield |
| Low early exit penalty | ❌ Heavy surrender charges (yrs 1–5) | ✅ Short tenor minimises risk |
| Savings discipline built-in | ✅ Enforced by premium schedule | ❌ One-time decision only |
Source: The Kopi Notes. Based on typical Singapore endowment plan structures as at Q3 2026.
If you’re evaluating robo-advisor alternatives for medium-term savings alongside endowment plans, check our guides on Endowus referral code (for CPF/SRS/cash portfolios) and Syfe referral code and sign-up bonus. For FSMOne’s unit trust and bond fund options, see the FSMOne referral code guide. These platforms offer liquidity that endowment plans lack, at the cost of market risk.
Frequently Asked Questions
What is the main difference between regular premium and single premium endowment plans?
Which endowment plan gives higher returns — regular or single premium?
Can I use SRS funds to buy an endowment plan in Singapore?
What happens if I surrender my endowment plan early?
Is a single premium endowment plan better than a fixed deposit in Singapore 2026?
How much do I need to start an endowment plan in Singapore?
Which type of endowment plan is better for retirement planning?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.