GXS Boost Pocket vs UOB Fixed Deposit (October 2026): Which Rate Wins?
Updated 24 October 2026 | Digital Banks | By The Kopi Notes
GXS Boost Pocket’s 18-month tenor now offers 2.00% p.a. — outpacing UOB’s best fixed deposit rate of 1.70% p.a. for a 12-month term in October 2026. With a minimum of just S$100 (versus UOB’s S$10,000), GXS is more accessible for most savers. However, UOB’s 1.70% 12-month rate is promotional, expiring 31 October 2026, and requires no lock-in beyond the chosen tenure. Here is how both products compare this month.
Not financial advice. All figures are for educational reference only. Data as at 24 October 2026 unless noted.
Table of Contents
- What Is GXS Boost Pocket?
- GXS Boost Pocket Rates — October 2026
- UOB Fixed Deposit Rates — October 2026
- GXS Boost Pocket vs UOB FD: Head-to-Head
- Minimum Deposit and Flexibility
- GXS October 2026 Promotions
- MariBank and Trust Bank: How Do They Compare?
- Which Should You Choose?
- Frequently Asked Questions
What Is GXS Boost Pocket?
GXS Bank is one of Singapore’s two fully licensed digital banks, launched in 2022 under a consortium involving Grab and Singtel. Unlike traditional banks, GXS operates without physical branches and offers products entirely through its mobile app.
The GXS Boost Pocket is a time-deposit product within the GXS savings ecosystem. It works similarly to a fixed deposit — you choose a tenure (1 to 18 months), lock in your funds at a fixed interest rate, and receive the bonus rate only if you hold to maturity. Unlike a standard GXS Saving Pocket (which earns 1.20% p.a. with no lock-in), the Boost Pocket rewards commitment with meaningfully higher rates.
Key features of the GXS Boost Pocket:
- Minimum deposit: S$100 (no large lump sum required)
- Maximum combined Boost Pocket balance: S$95,000
- Tenure options: 1, 3, 4, 8, 12, and 18 months
- Early withdrawal permitted, but bonus rate is forfeited (base rate applies instead)
- Deposits protected under SDIC up to S$100,000
The GXS app makes it easy to open multiple Boost Pockets simultaneously, letting you ladder different tenures for flexibility — similar to a Singapore fixed deposit laddering strategy.
GXS Boost Pocket Rates — October 2026
Here are the current GXS Boost Pocket rates as of 24 October 2026:
| Tenure | Interest Rate (p.a.) | Interest on S$10,000 |
|---|---|---|
| 1 month | 1.01% | S$8.42 |
| 3 months | 1.22% | S$30.42 |
| 4 months | 1.40% | S$46.58 |
| 8 months | 1.70% | S$113.15 |
| 12 months | 1.75% | S$175.00 |
| 18 months | 2.00% | S$300.00 |
Source: GXS Bank (via growbeansprout.com), October 16, 2026. Interest calculated on S$10,000 for illustrative purposes. Must hold to maturity for bonus rate.
The 18-month Boost Pocket at 2.00% p.a. is the standout offer — it significantly outpaces most competing products, though you need to commit for 18 months without early withdrawal to receive the full benefit.
UOB Fixed Deposit Rates — October 2026
UOB has been running a fixed deposit promotional campaign through October 2026, offering competitive rates for S$10,000 and above. These promotional rates expire on 31 October 2026.
| Tenure | Promotional Rate (p.a.) | Minimum Deposit | Interest on S$10,000 |
|---|---|---|---|
| 6 months | 1.60% | S$10,000 | S$80.00 |
| 10 months | 1.65% | S$10,000 | S$137.50 |
| 12 months | 1.70% | S$10,000 | S$170.00 |
Source: UOB Singapore (via growbeansprout.com), October 21, 2026. Promotional rates expire 31 October 2026. Interest calculated on minimum S$10,000 deposit.
The UOB promotional 12-month rate of 1.70% p.a. is attractive for savers with S$10,000 or more who prefer a familiar bank with branch access. However, these rates are not permanent — once the promotion ends, renewal rates will likely be lower.
For a broader comparison of Singapore fixed deposit rates across all banks this month, including OCBC, DBS, and ICBC, The Kopi Notes maintains a regularly updated rate tracker.
GXS Boost Pocket vs UOB Fixed Deposit: Head-to-Head
When comparing GXS Boost Pocket and UOB Fixed Deposit head-to-head, the choice depends heavily on your deposit size, tenure preference, and how much flexibility you need.
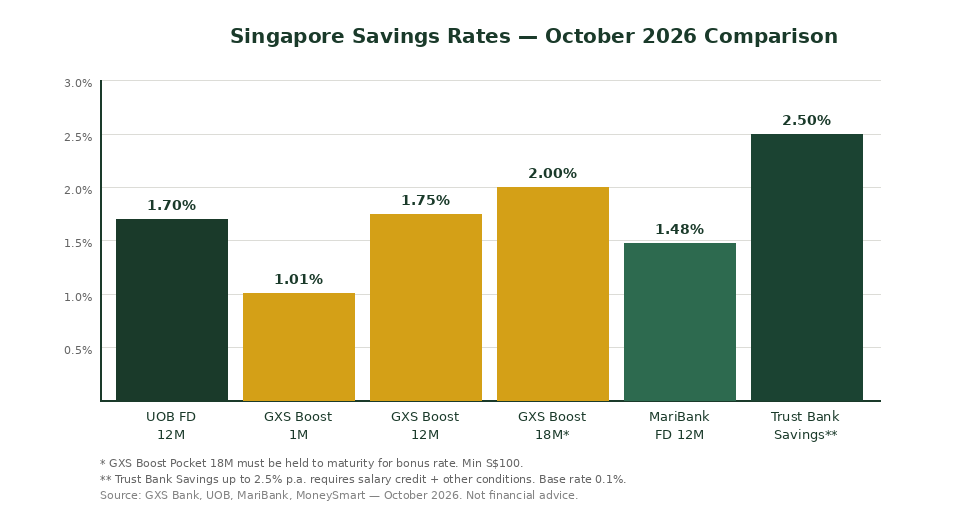
Chart: Singapore savings rates comparison — GXS Boost Pocket vs UOB FD vs MariBank vs Trust Bank, October 2026. Source: Official bank sites, growbeansprout.com, MoneySmart.sg.
The headline comparison for the most comparable timeframe — 12 months:
- GXS Boost Pocket 12M: 1.75% p.a. (minimum S$100)
- UOB Fixed Deposit 12M: 1.70% p.a. (minimum S$10,000, promotional until 31 Oct)
GXS edges out UOB by 0.05 percentage points at the 12-month mark — a small but meaningful difference when compounded, especially if you are starting from a smaller capital base. On a S$10,000 deposit held for 12 months, GXS Boost Pocket earns S$175 versus UOB’s S$170 — a S$5 difference that favours GXS.
At 18 months, the gap widens significantly. GXS Boost Pocket offers 2.00% p.a. compared to UOB’s best promotional rate of 1.70%. On S$10,000 over 18 months, that difference translates to approximately S$45 more interest in GXS’s favour (S$300 vs S$255).
However, if you have S$50,000 to deploy and prefer the security of a MAS-regulated incumbent bank, UOB’s 1.70% on the full amount at S$50,000 yields S$850 — comparable to GXS at 12 months (S$875), with the added comfort of branch access and an established brand.
Minimum Deposit and Flexibility
One of the most underappreciated differences between GXS Boost Pocket and traditional fixed deposits is the minimum deposit threshold. This has real implications for younger savers and those building an emergency fund gradually.
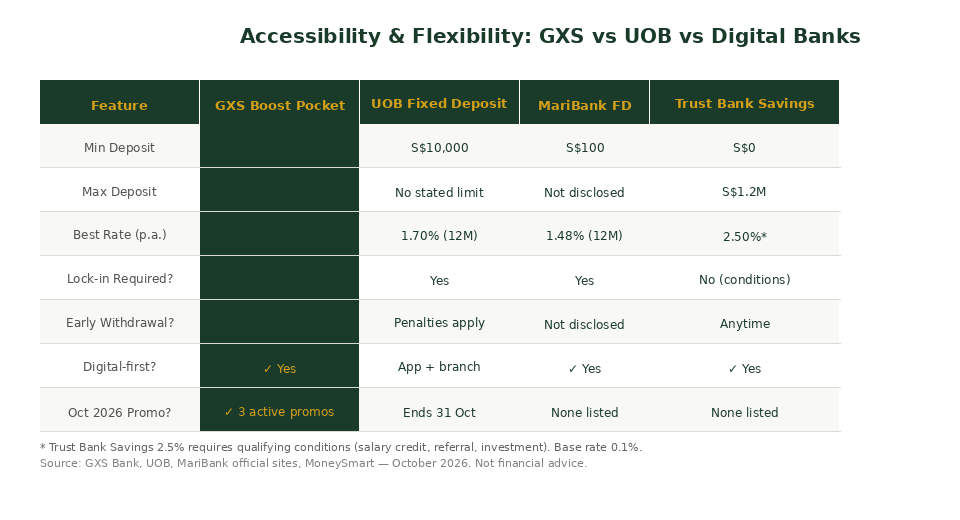
Chart: Minimum deposit and product accessibility — GXS vs UOB vs MariBank vs Trust Bank, October 2026. Source: Official bank sites, MoneySmart.sg.
Key takeaways on minimum deposit and flexibility:
- GXS Boost Pocket: S$100 minimum, up to S$95,000 total across all Boost Pockets. You can open multiple pockets with different tenures simultaneously — useful for deposit laddering.
- UOB Fixed Deposit: S$10,000 minimum. This locks out those who are building savings gradually or prefer to keep emergency funds liquid.
- MariBank Fixed Deposit: S$100 minimum, competitive rates (up to 1.48% p.a. for 12 months).
- Trust Bank Savings: No minimum deposit, but the headline 2.5% p.a. rate requires salary credit and other qualifying conditions (base rate is just 0.1%).
For someone with S$5,000 to S$9,999, the traditional bank FD route is effectively unavailable — GXS and MariBank fill this gap significantly. Use the TKN ROI calculator to model what different rates mean for your specific deposit amount over your chosen tenure.
If you prefer not to lock funds at all, consider Singapore T-bills (6-month tenure) — the latest October 22, 2026 auction cleared at 1.95%, which currently beats all the fixed deposit rates mentioned in this article for the equivalent 6-month timeframe, with full capital return and no lock-in risk.
GXS October 2026 Promotions
GXS is running three active promotions in October 2026. If you are considering opening a GXS account, timing your sign-up before month-end maximises your benefits.
1. Payday Boost (19–31 October 2026)
During this window, GXS offers a short-term bonus rate for salary credits received into your GXS account. This promotion is targeted at salaried employees who can credit their October salary into GXS. Check the GXS app for the exact bonus rate — it typically stacks on top of existing Saving Pocket or Boost Pocket rates for a defined period.
2. Save & Invest Campaign (1–30 October 2026)
GXS rewards customers who maintain a qualifying balance across their savings products (GXS Saving Pockets and Boost Pockets combined). This is worth noting for those who are already using GXS and plan to move additional funds this month before the campaign ends on 30 October.
3. First Boost (New Customers, until 31 October 2026)
New GXS customers who open their first Boost Pocket before 31 October 2026 may receive an additional bonus rate for their first tenure. This makes October a particularly good month to open a new GXS account if you have been on the fence. Use the GXS referral code YONG477 when signing up — TKN readers typically receive a bonus reward on their first Boost Pocket via referral.
Important: All promotional rates expire at month-end. Even without the promotions, the standard GXS Boost Pocket rates (up to 2.00% p.a.) remain competitive — but act before 31 October to benefit from the stacked promotions.
MariBank and Trust Bank: How Do They Compare?
Beyond GXS and UOB, two other digital bank options deserve mention for Singapore savers: MariBank and Trust Bank.
MariBank Fixed Deposit
MariBank — backed by Sea Limited (parent of Shopee) — offers fixed deposits starting from S$100, making it similarly accessible to GXS. Current rates as of October 2026:
- 1 month: 1.08% p.a.
- 3 months: 1.28% p.a.
- 6 months: 1.38% p.a.
- 12 months: 1.48% p.a.
At 12 months, MariBank’s 1.48% p.a. trails GXS Boost Pocket’s 1.75% p.a. and UOB’s promotional 1.70% p.a. It is, however, a solid alternative if you are already banking with MariBank or want to diversify across multiple digital banks for SDIC coverage. Use the MariBank referral code 2DCT80WQ when signing up.
Trust Bank Savings Account
Trust Bank — a joint venture between Standard Chartered and FairPrice Group — takes a different approach. Its headline savings rate is up to 2.5% p.a., but this requires multiple qualifying conditions including salary credit and potentially a linked FairPrice membership. The base rate without conditions is just 0.1% p.a.
For customers who already credit their salary to Trust Bank and shop regularly at FairPrice, the 2.5% p.a. is an excellent return with zero lock-in and no minimum deposit. For everyone else, the effective rate is closer to 0.5%–1.2% depending on which conditions are met. Use the Trust Bank referral code HTWYQP95 for a sign-up bonus.
Unlike GXS Boost Pocket and fixed deposits, Trust Bank savings is a high-yield savings account — your money stays liquid at all times, making it a better comparison against CIMB FastSaver or POSB Multiplier rather than traditional FDs.
Which Should You Choose?
The right choice depends on three factors: your deposit size, your preferred tenure, and how much flexibility you need.
| Your Situation | Best Option | Why |
|---|---|---|
| Less than S$10,000 to save | GXS Boost Pocket | Only option above 1% p.a.; S$100 minimum |
| Can commit S$10,000+ for exactly 12 months | UOB FD (until 31 Oct) or GXS 12M | Rates are similar; UOB is a familiar name with branch access |
| Want the best absolute rate, can lock for 18M | GXS Boost Pocket 18M | 2.00% p.a. — best available in this comparison |
| Want full liquidity, no lock-in | T-bills (6M, 1.95%) or Trust Bank Savings | Best rates without locking up funds |
| Already shop at FairPrice, credit salary | Trust Bank Savings | Up to 2.5% p.a. with no lock-in for qualifying customers |
| Want to diversify across multiple banks (SDIC) | GXS + MariBank + UOB combination | Spread across institutions; each deposit insured up to S$100k |
Source: The Kopi Notes analysis based on official bank rates, October 2026. Not financial advice.
For most salaried Singaporeans saving S$1,000–S$30,000, the GXS Boost Pocket 12-month or 18-month tenors currently offer the best rates among lock-in products with a low minimum deposit. If you are investing larger sums (S$50,000+) and want the peace of mind of a traditional bank, UOB’s promotional 12-month rate at 1.70% p.a. is worth considering before it expires on 31 October 2026.
For long-term wealth building beyond savings accounts and fixed deposits, Endowus offers evidence-based investment portfolios in CPF, SRS, and cash — a complement to short-term savings strategies.
Frequently Asked Questions
Is GXS Boost Pocket better than UOB Fixed Deposit?
For most deposit sizes below S$10,000, GXS Boost Pocket is the clear winner — UOB requires a S$10,000 minimum and GXS starts at S$100. For deposits of S$10,000 or more at the 12-month tenure, GXS Boost Pocket (1.75% p.a.) slightly edges out UOB’s promotional rate (1.70% p.a., valid until 31 October 2026). At 18 months, GXS’s 2.00% p.a. is significantly better than anything UOB currently offers. However, UOB is a traditional bank with branch access and decades of trust — a relevant consideration for some savers.
What happens if I withdraw from GXS Boost Pocket early?
If you withdraw from a GXS Boost Pocket before maturity, you forfeit the bonus interest rate and receive only the base rate instead. The base rate is typically much lower than the Boost Pocket rate (closer to the standard Saving Pocket rate). Your principal is not at risk — you get your full deposit back, just without the promised bonus interest. This is similar to how traditional fixed deposit early withdrawal penalties work at most Singapore banks.
Is GXS Bank safe? Are my deposits protected?
Yes. GXS Bank holds a full digital bank licence from the Monetary Authority of Singapore (MAS), the same regulatory body that oversees DBS, OCBC, and UOB. Deposits at GXS are protected under the Singapore Deposit Insurance Corporation (SDIC) scheme up to S$100,000 per depositor. This is the same level of protection offered at traditional banks. GXS is owned by a consortium including Grab and Singtel, both publicly listed companies.
Can I open multiple GXS Boost Pockets simultaneously?
Yes. You can open multiple GXS Boost Pockets with different tenures at the same time — a strategy known as deposit laddering. For example, you could open a 4-month Boost Pocket (1.40% p.a.), an 8-month Boost Pocket (1.70% p.a.), and a 12-month Boost Pocket (1.75% p.a.) simultaneously to balance liquidity and returns. The total combined balance across all your Boost Pockets cannot exceed S$95,000.
How does the GXS Boost Pocket compare to Singapore T-bills?
Singapore 6-month T-bills currently yield 1.95% p.a. (October 22, 2026 auction result), which is higher than the GXS Boost Pocket 8-month rate (1.70%) but lower than the 12-month (1.75%) and 18-month (2.00%) Boost Pocket rates. T-bills have no minimum deposit (you can bid for as little as S$1,000), are backed directly by the Singapore Government, and have no lock-in penalty — you can sell them in the secondary market. However, T-bills are not available in the GXS app and require a CDP or bank brokerage account to participate. See our guide on how to buy Singapore T-bills for a step-by-step walkthrough.
Does UOB Fixed Deposit renew automatically?
Yes, UOB Fixed Deposits typically renew automatically at maturity at the prevailing (non-promotional) rate, which may be significantly lower than the promotional rate you signed up for. This is a common pitfall with traditional bank fixed deposits. If you are placing money with UOB at the current 1.70% p.a. promotional rate, set a calendar reminder for your maturity date and review rates before allowing an auto-renewal — or consider whether GXS Boost Pocket’s rates at that point offer a better deal.
What are the GXS October 2026 promotions?
GXS is running three promotions in October 2026: (1) Payday Boost (19–31 October) — a bonus rate for salary credits received into GXS during this window; (2) Save & Invest Campaign (1–30 October) — rewards for maintaining qualifying balances across GXS savings products; and (3) First Boost (until 31 October) — a bonus for new customers opening their first Boost Pocket. All three expire at month-end, so now is an advantageous time to open a GXS account.
Disclaimer: The information in this article is for educational purposes only and does not constitute financial advice. All rates are subject to change without notice. Please verify current rates directly with the respective financial institutions before making any financial decisions. The Kopi Notes may receive referral compensation when you use referral codes on this page, at no additional cost to you.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.