CPF Retirement Account (RA) Singapore 2026: What Happens to Your CPF at 55
Your CPF Ordinary Account (OA), Special Account (SA) and MediSave Account (MA) are with you from your first payslip. The Retirement Account (RA) is different — it arrives automatically on your 55th birthday, and it changes everything.
The RA is created by merging your SA savings (and OA if needed) up to the Full Retirement Sum ($220,400 in 2026). Since January 2025, the SA is then permanently closed. From that moment, your RA earns 4% p.a. and becomes the single account that funds your CPF LIFE payouts from age 65.
- RA is created on your 55th birthday by merging SA (and OA if needed) funds up to the FRS
- The SA is permanently closed after the transfer — a change that took effect in January 2025
- RA earns 4% p.a. (floor rate), plus extra government interest of up to 2% p.a. on first $30,000
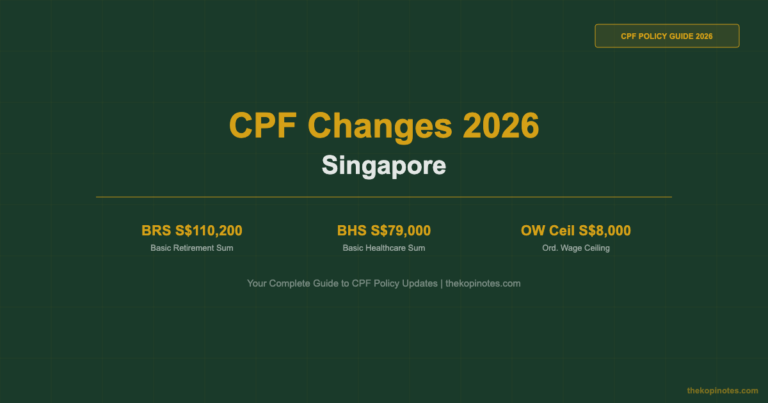
- FRS 2026: $220,400 | BRS: $110,200 | ERS cap: $440,800
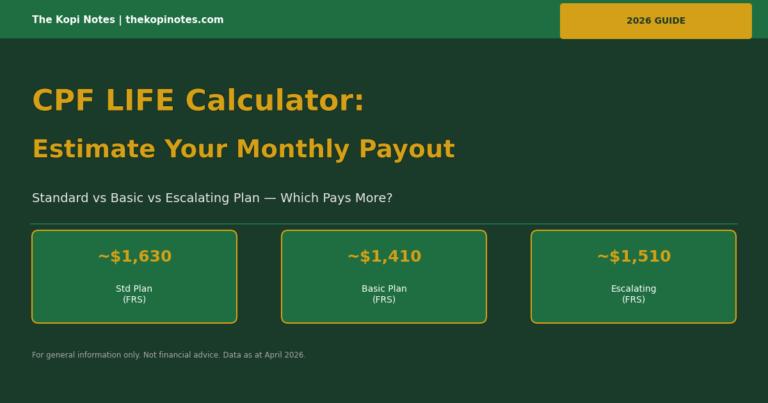
- At 65, your RA funds CPF LIFE — FRS gives ~$1,780/month; ERS gives ~$3,440/month
- You can top up your RA with cash for higher payouts and up to $8,000/year tax relief
What Is the CPF Retirement Account?
The RA is one of four CPF accounts. While the OA, SA and MediSave exist from when you start working, the RA appears only at 55. It serves as your dedicated retirement pool — the account from which CPF LIFE eventually draws your lifetime monthly income.
Before the RA arrives, your SA plays a similar role: it earns 4% p.a. and is ring-fenced for retirement. From 2025 onwards, that function transfers entirely to the RA. The SA does not continue alongside the RA — it is replaced by it.
What Happens at 55: The SA Closure
On your 55th birthday, CPF Board runs the following sequence automatically:
- Your SA savings move into the RA, up to the Full Retirement Sum (FRS)
- If your SA is below the FRS, your OA savings fill the remaining gap
- Any SA savings above the FRS move to your OA (not locked up)
- The SA is permanently closed
This SA closure has been in effect since January 2025. The key practical impact: the “SA shielding” strategy — where members invested SA savings in low-risk instruments just before 55 to prevent those savings from being locked in the RA — is no longer viable post-55.
Contributions after 55 (while you continue working) go into your OA, MediSave, and RA. Once the FRS is met in the RA, contributions flow only to the OA.
2026 Retirement Sums: BRS, FRS and ERS
Your RA balance at 65 determines which CPF LIFE plan you can join and how much you receive monthly. The three thresholds for 2026:
| Retirement Sum | 2026 Amount | CPF LIFE Standard Payout (from 65) |
|---|---|---|
| Basic Retirement Sum (BRS) | $110,200 | ~$950/month |
| Full Retirement Sum (FRS) | $220,400 | ~$1,780/month |
| Enhanced Retirement Sum (ERS) | $440,800 | ~$3,440/month |
Source: CPF Board. Payouts are estimates for members joining CPF LIFE at 65 in 2026. Actual payouts depend on plan type, gender, and age at scheme start. As at October 2026.
The BRS is the minimum needed to set aside to join CPF LIFE. Property owners can choose to set aside only the BRS if they pledge their property — you can then withdraw savings above the BRS from your OA.
How the RA Earns Interest
The RA earns the same floor rate as the SA used to: 4% per annum. This is guaranteed by the Singapore Government regardless of market conditions.
Members aged 55 and above also earn additional government-paid interest on their combined CPF balances:
| CPF Balance Tier | Extra Interest (55+) | Effective RA Rate |
|---|---|---|
| First $30,000 (combined CPF) | +2% p.a. | Up to 6% p.a. |
| Next $30,000 (combined CPF) | +1% p.a. | Up to 5% p.a. |
| Balance above $60,000 | — | 4% p.a. |
OA savings contributing to the extra interest calculation are capped at $20,000. Extra interest earned on OA savings goes into the RA (not the OA). Rates valid Q3–Q4 2026. Source: CPF Board.
The extra interest on the first $30,000 means that even a modest RA balance earns more than you might expect. A $30,000 RA balance effectively earns $1,800/year (6%) compared to $1,200/year (4%) without the extra tier.
Worked Example: Pei Ling Turns 55 in 2026
Pei Ling is a 55-year-old Singaporean with the following CPF balances at her birthday:
| Account | Balance at 55 |
|---|---|
| Special Account (SA) | $150,000 |
| Ordinary Account (OA) | $100,000 |
| MediSave Account (MA) | $63,000 |
Step 1 — SA funds transfer to RA: All $150,000 from SA moves into the RA. This covers 68% of the FRS ($220,400).
Step 2 — OA fills the gap: $220,400 − $150,000 = $70,400 is transferred from OA to RA.
Step 3 — SA is closed.
Result at 55:
- RA: $220,400 (FRS)
- OA: $100,000 − $70,400 = $29,600 (can withdraw)
- MediSave: $63,000 (unchanged, earns 4% p.a.)
- SA: Closed
At age 65 (10 years later): If Pei Ling makes no further top-ups or withdrawals, her RA grows from $220,400 to approximately $326,000 at 4% p.a. She joins CPF LIFE and receives approximately $1,780/month for life.
If she tops up to ERS: Topping up RA from $220,400 to $440,800 (adding approximately $22,040/year) could lift her CPF LIFE payout to approximately $3,440/month — nearly doubling her guaranteed income floor. See the CPF RA Top-Up Calculator to model your own numbers.
Topping Up Your CPF RA: How to Grow Your Retirement Payout
From age 55, you can voluntarily top up your RA with cash up to the current year’s Enhanced Retirement Sum ($440,800 in 2026). The ERS rises every January, so you can always top up further the following year.
There are two ways to top up your CPF post-55:
1. Cash Top-Ups (Retirement Sum Topping-Up Scheme)
- Tax relief of up to $8,000/year for top-ups to your own RA
- Additional tax relief of up to $8,000/year for top-ups to loved ones (parents, in-laws, grandparents, spouse, siblings)
- Maximum combined relief: $16,000/year
- Eligible for Matched Retirement Savings Scheme (MRSS): government matches up to $2,000/year, lifetime cap $20,000 — but MRSS top-ups do not qualify for tax relief
2. CPF Transfers (OA to RA)
- Transfer your OA savings into the RA — useful if you have surplus OA funds
- No tax relief on transfers (only on cash top-ups)
- Can also set up a recurring monthly transfer of OA employment contributions to RA
Important: All RA top-ups are irreversible. Once in the RA, the funds cannot be withdrawn for other purposes — they are committed to retirement. Top up in January rather than December to earn more interest over the year.
What You Can Withdraw at 55
The RA creation at 55 also triggers your first CPF withdrawal opportunity. Here is what you can take out:
- OA savings above the FRS gap: Any OA balance left after filling the RA up to the FRS can be withdrawn in full
- If you own property and meet the BRS: You can pledge your property and withdraw savings above the BRS from your RA — effectively unlocking up to $110,200 from the RA. A refund to CPF is required if the property is later sold
- $5,000 OA buffer: Up to $5,000 stays in your OA as withdrawable savings regardless of the RA requirement
Online withdrawals: the Daily Withdrawal Limit (DWL) defaults to $2,000 and can be adjusted up to $50,000. Larger withdrawals require a visit to a CPF Service Centre.
How the RA Links to CPF LIFE
At 65, your RA balance is used to fund CPF LIFE — Singapore’s national longevity insurance scheme. CPF LIFE pays a fixed monthly income for the rest of your life, however long you live.
The larger your RA at 65, the higher your monthly payout. You can also defer the payout start date from 65 to as late as 70 — each year of deferral increases the monthly amount by approximately 7%. See the full CPF LIFE deferral analysis for a side-by-side comparison.
Members who were already receiving monthly payouts under the old Retirement Sum Scheme (RSS) before CPF LIFE was mandatory may remain on RSS.
Budget 2026 Changes Affecting the RA
Two Budget 2026 changes are relevant to CPF RA holders:
1. One-Off CPF RA Top-Up (December 2026)
Singaporeans born in 1976 or earlier (aged 50+ in 2026) with retirement savings below the FRS will receive a one-off top-up in December 2026:
- Savings below $60,000 and property AV ≤ $21,000: $1,500
- Savings below $60,000 and property AV $21,001–$31,000: $500
- Savings at least $60,000 but below $110,200: $1,000
2. Higher Contribution Rates for Senior Workers (from January 2027)
Total CPF contribution rates will increase for senior employees:
- Workers aged 55–60: +1.5 percentage points
- Workers aged 60–65: +1.0 percentage point
The extra contributions go into the RA (up to the FRS), directly boosting retirement savings. Employers will receive a CPF Transition Offset equal to half their 2027 contribution rate increase.
Disclaimer: This article is for general information only and does not constitute financial advice. CPF rules, interest rates and retirement sums are subject to change. Verify current figures at cpf.gov.sg before making decisions. As at October 2026.
Frequently Asked Questions
What is the CPF Retirement Account (RA)?
When is the RA created and how?
What happened to the CPF Special Account in January 2025?
What is the 2026 Full Retirement Sum (FRS)?
Can I top up my CPF Retirement Account after 55?
How much interest does the CPF RA earn?
Can I withdraw money from my CPF RA at 55?
How does the CPF RA link to CPF LIFE?
Related Tools & Guides
- CPF RA Top-Up Calculator Singapore — Model how much extra payout you get for each top-up amount
- Retirement Planning Calculator Singapore — Build your full retirement income projection
- CPF Retirement Sums Explained (Pillar) — BRS, FRS and ERS deep-dive
- Enhanced Retirement Sum Singapore 2026 — Top up to $440,800 for maximum CPF LIFE payouts
- CPF Withdrawal at 55 — What you can take out and what stays in CPF
- CPF LIFE: Start at 65 or Defer to 70? — The numbers behind deferring your payout
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.