TL;DR
- Singapore non-employed households 65+ spend an average of S$2,349/month (SingStat HES, 2023)
- CPF LIFE pays from age 65: BRS ~S$950/mo · FRS ~S$1,780/mo · ERS ~S$3,440/mo (Standard Plan, male)
- Your savings fill the gap between CPF LIFE and your target monthly lifestyle
- For a Comfortable HDB life at S$3,200/month (FRS holder): gap = S$1,420/mo — needs ~S$355,000 in investments at 4.8% yield
- Use the Retirement Calculator to plug in your own figures
The S$1,384. That figure — the average per-member monthly spending of a non-employed Singapore household aged 65 or over, from the Singstat Household Expenditure Survey 2023 — circulates in personal finance discussions as proof you can retire cheaply here. And in one narrow sense, it is true: if you own an HDB flat outright, split costs with a spouse, and eat hawker food daily, you can get by on roughly that amount per person.
But getting by is not the same as retiring well. And for most working Singaporeans in their 40s and 50s today — planning a retirement that may span 25 to 30 years — the more useful question is not “what is the minimum?” but “what does my lifestyle actually require, and does my CPF LIFE payout cover it?”
This guide builds three practical monthly budget tiers for Singapore retirement in 2026, maps each against what CPF LIFE pays as your income floor, and shows you the savings gap your investment portfolio needs to fill.
For the full FIRE-based “the number” calculation — including the 25× and 33× portfolio rules specific to Singapore — see FIRE Singapore: The Number You Actually Need.
Why “How Much” Is Not One Answer
Your monthly retirement spend in Singapore can swing by S$2,000 or more depending on four variables:
- Housing type. HDB owners who have fully paid off their flat face near-zero accommodation cash cost — just S&CC, utilities and minor maintenance of roughly S$250–S$350/month. Condo residents pay S$500–S$800/month in maintenance fees alone, before utilities.
- Couple vs. single. A couple shares fixed costs. Per-person spending in a couple is typically 30–40% lower than living solo because housing, utilities and subscriptions are divided.
- Healthcare trajectory. MediShield Life premiums alone for a 65-year-old run around S$1,763/year (S$147/month). An Integrated Shield Plan (IP) rider adds another S$150–S$400/month depending on your age band and plan type. Healthcare costs tend to climb in your 70s and 80s.
- Discretionary lifestyle. Travel, dining out, hobbies, gifts to grandchildren — this is the biggest swing factor and it is entirely personal.
With that context, here are three tiers that cover the realistic range for most working Singaporeans.
Three Monthly Budget Tiers — Singapore 2026
| Tier | Profile | Single / month | Couple / month |
|---|---|---|---|
| Essential | HDB flat owned outright, hawker meals, public transport, minimal travel | S$1,800–S$2,200 | S$2,800–S$3,200 |
| Comfortable | HDB flat, occasional restaurants, Grab + MRT, one annual trip | S$3,000–S$3,500 | S$4,500–S$5,200 |
| Comfortable-Plus | Condo or larger HDB, regular dining out, car, 2–3 overseas trips/year | S$5,000–S$6,500 | S$7,500–S$9,000 |
As at Oct 2026. Based on SingStat HES 2023 and field estimates. Not financial advice.
Essential Tier — S$1,850–S$2,000/month (Single Person, HDB)
| Category | Monthly (SGD) |
|---|---|
| Housing (S&CC, utilities, town council) | S$280 |
| Food (hawker, wet market, coffeeshop) | S$550 |
| Transport (MRT/bus + occasional taxi) | S$150 |
| Healthcare (MediShield Life premiums + co-pays) | S$200 |
| Personal care, phone, internet | S$150 |
| Clothing & miscellaneous | S$120 |
| Leisure & family | S$200 |
| Total | ~S$1,650–S$1,850 |
This is a frugal but dignified retirement. CPF LIFE at FRS (S$1,780/month) almost fully covers this tier — the gap is S$0 to S$70 for most people, effectively covered by any modest savings or interest income.
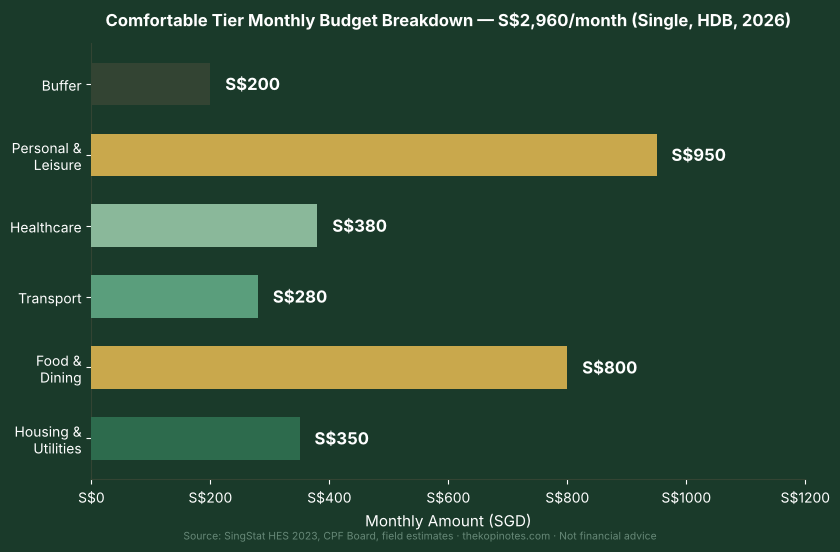
Comfortable Tier — S$2,960–S$3,200/month (Single Person, HDB)
| Category | Monthly (SGD) |
|---|---|
| Housing (S&CC, utilities, maintenance) | S$350 |
| Food (hawker + restaurants 3–4×/week) | S$800 |
| Transport (MRT/bus + ~8 Grab/month) | S$280 |
| Healthcare (MediShield Life + basic IP rider) | S$380 |
| Personal care, phone, internet, streaming | S$200 |
| Clothing & personal shopping | S$250 |
| Leisure & travel (1 SEA trip/year, annualised) | S$500 |
| Contingency buffer | S$200 |
| Total | ~S$2,960–S$3,200 |
This is the most realistic “I worked hard, I want to enjoy retirement” target for an HDB-owning Singaporean. CPF LIFE at FRS (S$1,780/month) covers about 56% of this budget — the remaining S$1,200–S$1,420/month needs to come from your investment portfolio.
Comfortable-Plus Tier — S$5,000–S$5,500/month (Single Person, Condo)
| Category | Monthly (SGD) |
|---|---|
| Housing (condo maintenance + utilities) | S$900 |
| Food (restaurants, groceries, home cooking) | S$1,000 |
| Transport (car: depreciation, insurance, ERP, petrol) | S$1,200 |
| Healthcare (IP full rider or upgraded plan) | S$500 |
| Personal care, phone, internet, services | S$300 |
| Clothing & personal shopping | S$400 |
| Leisure & travel (2–3 trips/year, annualised) | S$900 |
| Contingency & buffer | S$300 |
| Total | ~S$5,500 |
A car and condo alone add roughly S$2,100/month vs. the Comfortable HDB tier. This lifestyle almost certainly requires CPF LIFE at ERS (S$3,440/month) plus a substantial investment portfolio of S$500,000 or more in non-CPF assets.
What CPF LIFE Pays You: Your Income Floor
CPF LIFE is Singapore’s national longevity annuity. You set aside a retirement sum in your CPF Retirement Account (RA) at age 55, and from age 65, you receive a fixed monthly payout for life — regardless of how long you live.
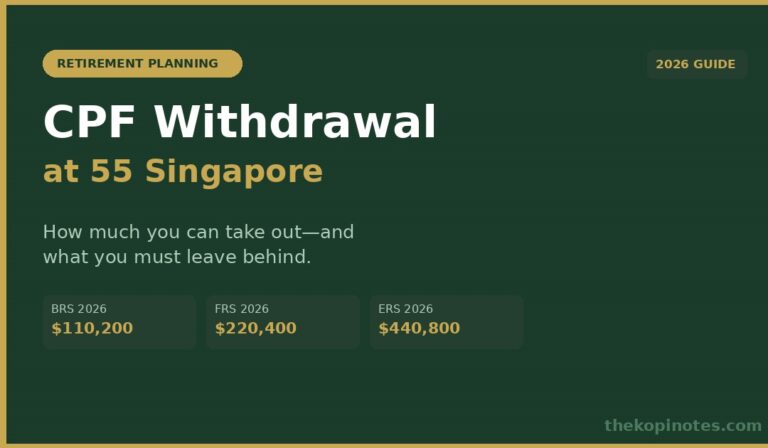
The three retirement sums for 2026 and their estimated Standard Plan payouts from age 65 are:
| Retirement Sum (2026) | Amount at 55 | Est. RA balance at 65 | Est. monthly payout from 65 |
|---|---|---|---|
| Basic (BRS) | S$110,200 | ~S$170,200 | ~S$950 |
| Full (FRS) | S$220,400 | ~S$330,100 | ~S$1,780 |
| Enhanced (ERS) | S$440,800 | ~S$650,100 | ~S$3,440 |
Source: CPF Board, as at Sep 2026. Assumes CPF LIFE Standard Plan, male member, 6% p.a. interest. Female members receive slightly lower initial payouts but equivalent lifetime income. See the full breakdown in our CPF Retirement Sum 2026 guide.
Mapping CPF LIFE to Your Tier: The Gap
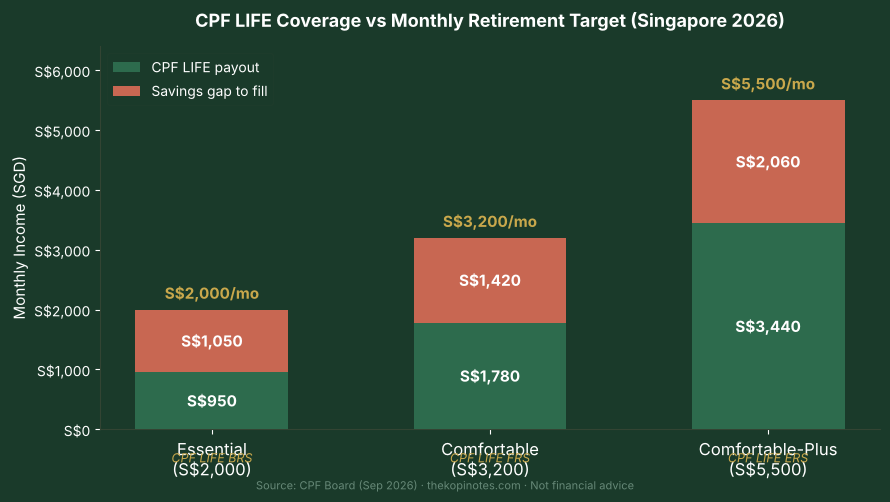
Now the critical question: how much does CPF LIFE cover, and how large is the gap your savings portfolio needs to fill?
| Tier | Monthly target | CPF LIFE | Monthly gap | Annual gap |
|---|---|---|---|---|
| Essential (single) | S$2,000 | S$1,780 (FRS) | S$220 | S$2,640 |
| Comfortable (single) | S$3,200 | S$1,780 (FRS) | S$1,420 | S$17,040 |
| Comfortable-Plus (single) | S$5,500 | S$3,440 (ERS) | S$2,060 | S$24,720 |
A few key observations:
- Essential tier at FRS: CPF LIFE covers 89% of spending. The S$220/month gap is small enough to be met by SRS drawdown, savings interest, or occasional freelance work. This is the most achievable retirement floor.
- Comfortable tier at FRS: A S$1,420/month gap. At a 4.8% portfolio withdrawal rate, you need approximately S$355,000 in non-CPF investments to fill it indefinitely.
- Comfortable-Plus at ERS: Even topping up to ERS, the gap is S$2,060/month — requiring a further S$515,000 or more in investments at 4.8%.
Worked Example: The Comfortable HDB Retirement
Let’s put concrete numbers to the most common scenario.
Profile: Boon, 55 years old, HDB flat fully paid off, CPF Retirement Account at FRS (S$220,400). He wants to retire at 65 on a Comfortable budget of S$3,200/month.
- CPF LIFE payout from 65 (Standard Plan): ~S$1,780/month
- Monthly gap to fill from investments: S$1,420
- Annual drawdown needed: S$17,040
If Boon’s investment portfolio (a mix of Singapore Savings Bonds, S-REITs and ETFs) yields 4.8% per year in dividends and interest, the lump sum needed at age 65 to sustain this drawdown without depleting principal is:
S$17,040 ÷ 0.048 = S$355,000
He has 10 years to build this portfolio. If his investments compound at 5% p.a., the equivalent amount he needs today (in present value terms) is:
S$355,000 ÷ (1.05)10 ≈ S$218,000
Alternatively: setting aside S$1,380/month into a 5% p.a. investment account for the next 10 years reaches S$214,000 by age 65 — close enough to cover the gap.
This is why non-CPF portfolio building matters as much as hitting FRS. CPF LIFE is the floor. Your investment portfolio is the house.
These figures are illustrative and do not account for inflation. Actual payouts depend on CPF LIFE plan type and prevailing interest rates.
Three Adjustments That Can Change Your Number
1. HDB Monetisation
If you own an HDB flat, you may be able to access capital or additional income through the HDB Lease Buyback Scheme — selling part of your remaining lease back to HDB for a combination of CPF top-ups and cash. Alternatively, renting out a spare room generates S$800–S$1,200/month in passive income for heartland flats, directly reducing your monthly savings gap.
2. SRS Drawdown
Contributions to your Supplementary Retirement Scheme (SRS) account grow tax-free and can be drawn down from age 62. Only 50% of each SRS withdrawal is taxable — making it exceptionally efficient once you’re in a lower income bracket. Building an SRS balance during your working years, then drawing it down between ages 62 and 65 (the gap before CPF LIFE starts), reduces the pressure on your investment portfolio. Learn more about CPF and SRS top-up strategies.
3. CPF Top-Up to ERS
If you can afford to top up your CPF Retirement Account to ERS (S$440,800 at 55) — whether through voluntary top-ups or CPF top-up contributions in your accumulation years — the ERS payout of S$3,440/month eliminates the gap entirely for the Essential and Comfortable tiers (single person), and covers a large portion of the Comfortable tier for a couple. The trade-off: S$220,400 more locked in CPF vs. accessible in a brokerage account. For those who value guaranteed income over portfolio flexibility, ERS is a compelling choice. See the full discussion in our CPF Retirement Sum 2026 guide.
Frequently Asked Questions
What is a realistic monthly budget to retire in Singapore?
For a single person owning an HDB flat in 2026, a realistic budget ranges from S$1,800/month (essential, frugal) to S$3,200/month (comfortable, including occasional dining and one annual trip). A couple can live comfortably for S$4,500–S$5,200/month combined. These figures are based on SingStat household expenditure data and typical Singapore living costs.
How much does CPF LIFE pay per month in 2026?
Under the Standard Plan from age 65: approximately S$950/month at BRS, S$1,780/month at FRS, and S$3,440/month at ERS. These are CPF Board estimates as at September 2026, assuming a male member at 6% p.a. interest. Female members receive a slightly lower initial payout but equivalent total lifetime income.
Can I retire in Singapore on S$2,000 per month?
Yes, if you own your HDB flat outright and have no significant debt. S$2,000/month per person covers essentials including hawker meals, public transport, basic healthcare via MediShield Life, utilities, and a small leisure buffer. CPF LIFE at FRS (S$1,780/month) covers 89% of this budget, leaving a gap of just S$220/month.
What happens if I retire before 65, before CPF LIFE starts?
You need to fund the ‘gap years’ between your early retirement date and age 65 entirely from your investment portfolio or SRS drawdown. For example, retiring at 60 means 5 fully self-funded years before CPF LIFE kicks in. This is the gap period in FIRE planning and is why many Singapore early retirees keep a larger liquid portfolio than the CPF floor alone would suggest.
Is S$1 million enough to retire in Singapore?
It depends on your CPF position and lifestyle. At a 4.8% portfolio withdrawal rate, S$1 million generates roughly S$4,000/month. Paired with CPF LIFE at FRS (S$1,780/month), a single person would have ~S$5,780/month — well above the Comfortable tier. A couple with two CPF LIFE payouts and a combined S$1 million portfolio could sustain a Comfortable-Plus lifestyle. The key variable is whether your S$1 million is in CPF (which yields the LIFE payout) or in a brokerage account (where you manage the withdrawal rate yourself).
Should I target FRS or ERS for CPF LIFE?
Most working Singaporeans naturally reach FRS or slightly above through regular CPF contributions over a career. If you can afford to voluntarily top up to ERS (S$440,800 at 55), the guaranteed S$3,440/month is powerful — especially for a single person targeting a comfortable, car-free retirement without relying heavily on investment returns. The main trade-off is that ERS locks an additional S$220,400 into CPF, reducing your liquid investable assets. See the full comparison in our CPF Retirement Sum 2026 guide.
Plan Your Number
This article gives you the benchmark context. To run the actual calculation with your own CPF balance, target age, and savings:
- Singapore Retirement Calculator 2026 — plug in your numbers and see your gap
- Retirement Planning Calculator — our interactive tool for monthly spend targets
- FIRE Singapore: The Number You Actually Need — the full FIRE number framework, Singapore-specific
Disclaimer: This article presents retirement budget estimates and CPF data for educational purposes only, as at October 2026. It does not constitute financial advice. CPF LIFE payout figures are estimates published by CPF Board and may differ based on your plan type, gender, and actual CPF balances. Speak with a licensed financial adviser before making retirement planning decisions.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.