Frasers Centrepoint Trust Share Price 2026 (SGX: J69U): 2H2026 DPU Outlook & Suburban Mall Recovery
Last Updated: October 7, 2026 | Category: S-REITs | Ticker: SGX J69U
Not financial advice. Always verify data with official FCT investor relations disclosures before investing.
Frasers Centrepoint Trust (FCT, SGX: J69U) remains one of Singapore’s most resilient S-REITs — a pure-play suburban retail trust that has quietly delivered strong results while the broader property market navigated higher interest rates. With the 1H FY2026 DPU rising 1.4% to S$0.06136, Hougang Mall’s AEI completing in September 2026, and portfolio committed occupancy hitting a near-perfect 99.8%, FCT’s 2H2026 distribution outlook is increasingly compelling.
In this deep-dive, we break down what drove FCT’s 1H2026 performance, what to expect for the 2H2026 distribution payout, and whether the current FCT share price offers an attractive entry point for Singapore dividend investors.
📋 Table of Contents
Contents — Click to Expand
- What Is Frasers Centrepoint Trust?
- FCT Share Price Performance in 2026
- 1H FY2026 Results: DPU Up 1.4%
- FCT DPU History: Half-Year Breakdown
- 2H2026 DPU Outlook: What to Expect
- FCT Mall Portfolio: 9 Singapore Suburban Malls
- Hougang Mall AEI: Income Booster Incoming
- Gearing & Financial Health
- FCT Dividend Yield vs Peer REITs 2026
- Is FCT a Buy, Hold or Sell in 2026?
- Where to Buy FCT: Broker Referral Codes
- FAQ
What Is Frasers Centrepoint Trust?
Frasers Centrepoint Trust is Singapore’s largest pure-play suburban retail REIT, listed on the SGX since 2006. It owns nine income-producing retail properties — all located in Singapore’s heartland residential townships — with a total NLA of approximately 2.2 million square feet.
FCT’s sponsor is Frasers Property Limited, one of Singapore’s largest property developers. The REIT’s income is largely non-discretionary retail: supermarkets, food & beverage, healthcare, childcare, and essential services that serve surrounding HDB communities. This gives FCT notably defensive income characteristics compared to office or industrial REITs.
Key Facts: Frasers Centrepoint Trust (SGX: J69U)
| Metric | Value (2026) |
|---|---|
| SGX Ticker | J69U |
| REIT Manager | Frasers Centrepoint Asset Management |
| Sponsor | Frasers Property Limited |
| No. of Malls | 9 |
| Total NLA | ~2.2 million sq ft |
| Committed Occupancy | 99.8% (1H FY2026) |
| 1H FY2026 DPU | S$0.06136 (+1.4% YoY) |
| Aggregate Leverage | ~39.6% |
| Distribution Frequency | Semi-annual (May & Nov) |
FCT Share Price Performance in 2026
FCT’s share price has broadly tracked the recovery in S-REIT valuations through 2026, benefiting from expectations of further Fed rate cuts and Singapore’s strong retail footfall data. The stock has traded in the S$2.20–S$2.40 range for much of 2026, with sentiment improving as the rate cycle appears to be easing.
At approximately S$2.30–S$2.35 (early October 2026), FCT’s annualised trailing DPU yield works out to roughly 5.1–5.3% based on the 1H FY2026 DPU of S$0.06136 doubled. This is somewhat compressed relative to FCT’s historical 5–6% range but reflects the trust’s near-premium quality: near-perfect occupancy, defensive income, AEI pipeline, and a top-tier sponsor.
For context, FCT has delivered significantly better occupancy and rental reversion than most retail peers — including many office and industrial REITs — making its premium valuation easier to justify. See our FCT FY2026 results preview for the full fundamental analysis.
1H FY2026 Results: DPU Up 1.4% to S$0.06136
FCT delivered a solid 1H FY2026 (October 2025 to March 2026), with distribution per unit rising 1.4% year-on-year to S$0.06136 cents. The distribution was paid on 29 May 2026.
Key highlights from 1H FY2026:
- Total distributable income: Rose strongly, reflecting the Northpoint City South Wing contribution
- Rental reversion: +6.5% across renewals — well above inflation
- Committed occupancy: 99.8% (up from 98.1% previously)
- Tenant retention rate: 87%
- Shopper traffic: Up YoY, consistent with Singapore’s strong domestic consumption
- Tenants’ sales: Increased, confirming healthy consumer spending at FCT malls
The one caveat: total distributions to unitholders rose 13.6% to S$125 million, but this was partly because units in issue grew ~12.0% from the equity fundraising that funded the Northpoint City South Wing acquisition. On a per-unit basis, the improvement was a more modest 1.4%. That said, 1.4% DPU growth in a still-elevated interest rate environment is creditable for a retail REIT.
FCT DPU History: Half-Year Breakdown
The table below tracks FCT’s semi-annual distribution per unit across recent fiscal years. FCT’s financial year runs April to March.
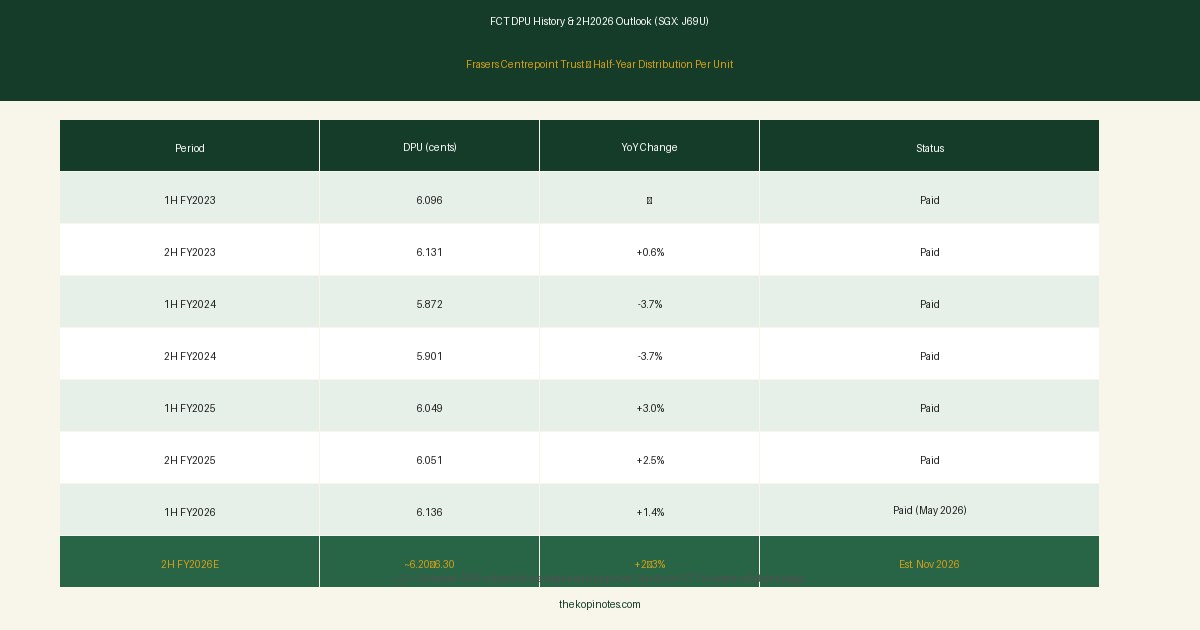
* 2H FY2026E is an estimate. FCT’s 2H FY2026 results (Apr–Sep 2026) will be announced around October–November 2026. The payout is expected around November 2026. Always verify with official FCT investor relations announcements.
Key takeaway: FCT’s DPU dipped in FY2024 as higher borrowing costs ate into distributable income, but has since recovered steadily in FY2025 and early FY2026. The 2H2026 DPU should benefit from the full-quarter contribution of Hougang Mall post-AEI.
2H2026 DPU Outlook: What to Expect
FCT’s 2H FY2026 (April–September 2026) results will be announced around October–November 2026, with the distribution payout expected around late November 2026.
Here are the key factors that could drive the 2H2026 DPU higher:
- Hougang Mall AEI completion (September 2026): The S$51 million AEI targeting ~7% ROI is expected to complete in September 2026, bringing an upgraded tenant mix (80%+ pre-committed) and a boost to Hougang Mall’s NPI. This should start contributing meaningfully from 2H2026 onwards.
- Full-period Northpoint City South Wing income: The acquisition has been in the portfolio for a full period, meaning no pro-rata adjustment — clean contribution for 2H.
- Continued strong rental reversions: FCT’s +6.5% reversion trend in 1H suggests leases expiring in 2H will be renewed at higher rates, sustaining NPI growth.
- Interest cost stabilisation: With Fed rate cuts materialising in 2026 and FCT’s borrowing costs partially hedged, there may be modest savings on interest expenses in 2H.
- Resilient suburban footfall: Singapore’s heartland malls — particularly near MRT hubs — have continued to attract steady traffic. FCT’s locations (Woodlands, Yishun, Punggol, Tampines) benefit from captive residential catchments.
Our estimate: FCT’s 2H FY2026 DPU could come in at approximately S$0.062–0.063 cents, bringing the full-year FY2026 DPU to roughly S$0.123–0.124. At an FCT share price of ~S$2.30, this implies a full-year yield of approximately 5.3–5.4%.
FCT Mall Portfolio: 9 Singapore Suburban Malls
FCT’s portfolio concentrates on suburban Singapore — areas that benefit from large captive HDB residential populations and excellent MRT connectivity. All nine malls are located in the suburbs, not in Orchard Road or the CBD.
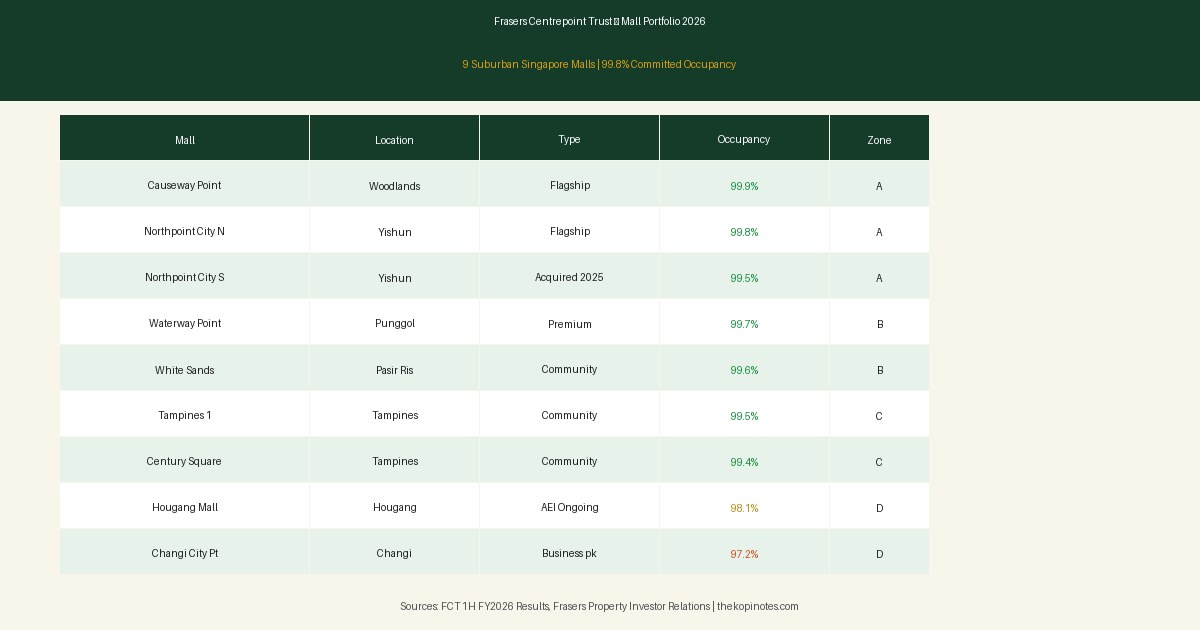
What makes FCT’s portfolio particularly defensive is the nature of its tenant mix — heavily weighted towards food & beverage, supermarkets, healthcare, and daily essentials. These sectors are far less exposed to e-commerce cannibalisation than fashion or electronics retail. When Singaporeans can walk downstairs to their neighbourhood mall, they do — and FCT’s near-perfect occupancy proves the concept works.
Flagship Malls
Causeway Point (Woodlands) and Northpoint City (Yishun) are FCT’s two flagship properties, each serving as the de-facto community retail hub for their respective towns. Causeway Point benefits from Woodlands Checkpoint proximity (cross-border shoppers) and strong HDB density. Northpoint City, comprising both North Wing and the newly acquired South Wing, is the largest mall in Northern Singapore.
Waterway Point
Waterway Point (Punggol) anchors FCT’s Eastern portfolio. Punggol is one of Singapore’s fastest-growing new towns and Waterway Point — directly connected to Punggol MRT — is the only major mall serving the catchment. This structural monopoly position makes it particularly resilient.
Hougang Mall AEI: Income Booster Incoming
One of the most important near-term catalysts for FCT’s 2H2026 DPU is the completion of the Hougang Mall Asset Enhancement Initiative (AEI):
- Total capex: S$51 million
- Target ROI: ~7% (translating to approximately S$3.6 million in additional annual NPI)
- Pre-commitment: Over 80% of new/reconfigured spaces committed pre-completion
- Completion target: September 2026
- Expected contribution: From 4Q FY2026 onwards (i.e., 2H FY2026 financial year)
A 7% ROI on S$51 million capex implies roughly S$3.6 million in incremental annual NPI. Given FCT’s ~2 billion units in issue (post equity fundraising), this represents an additional ~S$0.0018 per unit per year, or approximately 0.09 cents per unit per half-year. While modest in isolation, it adds to an already strong growth trajectory and demonstrates FCT’s active portfolio management approach.
The key question is whether the fully committed spaces at Hougang Mall can sustain their pre-committed rents — early indicators appear positive given Singapore’s resilient domestic retail environment.
Gearing & Financial Health
FCT’s aggregate leverage (gearing) stood at approximately 39.6–40.3% in early 2026, elevated from historical norms due to the Northpoint City South Wing acquisition and ongoing AEI capex. While this is below the MAS regulatory cap of 50%, it leaves a tighter buffer than FCT’s historical <35% gearing.
Key financial health indicators:
| Metric | FY2026 Level | Assessment |
|---|---|---|
| Aggregate Leverage | ~39.6–40.3% | Elevated; monitoring needed |
| Interest Cover Ratio | ~3.0–3.2x | Adequate |
| Debt Hedging Ratio | ~75–80% | Well hedged |
| % Debt at Fixed Rate | ~75%+ | Rate risk mitigated |
| Debt Maturity Profile | Well-staggered (no cliff) | Manageable |
The gearing of ~40% is worth monitoring, particularly if property valuations were to decline. However, given FCT’s high occupancy, strong NPI, and fixed-rate hedging, there is no immediate refinancing risk. As the Fed continues its rate-cutting cycle, FCT’s floating-rate debt costs should also gradually decrease — a tailwind for 2H2026 and beyond.
FCT Dividend Yield vs Peer REITs 2026
How does FCT stack up against comparable S-REITs in terms of dividend yield and quality? The table below provides a snapshot as at October 2026 (approximate figures — verify current prices and DPU on official sources):
| REIT | Type | Approx Yield | Occupancy |
|---|---|---|---|
| Frasers Centrepoint Trust (J69U) | Suburban Retail | ~5.3% | 99.8% |
| CapitaLand Ascendas REIT (A17U) | Industrial | ~5.2% | ~93% |
| Mapletree Logistics Trust (M44U) | Logistics | ~6.1% | ~96% |
| Suntec REIT (T82U) | Office + Retail | ~6.8% | ~96% |
| Keppel DC REIT (AJBU) | Data Centre | ~4.8% | ~98% |
FCT trades at a yield premium to KDC REIT (the premium data centre REIT) but at a discount to higher-risk REITs like Suntec or MLT. This positioning reflects FCT’s quality defensive characteristics — investors willingly accept a lower yield for the certainty of near-perfect occupancy and non-discretionary retail income.
Is FCT a Buy, Hold or Sell in 2026?
Based on the available data, here is a balanced assessment of FCT’s investment case for Q4 2026:
✅ Reasons to be Bullish on FCT
- Near-perfect 99.8% occupancy — structural demand for heartland retail space
- Hougang Mall AEI completing in September 2026 — NPI uplift from 2H2026
- +6.5% rental reversion — well above CPI, suggesting pricing power
- Northpoint City South Wing fully integrated into portfolio
- Fed rate cuts reducing floating-rate borrowing costs through 2H2026
- Strong sponsor (Frasers Property) with ROFR on quality retail assets
⚠️ Key Risks to Monitor
- Elevated gearing at ~40% — limited buffer for additional acquisitions
- Post-AEI Hougang Mall ramp-up risk — can it sustain 80%+ committed occupancy?
- Yield compression at ~5.3% offers limited margin of safety vs rate risk
- SGD strength vs other S-REITs’ foreign income (FCT is purely SG domestic — good in SG, but no FX upside)
- Rising construction costs could impact future AEI ROI assumptions
Bottom line: FCT is a quality hold for income investors who prioritise DPU stability and near-zero occupancy risk over maximum yield. Those seeking higher near-term yield should consider MLT or Suntec REIT instead. FCT is most suitable for defensive, long-term dividend investors — particularly those using CPF-OA or SRS to invest in quality S-REITs.
This is not financial advice. Please do your own research and consult a licensed financial adviser before investing.
Where to Buy FCT: Singapore Broker Referral Codes 2026
FCT (SGX: J69U) is available on all major Singapore brokerage platforms. Here are our recommended brokers with exclusive referral codes for TKN readers:
| Broker | Best For | Referral Code | Perk |
|---|---|---|---|
| FSMOne | SGX REITs + regular savings | P0544985 | Cash rebates on SGX trades |
| Syfe | S-REIT portfolio / Syfe REIT+ | SRPRFFFCD | Fee waiver up to 6 months |
| Endowus | CPF/SRS investing in REITs | 2V343 | S$20 access fee credit |
| IBKR | Active traders, low commissions | jianxiong368 | Cash bonus on deposit |
Disclosure: TKN earns referral commissions from the links above at no extra cost to you. Always compare fees before investing.
Frequently Asked Questions About Frasers Centrepoint Trust
What is Frasers Centrepoint Trust's share price today?
FCT’s share price fluctuates with market conditions. As at October 2026, FCT (SGX: J69U) was trading in the approximate range of S$2.20–S$2.40. Check Google Finance, SGX, or your brokerage platform for the live price.
When is FCT's next distribution payout?
FCT distributes semi-annually. The 1H FY2026 distribution (S$0.06136 per unit) was paid on 29 May 2026. The 2H FY2026 distribution (for April–September 2026) is expected to be announced around October–November 2026, with payout likely in late November 2026. Check FCT’s investor relations page for exact record and payment dates.
What is FCT's dividend yield in 2026?
Based on the 1H FY2026 DPU of S$0.06136 (annualised to ~S$0.123) and a share price of ~S$2.30, FCT’s trailing dividend yield is approximately 5.1–5.3%. If the 2H DPU comes in at ~S$0.062–0.063, the full-year yield would be approximately 5.3–5.4% at current prices.
Is FCT a good buy in 2026?
FCT is widely regarded as a defensive, high-quality S-REIT with near-perfect occupancy (99.8%), strong rental reversions (+6.5%), and a resilient suburban retail portfolio. The Hougang Mall AEI completing in September 2026 adds near-term income uplift. However, elevated gearing (~40%) and yield compression relative to higher-risk REITs are factors to weigh. It suits long-term, income-focused investors. This is not financial advice.
Does FCT qualify for CPF and SRS investing?
Yes. FCT (SGX: J69U) is listed on the SGX main board and is eligible for CPF-OA and SRS investment under the CPFIS scheme. Check with your broker (e.g., Endowus for SRS, FSMOne for CPF) to confirm current eligibility and any applicable conditions.
What malls does Frasers Centrepoint Trust own?
As at 2026, FCT owns nine malls in Singapore: Causeway Point (Woodlands), Northpoint City North Wing (Yishun), Northpoint City South Wing (Yishun, acquired 2025), Waterway Point (Punggol), White Sands (Pasir Ris), Tampines 1 (Tampines), Century Square (Tampines), Hougang Mall (Hougang), and Changi City Point (Changi).
What is FCT's aggregate leverage (gearing) in 2026?
FCT’s aggregate leverage stood at approximately 39.6–40.3% in early 2026, elevated due to the Northpoint City South Wing acquisition and Hougang Mall AEI capex. This is below the MAS regulatory cap of 50%, but higher than FCT’s historical levels. Monitor quarterly results for any changes to gearing levels.
Related Articles: FCT FY2026 Results Preview | FCT Q4 Rate-Cut DPU Recovery | FSMOne Referral Code
© 2026 The Kopi Notes. Not financial advice. All data approximate — verify with official FCT investor relations announcements and SGX filings.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.