How to Top Up Your Medisave Account in Singapore (2026 Step-by-Step Guide)
PayNow, $8,000 tax relief, BHS cap of $79,000, and the Matched MediSave Scheme — everything Singapore residents need to know.
You can top up your Medisave account online in minutes using PayNow via the CPF website or mobile app. The 2026 Basic Healthcare Sum (BHS) cap is $79,000 — you may contribute up to the gap between your balance and $79,000. Cash top-ups earn income tax relief of up to $8,000 per year for your own account, and an additional $8,000 for qualifying family members.
Not financial advice. All figures are for educational reference only. Data verified as at 3 October 2026. Sources: CPF Board (cpf.gov.sg) and IRAS (iras.gov.sg).
Table of Contents
Contents — Click to expand
- Why Top Up Your Medisave?
- Medisave Basic Healthcare Sum (BHS) Cap for 2026
- How to Top Up Medisave: Step-by-Step (All Methods)
- How to Top Up Medisave for Family Members
- Tax Relief for Medisave Top-Ups
- Matched MediSave Scheme — Free $1,000 Government Top-Up
- Important Reminders Before You Top Up
- Frequently Asked Questions
Why Top Up Your Medisave?
Medisave is your dedicated healthcare savings account within the CPF system. It covers hospitalisation bills, approved outpatient treatments, MediShield Life premiums, and Integrated Shield Plan (ISP) premiums. As ISP premiums rise steeply with age and new co-payment rider rules take effect from 2024 to 2026, ensuring your Medisave has a healthy buffer has become more important than ever.
There are three strong practical reasons to top up proactively:
1. Offset rising ISP premiums. ISP premiums increase significantly after age 60 — often by 30–50% per decade — and are deducted directly from Medisave. If your Medisave balance runs low, you may need to pay ISP premiums in cash, which removes the tax-deferral advantage. See our analysis of how the new Medisave deductible changes affect your ISP costs in 2026 for a detailed breakdown.
2. Earn substantial tax relief. A voluntary cash top-up of $8,000 to your own Medisave saves between $960 and $3,360 in income tax per year, depending on your marginal tax rate. At the 20% rate (taxable income ~$80,000–$120,000 p.a.), topping up $8,000 saves approximately $1,600 in tax. That is an immediate 20% guaranteed return on the contributed amount.
3. Qualify for government matching. If you are aged 55 to 70 and meet the income criteria, the Matched MediSave Scheme provides a dollar-for-dollar government top-up of up to $1,000 per year — effectively doubling your first $1,000 in contributions. For details, see our dedicated Matched MediSave Scheme 2026 guide.
Many Singaporeans underestimate how quickly Medisave can be depleted by hospitalisation. If you have ever wondered what a hospital bill looks like without an ISP, understanding hospitalisation costs without an ISP makes a strong case for maintaining a well-funded Medisave account.
Medisave Basic Healthcare Sum (BHS) Cap for 2026
The Basic Healthcare Sum (BHS) is the maximum amount the CPF Board allows you to hold in your Medisave Account at any one time. The BHS increases each year for members below 65 to keep pace with rising healthcare costs. For 2026, the BHS is:
| Member Group | BHS 2026 | Notes |
|---|---|---|
| Members below 65 years old | $79,000 | Increased from $75,500 in 2025 |
| Members turning 65 in 2026 | $79,000 | Fixed for life at this cohort BHS |
| Members aged 66 and above | Previous cohort BHS | Not affected by 2026 BHS increase |
Source: CPF Board news release, January 2026 (cpf.gov.sg)
Once your Medisave balance reaches your applicable BHS, no further voluntary top-ups are accepted. If a top-up would cause your balance to exceed the BHS, the entire contributed amount is automatically refunded to your registered bank account — it is not partially accepted up to the cap.
How to calculate your maximum top-up amount:
Maximum top-up = $79,000 (BHS) − Your current Medisave balance
For example, if your current Medisave balance is $52,000, you can top up a maximum of $27,000. You can check your current Medisave balance at any time by logging into the CPF Member Portal or the CPF mobile app under “Healthcare.”
How to Top Up Medisave: Step-by-Step (All Methods)
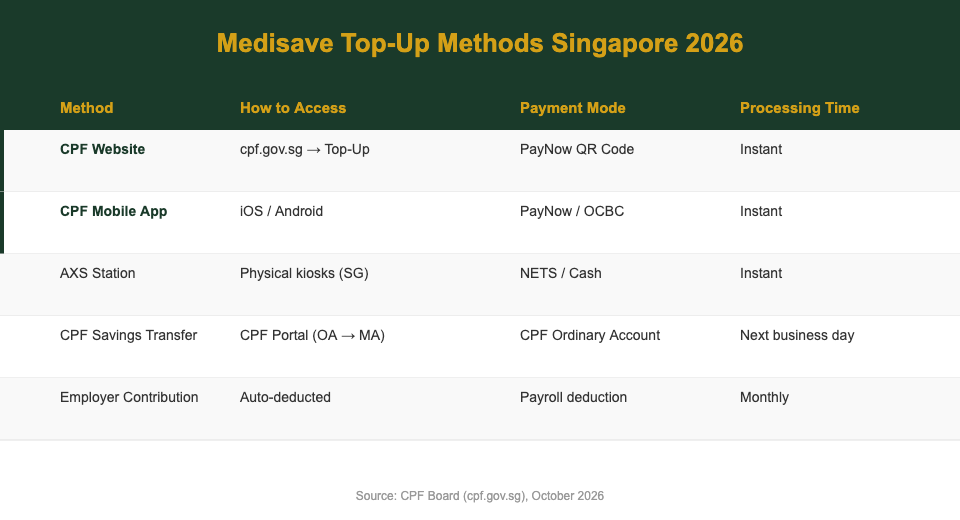
The CPF Board provides several ways to make a voluntary top-up to your Medisave Account. The fastest and most widely used method is PayNow via the CPF website, but alternatives exist for those who prefer physical channels or wish to use existing CPF savings.
Method 1: CPF Website (Recommended — PayNow)
- Log in to the CPF Member Portal at cpf.gov.sg using your Singpass.
- Navigate to “Tools & Services” → “Top Up MediSave Account”.
- Select whether you are topping up for yourself or a family member.
- Enter the top-up amount (minimum $1; must not exceed your BHS gap).
- Click “Submit” to generate a PayNow QR code.
- Open your bank’s mobile app, scan the QR code, and authorise the payment.
- The top-up is credited to your Medisave account immediately upon successful PayNow payment.
Step-by-step guides in English, Chinese, Malay, and Tamil are available as downloadable PDFs from the CPF website.
Method 2: CPF Mobile App
Download the official CPF Mobile app from the App Store (iOS) or Google Play (Android). After logging in via Singpass Face Verification, go to “Top Up” → “MediSave Account.” Payment can be made via PayNow QR or directly through OCBC Digital if you hold an OCBC account. The app displays your current Medisave balance and calculates your available top-up room automatically.
Method 3: AXS Stations (Physical Kiosks)
AXS stations located at MRT stations, shopping centres, selected community clubs, and government service centres accept Medisave top-ups via NETS or credit/debit card. This is the preferred option for members who are not comfortable with internet banking or who wish to handle the transaction in person.
Method 4: Transfer from CPF Ordinary Account (OA → MA)
If you prefer to use your existing CPF Ordinary Account savings rather than cash, you can apply to transfer funds from your OA to your Medisave Account via the CPF portal (“Top Up MediSave Account Using CPF Savings” form). Note that this transfer is irreversible — OA funds moved to Medisave cannot be returned to the OA. Additionally, OA-to-MA transfers do not qualify for income tax relief, as that relief applies only to cash top-ups.
How to Top Up Medisave for Family Members
Singapore residents can make voluntary Medisave top-ups on behalf of their parents, grandparents, grandparents-in-law, spouse, siblings, children, in-laws — or even any other CPF member. The process is nearly identical to topping up for yourself.
To top up a family member’s Medisave:
- Log in to the CPF Member Portal with your own Singpass.
- Go to “Top Up MediSave Account” and select “Top Up for Someone Else.”
- Enter the recipient’s NRIC or FIN number to look up their account.
- Enter the top-up amount (capped at the recipient’s BHS gap) and pay via PayNow.
The top-up is credited to the recipient’s Medisave account, and you — the payer — may be eligible to claim income tax relief on the amount contributed (subject to conditions — see the Tax Relief section below).
Planning Medisave top-ups for ageing parents is an increasingly common strategy in Singapore as ISP premiums for the 70+ age group can exceed $5,000 per year. For a full look at how ISP costs evolve in retirement, see our guide to the best integrated shield plan for Singapore retirees in 2026.
Tax Relief for Medisave Top-Ups
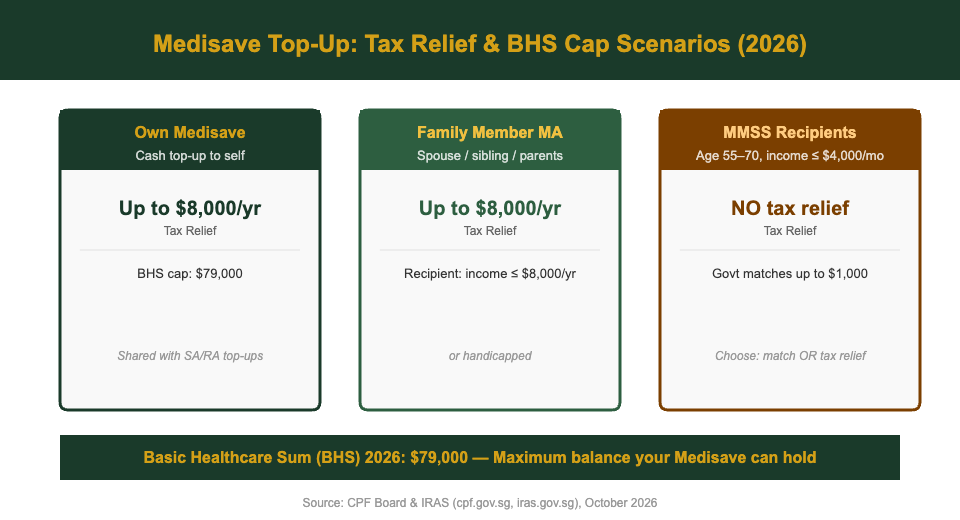
Voluntary cash top-ups to your Medisave Account qualify for income tax relief under the CPF Cash Top-Up Relief scheme, administered by IRAS. This makes Medisave top-ups one of the most tax-efficient savings moves available to Singapore residents.
| Top-Up Recipient | Max Annual Tax Relief | Key Conditions |
|---|---|---|
| Your own Medisave / SA / RA (combined) | $8,000 | Cash top-up only (not OA transfer) |
| Spouse or sibling’s Medisave / SA / RA | $8,000 | Recipient earns ≤ $8,000/yr or is handicapped |
| Parents / grandparents / in-laws | $8,000 | No income condition for parents; combined cap applies |
| Total maximum across self + loved ones | Up to $16,000 | Subject to overall $80,000 personal relief cap |
Source: IRAS CPF Cash Top-Up Relief guidance; CPF Board (cpf.gov.sg), October 2026
Critical note on the $8,000 cap: The $8,000 annual limit is shared across all your voluntary cash top-ups to your own Special Account (SA), Retirement Account (RA), and Medisave Account combined. It is not $8,000 per account type. If you top up $5,000 to your SA and $3,000 to your Medisave, you have reached the $8,000 ceiling for your own accounts.
Worked example — SGD 120,000 annual income (20% marginal rate):
A Singapore resident earning $120,000 per year who tops up $8,000 to their own Medisave and $8,000 to their mother’s Medisave (mother earns less than $8,000/year) can claim $16,000 in tax relief — saving approximately $3,200 in income tax for the year (at 20%). The CPF top-up effectively returns 20 cents on every dollar contributed through tax savings alone, before any healthcare benefit.
For a comprehensive look at how Medisave fits into your overall retirement planning alongside SRS contributions, CPF-SA top-ups, and investment accounts, see our guide on CPF investment strategy for Singapore residents and use our Singapore retirement calculator to model your numbers.
Matched MediSave Scheme — Free $1,000 Government Top-Up
The Matched MediSave Scheme (MMSS) is a government programme that provides a dollar-for-dollar matching grant of up to $1,000 per year for eligible seniors who top up their own Medisave Account. If you qualify and contribute $1,000, the government adds another $1,000 — effectively doubling your healthcare savings at no additional cost.
Matching grants are credited to your Medisave account at the beginning of the following year (e.g., top-ups made in 2026 receive the 2026 matching grant in early 2027).
| Eligibility Criterion | Requirement (2026) |
|---|---|
| Age | Aged 55 to 70 as at 31 December of the assessment year |
| Medisave balance | Less than half of applicable BHS (i.e., below $39,500 in 2026) |
| Average monthly income | $4,000 or less (assessed over the year) |
| Annual value of property | $21,000 or less |
| Properties owned | One or fewer |
Source: CPF Board / MOH Matched MediSave Scheme guidelines, 2026 (cpf.gov.sg)
MMSS vs. Tax Relief — you must choose:
This is the detail most Singaporeans miss. The first $1,000 of your top-up that attracts the MMSS matching grant does not qualify for income tax relief. The two benefits are mutually exclusive on the same $1,000:
- MMSS route: Top up $1,000 → Receive $1,000 government match → Zero tax relief on that $1,000
- Tax relief route: Top up $1,000 → No government match → Claim tax relief (worth ~$100–$420 at your marginal rate)
For most eligible seniors (typically in lower tax brackets after retirement), the MMSS dollar-for-dollar match is the better deal — a 100% guaranteed return on the first $1,000 is hard to beat. Higher earners still in the workforce might calculate otherwise at the top marginal rates.
For a full breakdown of MMSS eligibility, how to apply, and how it interacts with other CPF schemes, see our dedicated Matched MediSave Scheme 2026 guide.
Important Reminders Before You Top Up
Before confirming any Medisave top-up, keep the following rules in mind — they cannot be undone after the fact:
1. All top-ups are irreversible. Once credited to a Medisave Account, funds can only be used under approved Medisave withdrawal schemes (hospitalisation, ISP premiums, approved outpatient treatments, MediShield Life premiums). You cannot reverse a top-up even in financial hardship.
2. Excess top-ups are refunded in full. If a top-up would cause your Medisave balance to exceed the BHS of $79,000, the CPF system refunds the entire amount (not just the excess) to your registered bank account. Always check your current balance before topping up.
3. Self-employed persons must settle arrears first. If you are self-employed with outstanding mandatory MediSave contributions (based on your net trade income), you must settle these before the CPF Board will accept voluntary top-ups.
4. The $80,000 personal relief cap. All CPF-related tax reliefs combined — including employee CPF contributions, voluntary top-ups, SRS contributions, and other qualifying reliefs — cannot exceed $80,000 per year. If you are already close to this cap, the tax benefit of a Medisave top-up may be partially or fully absorbed.
5. OA-to-MA transfers do not give tax relief. Only cash top-ups qualify for the CPF Cash Top-Up Relief. Transfers from your OA savings to Medisave are not eligible for the tax deduction.
Frequently Asked Questions
How do I top up my Medisave account in Singapore?
You can top up your Medisave account online in three ways: (1) log in to the CPF Member Portal at cpf.gov.sg, go to “Tools & Services” → “Top Up MediSave Account,” enter your amount, and pay via PayNow QR; (2) use the CPF mobile app with PayNow or OCBC Digital; or (3) visit a physical AXS station and pay via NETS or card. All methods credit the top-up to your Medisave immediately. Top-ups are irreversible once made.
What is the maximum amount I can top up to my Medisave in 2026?
The maximum top-up is the difference between the Basic Healthcare Sum (BHS) and your current Medisave balance. For 2026, the BHS is $79,000 for members below 65. If your Medisave currently holds $55,000, you can top up a maximum of $24,000. If a top-up would push your balance above the BHS, the entire amount is refunded — the CPF system does not partially accept a top-up that exceeds your cap.
Do I get tax relief for topping up my Medisave?
Yes. Cash top-ups to your own Medisave Account qualify for CPF Cash Top-Up Relief of up to $8,000 per year (shared with top-ups to your SA or RA). You can claim a further $8,000 in relief for cash top-ups to a qualifying family member’s Medisave. This is one of Singapore’s most tax-efficient deductions — at the 20% marginal rate, an $8,000 top-up saves $1,600 in income tax. Note: top-ups qualifying for the MMSS government matching grant do not receive tax relief.
Can I top up Medisave for my parents?
Yes. You can top up Medisave for your parents, grandparents, parents-in-law, grandparents-in-law, spouse, siblings, and children. Log in to the CPF Member Portal, select “Top Up for Someone Else,” and enter the recipient’s NRIC. For top-ups to parents and grandparents, you can claim income tax relief without any income condition on the recipient. For siblings and spouses, the recipient must earn $8,000 or less per year or be handicapped to qualify the payer for tax relief.
What is the Matched MediSave Scheme and who qualifies?
The Matched MediSave Scheme (MMSS) is a government programme that matches your voluntary Medisave top-up dollar-for-dollar, up to $1,000 per year. To qualify in 2026, you must be aged 55–70 as at 31 December, have a Medisave balance below half the BHS (i.e., below $39,500), earn an average monthly income of $4,000 or less, own one or fewer properties with an annual value of $21,000 or less. Importantly, top-ups that attract the MMSS matching grant do not qualify for income tax relief — the two benefits are mutually exclusive.
Can I reverse a Medisave top-up if I change my mind?
No — Medisave top-ups are irreversible. Once funds are credited to a Medisave Account, they can only be used under CPF Board-approved healthcare schemes such as hospitalisation claims, MediShield Life premiums, Integrated Shield Plan premiums, and approved outpatient treatments. There is no mechanism to refund a voluntary top-up back to your bank account, even in financial hardship. This is why it is important to check your current balance and calculate your top-up limit before proceeding.
Plan Your Medisave & ISP Strategy
Use our retirement calculator to model how much to set aside in Medisave — alongside ISP premiums, SRS, and CPF-SA top-ups.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.