MediSave for Hospitalisation 2026: Ward A, B1, B2 & ISP Rider Claims Explained
Daily limits, deductibles, co-payment caps and what you actually pay — by ward class
MediSave covers up to S$1,130 per day for the first two days of inpatient hospitalisation and S$400 per day from day three onwards — but how much you pay out of pocket depends heavily on your ward class, your MediShield Life deductible, and whether you hold an Integrated Shield Plan (ISP) rider. This guide breaks down every layer by ward class, including the new April 2026 rider changes that affect all new ISP policyholders.
Not financial advice. All figures are for educational reference only. Data verified as at 17 September 2026 against CPF Board and MOH official sources.
- MediSave pays $1,130/day (days 1–2) then $400/day (day 3+) regardless of ward class.
- Your deductible ranges from $1,500 (Class C) to $2,500 (Class A/Private) under MediShield Life and ISPs.
- From April 2026, new ISP riders can no longer cover your minimum deductible — and the co-payment cap doubled from $3,000 to $6,000/year.
Singapore Ward Classes Explained
Singapore’s public hospitals offer four main ward classes. Your ward choice determines your subsidy level, your MediShield Life coverage, and your ISP rider’s relevance.
| Ward Class | Setting | Subsidy | Room Type | MediShield Life Covers? |
|---|---|---|---|---|
| Class C | Restructured hospital | Up to 65–80% | 5–9 bedded | ✅ Yes (primary) |
| Class B2 | Restructured hospital | Up to 50–65% | 5–6 bedded | ✅ Yes (primary) |
| Class B1 | Restructured hospital | No subsidy | 4 bedded, AC | ⚠️ Partially (ISP recommended) |
| Class A | Restructured hospital | No subsidy | Single or 2-bed, AC | ⚠️ Partially (ISP strongly recommended) |
| Private | Private hospital | No subsidy | Single, premium | ❌ Minimal (ISP essential) |
Source: Ministry of Health Singapore, ward class guide (2026)
MediShield Life was designed primarily for Class B2 and C wards. If you choose a higher ward class — B1, A, or private — you need an Integrated Shield Plan (ISP) to avoid a large out-of-pocket bill.
MediSave Daily Hospitalisation Limits (2026)
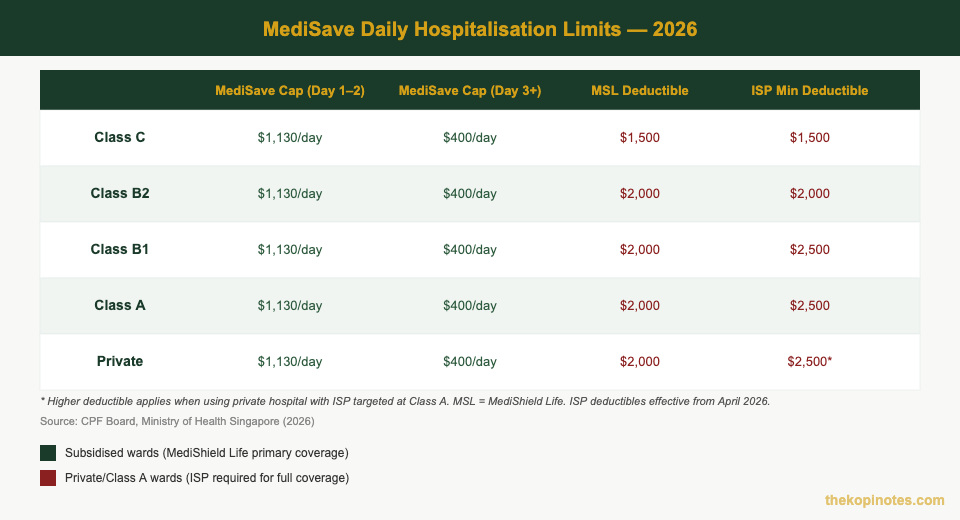
MediSave covers your hospital bill based on a per-day cap — not a percentage of the actual bill. These limits apply to all ward classes equally, from Class C to private hospitals.
Here’s what the caps cover: ward charges, specialist fees, treatment, investigations, medicines, and implants — all bundled into this daily cap. If your actual bill exceeds the cap, you pay the difference.
For example, a 5-day stay in Class B1 with a $6,000 total ward charge would have MediSave cover: (2 × $1,130) + (3 × $400) = $3,460. The remaining $2,540 comes from MediShield Life and/or your ISP.
These limits have been effective since April 2025 and remain unchanged for 2026. Check the CPF Board’s official hospitalisation limits page for the latest schedule.
Source: CPF Board & Ministry of Health Singapore (2026)
The chart above shows how the daily MediSave limits and the minimum deductibles interact across ward classes. For a deeper look at how your total hospitalisation claim is processed step-by-step, read our MediSave hospitalisation step-by-step guide.
MediShield Life Deductibles & Co-Insurance
Before MediShield Life pays a single dollar, you must first meet your annual deductible. This resets every year. Here are the 2026 figures:
- Class C ward: $1,500 annual deductible
- Class B2 and above: $2,000 annual deductible
- Aged 81 and above: add $1,000 to the above amounts
After your deductible is met, MediShield Life covers the remaining eligible bill — but not 100%. You pay co-insurance on top. The co-insurance rate is tiered:
| Claimable Amount (After Deductible) | Co-Insurance Rate (You Pay) | MediShield Life Pays |
|---|---|---|
| First $5,000 | 10% | 90% |
| Next $5,000 | 7% | 93% |
| Above $10,000 | 3% | 97% |
Source: CPF Board, MediShield Life benefit schedule (2026)
From 1 June 2026, the annual MediShield Life claim limit rose to $200,000 (up from $150,000). There is no lifetime cap. This means a catastrophic illness won’t eat through a fixed ceiling over time.
For more details on what MediShield Life covers at each claim tier, see our guide on MediShield Life benefits Singapore 2026.
ISP Riders & the April 2026 Rule Changes
An ISP rider is an optional add-on that sits on top of your base ISP. Riders traditionally covered your deductible and co-insurance — essentially wiping out your out-of-pocket costs. That changed in 2026.
What Changed on 1 April 2026
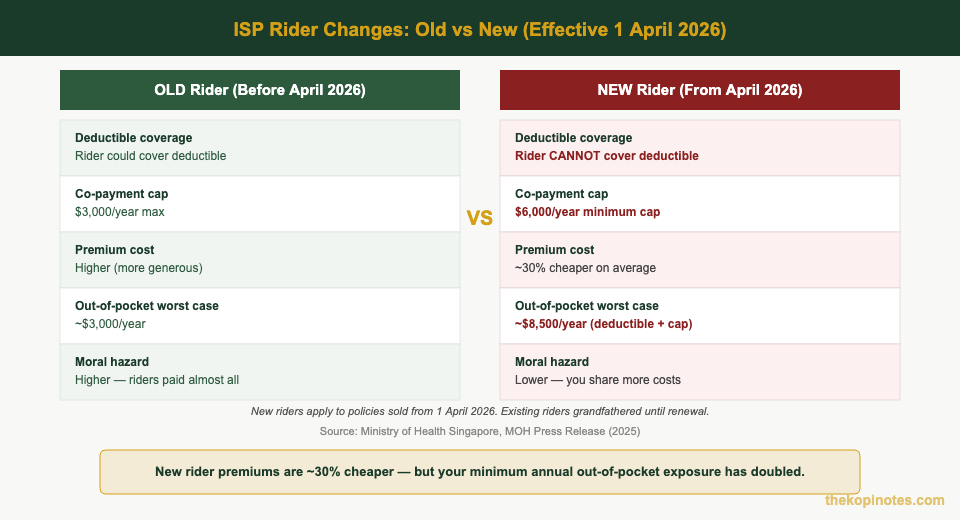
MOH introduced new requirements for ISP riders effective 1 April 2026. Here’s what you need to know:
- Riders can no longer cover the minimum ISP deductible. You must pay your deductible out of pocket, every year you’re hospitalised.
- The minimum co-payment cap doubled — from $3,000 to $6,000 per year. This is the maximum you’ll pay in co-insurance (excluding the deductible) in a policy year.
- New rider premiums dropped by ~30% on average compared to the old, more generous versions.
- Existing riders are grandfathered — they stay the same until you renew or switch.
For a full breakdown of the new co-payment structure, including worked examples, read our guide on ISP co-payment 2026 changes.
What This Means for Your Out-of-Pocket Bill
Under the new rules, your worst-case annual exposure for Class A or private hospitalisation is roughly:
- Minimum ISP deductible: $2,500 (Class B1/A/Private)
- Maximum co-payment cap: $6,000
- Total worst-case: ~$8,500 per year
Under the old rules, that figure was capped at $3,000 in co-payments (plus the deductible your rider covered). The new structure is less generous — but it comes with lower premiums and aims to slow down healthcare inflation driven by over-consumption.
Source: Ministry of Health Singapore — MOH announcement on ISP rider requirements (2025)
Minimum Deductibles by Ward Class (ISP, from April 2026)
These are the minimum deductibles that new ISP riders cannot cover:
- Class C: $1,500
- Class B2: $2,000
- Class B1, A, or Private: $2,500
Your insurer sets your ISP deductible at or above these minimums. Check your policy documents or your insurer’s website for your specific deductible amount.
Using MediSave to Pay ISP Premiums (AWL)
Your ISP base premium can be paid using MediSave — but only up to the Additional Withdrawal Limit (AWL). The AWL depends on your age at the time of payment:
| Age Group | MediSave AWL (per year) | What It Covers |
|---|---|---|
| 40 and below | $300 | ISP base plan premium only |
| 41 to 70 | $600 | ISP base plan premium only |
| 71 and above | $900 | ISP base plan premium only |
Source: CPF Board, Additional Withdrawal Limits for Integrated Shield Plans (2026)
Important: ISP rider premiums cannot be paid using MediSave at all. You must pay them in cash. Only the MediShield Life portion and the base ISP premium portion are MediSave-eligible (within the AWL).
If your ISP base premium exceeds the AWL for your age, you pay the remainder in cash too. Premiums tend to rise significantly after age 60, so factor this into your long-term healthcare budgeting. Our Singapore retirement planning calculator can help you model these costs.
Practical Example: $30,000 Class A Hospital Bill
Let’s work through a real-world example. You’re admitted to a Class A ward at a restructured hospital for 6 days. The total subsidised bill is $30,000. You hold a Class A ISP base plan plus a rider purchased before April 2026.
Step 1 — MediSave pays your daily cap:
- Days 1–2: 2 × $1,130 = $2,260
- Days 3–6: 4 × $400 = $1,600
- Total MediSave: $3,860
Step 2 — Remaining bill: $30,000 − $3,860 = $26,140
Step 3 — MediShield Life deductible: $2,000 (you pay this first, from cash or MediSave)
Step 4 — Claimable amount: $26,140 − $2,000 = $24,140
MediShield Life covers:
- 90% of first $5,000 = $4,500 (you pay $500 co-insurance)
- 93% of next $5,000 = $4,650 (you pay $350 co-insurance)
- 97% of remaining $14,140 = $13,716 (you pay $424 co-insurance)
- Total co-insurance you pay: $500 + $350 + $424 = $1,274
Your pre-rider out-of-pocket: $2,000 (deductible) + $1,274 (co-insurance) = $3,274
If you have an old rider (before April 2026), the rider covers the deductible and most co-insurance. If you have a new rider (from April 2026), you pay at least the $2,500 ISP deductible out of pocket. In this example, the co-insurance of $1,274 is below the $6,000 cap — so your new rider covers it. Your total out-of-pocket with a new rider: $2,500 (deductible) + $0 (rider covers co-insurance) = $2,500.
Frequently Asked Questions
How much can I claim from MediSave for hospitalisation in 2026?
What is the difference between the MediShield Life deductible and the ISP deductible?
Did the ISP rider co-payment cap change in 2026?
Can I use MediSave to pay my ISP rider premium?
What happens if I stay in a ward class higher than my ISP covers?
Has the MediShield Life annual claim limit changed in 2026?
Which ISPs cover Class A and private hospital wards in Singapore?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.