CPF MediSave Cap & ISP Premiums: Will Your Shield Plan Be Covered as You Age? (2026)
Your CPF MediSave cap — officially called the Basic Healthcare Sum (BHS) — is $79,000 in 2026. While your MediShield Life base premiums are fully payable from MediSave, your Integrated Shield Plan (ISP) rider premium is subject to an Additional Withdrawal Limit (AWL) of just $300 to $900 per year depending on your age. As ISP premiums climb steeply after age 50, the MediSave shortfall can reach thousands of dollars annually — meaning more cash out of pocket the older you get.
Not financial advice. All figures are for educational reference only. Data verified as at 6 September 2026 unless noted.
- The MediSave cap (BHS) is $79,000 in 2026 — it limits accumulation in your MA, not how much you can use per year.
- Your ISP rider premium above MediShield Life is subject to an AWL: $300/year (age 40 and below), $600/year (41–70), or $900/year (71+).
- ISP premiums escalate sharply in your 60s and 70s, but the AWL stays flat — expect a growing cash gap as you age.
In This Guide
What Is the CPF MediSave Cap (BHS)?
The Basic Healthcare Sum (BHS) is the maximum balance your CPF MediSave Account (MA) can hold. For 2026, the BHS is $79,000 — rising each year to keep pace with healthcare costs.
Here is the key point many people miss: the BHS cap controls how much you can accumulate in MediSave. It does not directly limit how much you can spend from MediSave on healthcare in a given year.
Once your MA hits $79,000, additional contributions overflow automatically. If you are under 55, excess flows to your Special Account (SA). If you are 55 and above, excess flows to your Retirement Account (RA) — up to the Full Retirement Sum — then to your Ordinary Account (OA).
To understand how your CPF MediSave Account works in full — including contribution rates and all approved uses — check our dedicated guide.
How ISP Premiums Are Deducted from MediSave
If you hold an Integrated Shield Plan, your annual premium has two separate components — and MediSave treats them very differently.
Component 1: MediShield Life base premium. This is the government-mandated health insurance layer all Singapore Citizens and PRs must have. CPF Board deducts this from your MediSave with no annual cap. It happens automatically.
Component 2: The ISP rider premium. This is the extra you pay to upgrade your coverage from MediShield Life’s Class B2/C ward standard to Class A wards or private hospitals. This portion is subject to the AWL.
Your insurer charges you one combined annual premium. CPF automatically allocates the MediShield Life base portion first, then applies the AWL to the rider portion. Any rider premium beyond the AWL must be paid in cash.
| Premium Component | Paid From | Annual Cap? |
|---|---|---|
| MediShield Life Base Premium | MediSave (MA) | No cap — fully deductible |
| ISP Rider Premium (above MediShield Life) | MediSave up to AWL, then cash | Yes — AWL of $300–$900/year by age |
| Balance above AWL | Cash (GIRO) | No limit |
Source: CPF Board, MOH 2026.
The Additional Withdrawal Limit (AWL) Explained
The AWL is the maximum amount CPF allows you to withdraw from MediSave per year specifically for the ISP rider portion of your premium. Think of it as a sub-limit within your MA, reserved for ISP top-ups.
For 2026, the AWL tiers are:
| Age Band | Annual AWL for ISP Rider |
|---|---|
| Age 40 and below | $300 per year |
| Age 41 to 70 | $600 per year |
| Age 71 and above | $900 per year |
Source: CPF Board / MOH 2026.
The AWL is deliberately modest. MOH set it this way to prevent over-reliance on MediSave for insurance premiums, keeping your MA available for actual medical bills. The problem: ISP premiums grow steeply with age while the AWL rises only in two small steps. The result is a widening cash gap.
The Growing Gap: ISP Premiums Rise, AWL Stays Flat
Walk through a concrete example. Say you are on a mid-tier ISP — a Class A ward plan from one of the major insurers.
In your 30s, your total annual ISP premium might be around $500–$700. The MediShield Life base covers roughly $200–$300, and the rider portion of around $300 fits within the $300 AWL. You pay nothing in cash.
Fast-forward to your 60s. Your total ISP premium has grown to $1,800–$2,500. MediShield Life base covers $700–$900. That leaves $1,100–$1,600 as the rider portion — but your AWL is only $600. You are paying $500–$1,000 per year in cash.
By your 70s, the cash gap can exceed $1,500–$2,500 per year — even for a Plan B (Class A ward) policy.
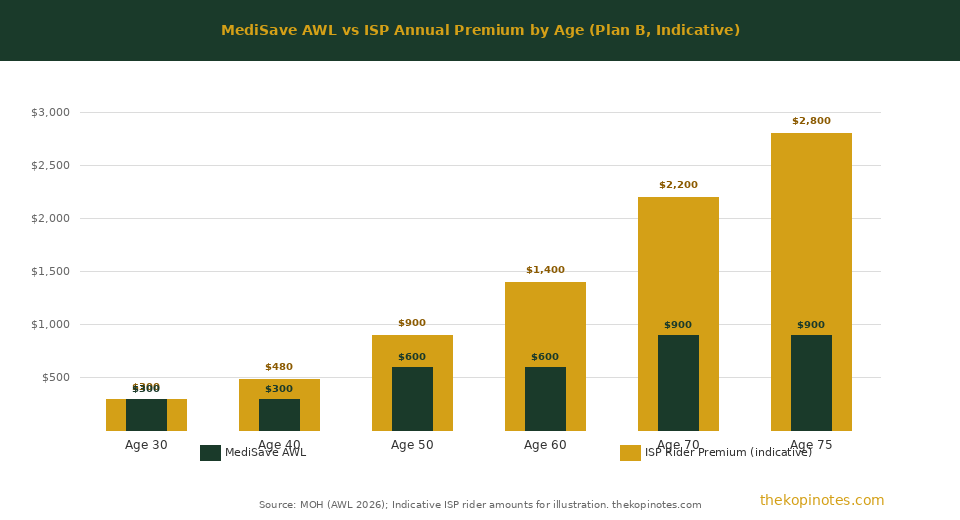
Source: MOH (AWL 2026); ISP rider premiums are indicative for illustration. Actual amounts vary by insurer, plan tier, and health history.
| Age | ISP Rider Portion (indicative) | AWL Available | Cash Gap |
|---|---|---|---|
| Age 30 | ~$300 | $300 | ~$0 |
| Age 45 | ~$550 | $600 | ~$0 |
| Age 60 | ~$1,300 | $600 | ~$700 |
| Age 72 | ~$2,200 | $900 | ~$1,300 |
Rider portion = total ISP premium minus MediShield Life base premium. Figures are indicative for a mid-tier ISP (Class A ward). Source: TKN estimates based on published insurer schedules and MOH withdrawal limits, September 2026.
The takeaway: MediSave largely covers ISP premiums in your 40s. After age 55–60, budget for an increasing annual cash payment. To compare ISP options including premium escalation, see our best Integrated Shield Plan comparison guide.
What Happens When Your MediSave Falls Short?
If your AWL is exhausted for the year — or if your MA balance is low — you must pay the outstanding ISP rider premium in cash via GIRO.
If you miss the cash payment, your ISP lapses. You revert to MediShield Life-only coverage (Class B2/C ward standard). Reinstating a lapsed policy requires a new application and underwriting — pre-existing conditions may then be excluded. This is why proactively budgeting for the growing cash gap matters.
This risk is highest for self-employed individuals with lower MA balances, early retirees who stop CPF contributions, and older policyholders whose premiums have escalated well beyond the $900 AWL.
The good news: MediShield Life itself never lapses. CPF continues to pay base premiums from your MA automatically. Only the ISP rider requires active management.
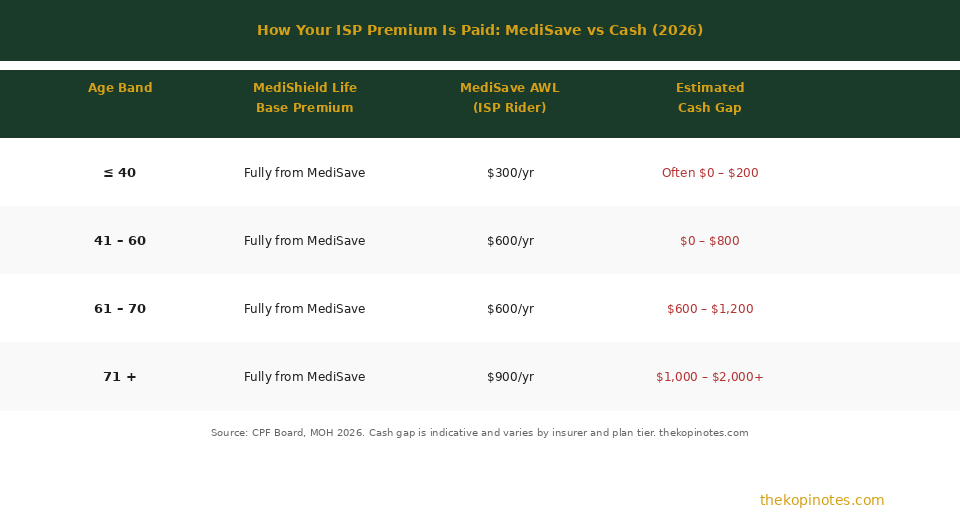
Source: CPF Board, MOH 2026. Cash gap is indicative and varies by insurer and plan tier.
For a full breakdown of what your base coverage includes, see our guide on what MediShield Life covers — and where the ISP rider adds real value.
Strategies to Manage Your MediSave for ISP Coverage
1. Keep Your MediSave Topped Up
If you are self-employed or on a career break, your MA does not receive automatic employer contributions. Make voluntary top-ups to keep your balance healthy. Every dollar in MediSave earns a risk-free 4% interest per year in 2026 — one of the best guaranteed returns available in Singapore. If your MA is already at $79,000, top-ups overflow to SA or RA — still useful for retirement.
2. Choose Your ISP Tier Carefully
The difference between Plan A (private hospital) and Plan B (Class A public ward) can be $800–$1,200 per year in premiums by age 60. If private hospital access is not essential, Plan B dramatically reduces your cash outlay in later years. Review your tier every few years. Downgrading from Plan A to Plan B is generally possible; upgrading later may face underwriting.
3. Understand the April 2026 Rider Changes
From 1 April 2026, new ISP riders no longer cover the minimum deductible ($1,500–$3,500 depending on ward). However, new rider premiums dropped by about 30% on average. If you bought your rider before 27 November 2025, you are grandfathered with old benefits until your first renewal after 1 April 2028. Do not switch unless you have a strong reason to. For more detail on these changes and how they affect your MediSave usage, see our ISP rider changes 2026 guide.
4. Budget for a Cash Premium Starting in Your Late 50s
From age 55–60 onward, set aside $500–$1,500 per year specifically for ISP cash premiums. Treat it as a fixed annual expense. Removing the surprise makes this far easier to manage.
5. Review Your ISP Annually at Each Age Band
Premium jumps are not gradual — they spike at age bands (51, 61, 71). Set a yearly reminder to check your new annual premium, your MediSave balance, how much AWL remains, and whether your plan tier still makes sense. For a broader overview of all approved MediSave uses, our MediSave limit 2026 guide covers every withdrawal category.
Frequently Asked Questions
What is the MediSave cap (BHS) in 2026?
How much MediSave can I use to pay my ISP rider premium?
What happens if I cannot pay the cash portion of my ISP premium?
Can I top up MediSave to pay more of my ISP premium?
Does the April 2026 ISP rider change affect how premiums are paid from MediSave?
Is the MediShield Life base premium subject to the AWL?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.