CapitaLand Ascendas REIT Share Price 2027 (A17U): FY2027 DPU Forecast, Gearing & Investor Verdict
A complete deep-dive for Singapore investors — FY2027 DPU forecast, gearing analysis, portfolio quality, and our buy/hold verdict for CLAR in 2027.
CapitaLand Ascendas REIT (SGX: A17U), commonly known as CLAR, is Singapore’s largest diversified industrial REIT with over SGD 17 billion in assets under management across more than 220 properties in Singapore, Australia, the United States, and the United Kingdom/Europe. As 2026 draws to a close, Singapore investors are asking whether CLAR’s FY2027 DPU forecast justifies its current share price — and whether the rate-cut cycle ahead can sustain dividend growth into 2027.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Table of Contents
Contents — Click to expand
- What Is CapitaLand Ascendas REIT (CLAR)?
- Key Facts at a Glance (October 2026)
- FY2026 Performance Review
- FY2027 DPU Forecast & Share Price Outlook
- Portfolio Quality & Occupancy
- Gearing Ratio & Interest Rate Sensitivity
- CLAR vs Industrial REIT Peers
- Is CLAR a Buy, Hold, or Sell in 2027?
- Frequently Asked Questions
What Is CapitaLand Ascendas REIT (CLAR)?
CapitaLand Ascendas REIT (SGX: A17U) is Asia-Pacific’s first and largest industrial REIT. Listed on the Singapore Exchange in 2002, it is managed by CapitaLand Ascendas REIT Management Ltd, a subsidiary of CapitaLand Investment, one of Asia’s largest diversified real estate groups. CLAR’s portfolio spans four key geographies — Singapore, Australia, the United States, and the United Kingdom/Europe — with asset classes including business parks, hi-tech industrial facilities, logistics and distribution centres, suburban offices, and data centre-adjacent campuses.
With a market capitalisation of approximately SGD 12.8 billion and more than 220 properties, CLAR consistently ranks among the top S-REITs by size, liquidity, and institutional ownership. It is also a constituent of the MSCI Singapore Index and regularly included in Singapore STI-adjacent indices. CLAR’s focus on “new economy” assets differentiates it from traditional commercial or retail REITs, giving it structural demand tailwinds from advanced manufacturing, digital logistics, and data infrastructure growth.
Key Facts at a Glance (October 2026)
| Metric | Detail |
|---|---|
| Full Name | CapitaLand Ascendas Real Estate Investment Trust |
| Ticker (SGX) | A17U |
| Manager | CapitaLand Ascendas REIT Management Ltd (CapitaLand Investment subsidiary) |
| Asset Class | Industrial — Business Parks, Hi-Tech, Logistics, Data Centre-Adjacent |
| Geographies | Singapore (~60%), Australia (~20%), United States (~12%), UK/Europe (~8%) |
| No. of Properties | ~225+ (as at Oct 2026) |
| AUM | ~SGD 17.3 billion |
| Market Cap | ~SGD 12.8 billion |
| FY2025 DPU | 15.258 cents per unit |
| FY2026E DPU (Consensus) | ~15.6–15.9 cents per unit |
| Distribution Frequency | Semi-annual (June & December) |
| Gearing Ratio | ~37.2% (as at Q3 2026) |
Source: CapitaLand Ascendas REIT Q3 2026 investor update, SGX announcements, analyst consensus (October 2026). AUM and market cap are approximate and subject to change.
FY2026 Performance Review
CapitaLand Ascendas REIT entered 2026 as one of the more resilient large-cap S-REITs, benefitting from its industrial and logistics portfolio which held occupancy above 93% even as office REITs faced structural headwinds. The Singapore portfolio — comprising approximately 60% of total AUM — delivered stable rental reversions averaging 8–12% in FY2026, driven by demand from advanced manufacturing, cold chain logistics, and technology firms seeking last-mile distribution space.
Across Australia (approximately 20% of AUM), the logistics and suburban office assets continued to post healthy metrics, with Melbourne and Sydney industrial land values rising on constrained supply. In the United States (approximately 12% of AUM), CLAR’s suburban office assets in Raleigh, San Diego, and Portland faced normalisation pressures as hybrid work moderated lease renewals. However, US logistics assets in California and Illinois remained near full occupancy.
The key positive catalyst in 2026 was the US Federal Reserve rate-cutting cycle. By October 2026, the Fed had delivered approximately 100–125 basis points of cumulative cuts since late 2025. With approximately 20–25% of CLAR’s total borrowings on floating rates, every 25bp cut yields roughly SGD 3–4 million in annual interest savings — a modest but meaningful DPU tailwind. CLAR’s 1H2026 DPU came in at approximately 7.65 cents per unit, up approximately 2.0% from 1H2025’s 7.50 cents, setting a full-year FY2026 DPU trajectory of approximately 15.6–15.9 cents.
For Singapore investors, the REIT’s share price recovered from early 2026 lows near SGD 2.62 to the SGD 2.85–2.95 range by October 2026, implying a forward yield of approximately 5.4–5.6%. For a detailed breakdown of the 2H2026 DPU timeline and distributions already declared, see our earlier CapitaLand Ascendas REIT 2H2026 DPU analysis.
FY2027 DPU Forecast & Share Price Outlook
Analyst consensus as at October 2026 projects CLAR’s FY2027 DPU in the range of 15.9–16.4 cents per unit, representing approximately 2–4% growth over FY2026’s estimated 15.6–15.9 cents. Three drivers underpin the FY2027 growth thesis.
First, positive rental reversions in Singapore will continue. CLAR’s Singapore portfolio continues to achieve meaningful uplifts on lease renewals. Industrial and logistics rents are expected to maintain 6–10% positive reversion in FY2027, supported by JTC vacancy rates below 8% — tight industrial land supply that gives quality assets like CLAR’s business parks at Science Park I & II and one-north significant pricing power.
Second, interest savings from ongoing rate cuts. With further Fed cuts expected in 1H2027 (consensus forecasts an additional 50–75bp from current levels), CLAR’s floating-rate debt cost is projected to decrease. Combined with opportunistic refinancing of maturing fixed-rate loans at current lower market rates, management estimates net interest savings of SGD 8–12 million in FY2027 versus FY2026.
Third, potential for accretive acquisitions. CLAR has maintained headroom in its gearing ratio (currently approximately 37%, well below the statutory 50% cap). Management has signalled appetite for selective acquisitions in Singapore and Australia in the SGD 300–800 million range — specifically cold chain logistics and suburban office parks near established tech clusters. A FY2027 acquisition at initial yields of 5.5–6.0% could add 0.2–0.4 cents per unit annually to DPU.
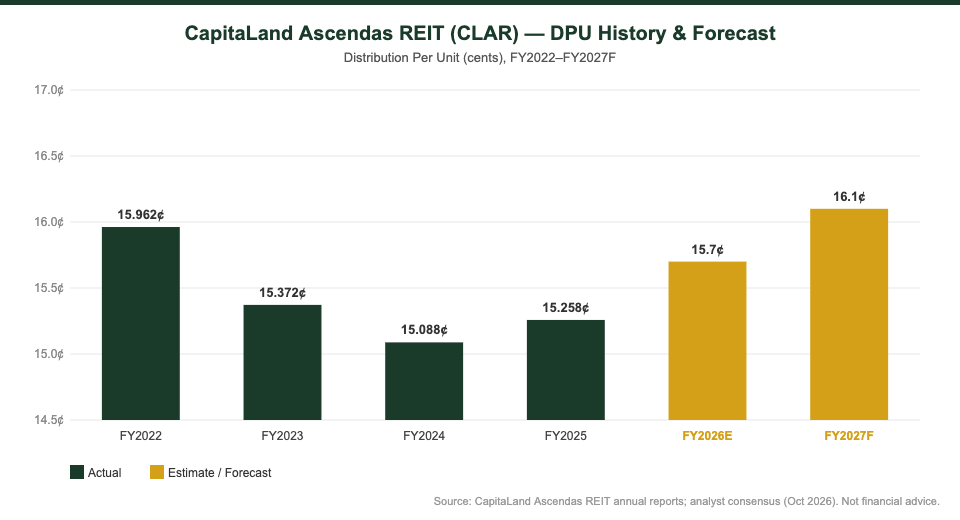
| Year | DPU (cents) | YoY Change | Yield @ SGD 2.90 | Status |
|---|---|---|---|---|
| FY2022 | 15.962 | +3.5% | 5.5% | Actual |
| FY2023 | 15.372 | −3.7% | 5.3% | Actual |
| FY2024 | 15.088 | −1.8% | 5.2% | Actual |
| FY2025 | 15.258 | +1.1% | 5.3% | Actual |
| FY2026E | ~15.7 | +2.9% | 5.4% | Estimate |
| FY2027F | ~16.1 | +2.5% | 5.6% | Forecast |
Source: CapitaLand Ascendas REIT annual reports FY2022–FY2025 (SGX); FY2026E and FY2027F are analyst consensus estimates (Bloomberg, October 2026). Past DPU does not guarantee future distributions. Share price used: SGD 2.90 for yield calculation.
For Singapore investors using a Singapore retirement calculator, a 5.4–5.6% forward yield from CLAR, combined with modest capital appreciation potential, can meaningfully contribute to a passive income Singapore strategy — especially as fixed deposits and T-bills now yield 3.0–3.5%, tightening the yield gap between cash and industrial REITs.
Portfolio Quality & Occupancy
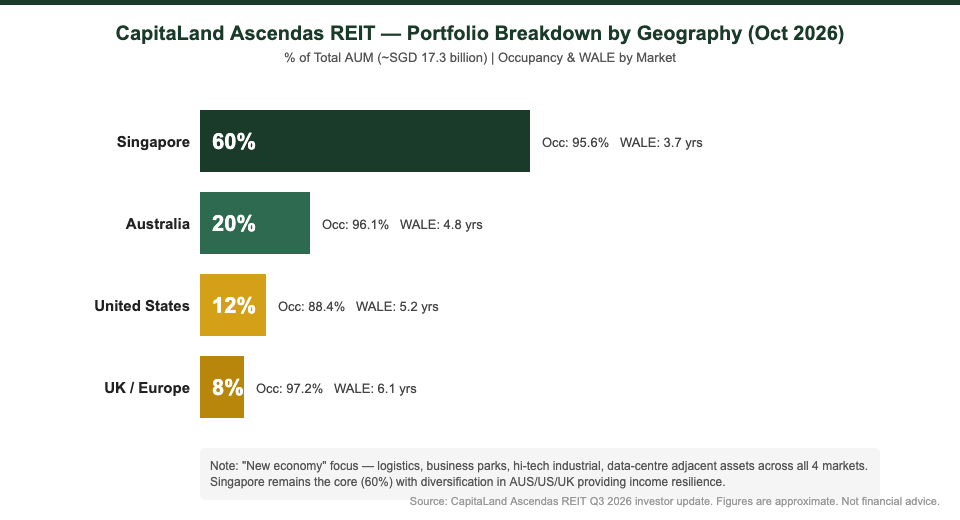
CLAR’s portfolio quality is a cornerstone of its investment case. Unlike retail or office REITs that face structural demand headwinds, industrial assets — particularly logistics facilities, business parks, and hi-tech manufacturing spaces — benefit from supply chain reshoring, data centre expansion, and urban logistics growth. As at Q3 2026, CLAR’s portfolio-level occupancy stood at approximately 93.8%, with Singapore and Australia occupancy remaining strong at 95.6% and 96.1% respectively.
The modest portfolio-level dip from the FY2022 high of 95.4% reflects normalisation in CLAR’s US suburban office portfolio, where vacancy has ticked up to approximately 12% in the Portland and San Diego campuses. However, the UK/Europe portfolio — anchored by long-lease Amazon Logistics, DHL, and Kuehne+Nagel tenants — records the highest occupancy in the group at 97.2%, with a weighted average lease expiry (WALE) of 6.1 years.
| Geography | % of AUM | Occupancy | WALE (years) | Key Asset Types |
|---|---|---|---|---|
| Singapore | ~60% | 95.6% | 3.7 yrs | Business Parks, Hi-Tech, Logistics |
| Australia | ~20% | 96.1% | 4.8 yrs | Logistics, Suburban Office |
| United States | ~12% | 88.4% | 5.2 yrs | Suburban Office, Life Science |
| UK / Europe | ~8% | 97.2% | 6.1 yrs | Logistics Parks, Light Industrial |
Source: CapitaLand Ascendas REIT Q3 2026 investor presentation (October 2026). WALE = Weighted Average Lease Expiry by gross rental income. Occupancy figures are approximate.
The US portfolio (12% of AUM) is the key risk area to monitor. While US suburban offices face structural vacancy pressures sector-wide, CLAR’s management has guided for selective asset recycling — including potential divestments of underperforming campuses and redeployment into Australian logistics or Singapore hi-tech industrial. Any successful divestment at or above book value would be DPU-neutral to mildly accretive in FY2027. For investors building a diversified income portfolio, CLAR’s geographic spread reduces single-market concentration risk that affects smaller Singapore-only industrial REITs.
Gearing Ratio & Interest Rate Sensitivity
CLAR’s gearing ratio of approximately 37.2% as at Q3 2026 places it comfortably below the MAS aggregate leverage limit of 50% (or 55% if the REIT’s interest coverage ratio exceeds 2.5x). With approximately SGD 4.3 billion in total borrowings on a SGD 17.3 billion portfolio, CLAR has an estimated SGD 2.2 billion in debt headroom to 45% gearing, providing meaningful acquisition firepower without compromising its investment-grade credit rating.
Approximately 80% of CLAR’s borrowings are on fixed-rate terms, with a weighted average debt maturity of approximately 3.5 years as at Q3 2026. The remaining 20% floating-rate borrowings have already benefitted from Fed rate cuts in 2026. As fixed-rate tranches mature and are refinanced in 2027 and 2028, the direction of medium-term interest rates will determine whether CLAR’s all-in borrowing cost can trend down from its FY2026 peak of approximately 3.6% toward 3.2–3.4% by end-FY2027. Interest Coverage Ratio (ICR) stands at approximately 3.6x — healthy and comfortably above the 2.5x threshold.
| Rate Scenario (All-In Cost) | Estimated Annual Interest | DPU Impact vs Base Case |
|---|---|---|
| Bear: 4.0% (+40bp vs base) | ~SGD 172M | −0.2 cents per unit |
| Base: 3.6% (current) | ~SGD 155M | — |
| Bull: 3.2% (−40bp vs base) | ~SGD 138M | +0.2 cents per unit |
Source: TKN estimates based on total borrowings of ~SGD 4.3B with ~20% floating-rate exposure transitioning to lower fixed rates on refinancing. For illustrative purposes only. Not financial advice.
CLAR vs Industrial REIT Peers
Comparing CLAR against its closest industrial REIT peers helps Singapore investors assess relative value at current price levels. CLAR’s premium to book (P/NAV of approximately 1.02x) reflects investor confidence in portfolio quality and management track record, while offering a slightly lower yield than smaller or higher-geared peers.
| REIT | Ticker | Market Cap | Fwd Yield | Gearing | Occupancy | P/NAV |
|---|---|---|---|---|---|---|
| CapitaLand Ascendas REIT | A17U | SGD 12.8B | 5.4–5.6% | 37.2% | 93.8% | 1.02x |
| Mapletree Industrial Trust | ME8U | SGD 6.9B | 5.6–5.9% | 38.6% | 91.2% | 1.05x |
| Mapletree Logistics Trust | M44U | SGD 7.1B | 5.8–6.1% | 40.1% | 96.2% | 0.89x |
| AIMS APAC REIT | O5RU | SGD 1.1B | 6.8–7.1% | 35.4% | 97.8% | 1.01x |
Source: SGX, Bloomberg consensus estimates (October 2026). P/NAV = Price-to-Net Asset Value. Forward yield based on FY2027F DPU consensus. Data is approximate and subject to revision.
Mapletree Logistics Trust (M44U) trading below NAV at 0.89x offers a higher yield but carries approximately 27% China AUM exposure, where logistics sector headwinds persist. For investors who want pure-play Singapore industrial exposure with higher yield, AIMS APAC REIT (O5RU) is an option, but with significantly smaller market cap and lower liquidity. For a broader view of how industrial REITs fit into a diversified S-REIT portfolio, see our comparison of the best S-REITs in Singapore 2026. For ETF-based industrial REIT exposure, our Singapore REIT ETF guide covers how a single fund can give you diversified REIT income.
Is CLAR a Buy, Hold, or Sell in 2027?
TKN Assessment: BUY or HOLD for long-term Singapore investors seeking a diversified industrial REIT with strong management, near-30-year track record, and improving DPU trajectory as rate cuts flow through in FY2027. CLAR’s defensively high portfolio occupancy (>93%), positive rental reversion in Singapore, investment-grade balance sheet with acquisition headroom, and adequate liquidity (average daily trading volume ~SGD 25–30M) make it a core S-REIT holding for most income investors.
Consider underweighting or monitoring carefully if you are concerned about: US suburban office occupancy risk (~12% of AUM in a normalising US office market); currency headwinds from AUD/USD weakness versus SGD (Australia and US assets contribute ~32% of AUM); a reversal of the rate-cut cycle which would increase refinancing costs on maturing debt; or premium valuation (P/NAV ~1.02x) that limits deep-value upside.
At a share price of approximately SGD 2.85–2.95 and a FY2027F DPU of approximately 16.1 cents, CLAR offers a forward yield of ~5.5%. While this is below the ~5.8–6.1% yield available from Mapletree Logistics Trust or AIMS APAC REIT, the premium is justified by CLAR’s superior portfolio diversification, larger float, and stronger balance sheet. For most Singapore investors building a retirement-oriented S-REIT portfolio, CLAR at current levels remains a core holding.
Singapore investors should note that CLAR (A17U) is included on the CPF Investment Scheme (CPFIS) approved list — you can purchase it using CPF-OA funds via CPF-approved brokers. For an overview of how REITs fit into a wider CPF strategy, see our guide on CPF investment strategy Singapore.
To purchase CLAR, Singapore investors can use Syfe (referral code: SRPRFFFCD) for simple fractional REIT access, Endowus (code: 2V343) for CPF/SRS-eligible fund investing, FSMOne (code: P0544985) for direct SGX trading, or IBKR for lower brokerage fees on larger positions.
Frequently Asked Questions
What is CapitaLand Ascendas REIT (CLAR) and how is it different from other S-REITs?
CapitaLand Ascendas REIT (SGX: A17U) is Asia-Pacific’s first and largest industrial REIT, holding over 220 properties across Singapore, Australia, the United States, and the UK/Europe. Unlike commercial or retail REITs, CLAR focuses on industrial assets — business parks, hi-tech manufacturing facilities, logistics centres, and data centre-adjacent campuses. This “new economy” focus gives CLAR structural demand tailwinds from digital supply chains and technology infrastructure, and lower volatility than retail or office REITs. As at October 2026, it is one of the top 10 largest REITs listed on the SGX by market capitalisation.
What is CapitaLand Ascendas REIT's expected DPU for FY2027?
Analyst consensus (as at October 2026) projects CLAR’s FY2027 DPU in the range of approximately 15.9–16.4 cents per unit, with a midpoint estimate of approximately 16.1 cents. This represents approximately 2–4% growth over FY2026’s estimated 15.6–15.9 cents per unit. The growth is underpinned by positive Singapore rental reversions (6–10%), interest cost savings from rate cuts, and potential DPU accretion from selective acquisitions. Estimates are subject to change and are not financial advice — always refer to CLAR’s official SGX announcements for confirmed distribution amounts and dates.
Is CapitaLand Ascendas REIT (A17U) eligible for CPF investment?
Yes. CapitaLand Ascendas REIT (A17U) is included on the CPF Investment Scheme (CPFIS) approved list, meaning Singapore investors can purchase A17U units using their CPF Ordinary Account (OA) funds, subject to the applicable CPFIS investment limits. CPFIS investments in REITs allow CPF members to potentially earn returns above the standard CPF OA interest rate of 2.5% per annum. However, REITs carry market risk and the investment value can fall below the amount invested. Consult the CPF Board’s official CPFIS approved investment list for the latest status before investing.
What is CLAR's gearing ratio and is it at risk?
CLAR’s gearing ratio stood at approximately 37.2% as at Q3 2026 (total borrowings of ~SGD 4.3 billion on ~SGD 17.3 billion AUM). This is comfortably below the MAS aggregate leverage limit of 50% and well below the 55% ceiling available to REITs with an Interest Coverage Ratio above 2.5x (CLAR’s ICR is approximately 3.6x). The gearing is not at risk under most scenarios, and CLAR retains approximately SGD 2.2 billion of debt headroom to a self-imposed 45% gearing ceiling — sufficient for meaningful acquisitions without raising equity. CLAR’s investment-grade credit rating also provides access to competitively priced debt in most market conditions.
Should I buy CLAR (A17U) or Mapletree Industrial Trust (ME8U) in 2027?
Both are quality large-cap industrial REITs, but they serve slightly different investor profiles. CLAR (A17U) offers greater geographic diversification (Singapore, Australia, US, UK/Europe) with a slightly lower forward yield (~5.5%) and higher AUM scale (~SGD 17.3B vs ~SGD 10B for MIT). Mapletree Industrial Trust (ME8U) has a higher data centre concentration (~50% of AUM including US data centres) and a slightly higher forward yield (~5.6–5.9%), but less geographic diversification. Neither is inherently “better” — the right choice depends on your preference for geographic spread vs sector concentration, and your yield vs safety trade-off. Consulting a licensed financial advisor before making any investment decision is recommended.
How do I buy CapitaLand Ascendas REIT (A17U) in Singapore?
Singapore investors can purchase A17U through a brokerage account connected to the Central Depository (CDP) or a custodian account. Popular platforms include FSMOne (code: P0544985) for regular savings plans and direct SGX trading, Syfe (code: SRPRFFFCD) for thematic REIT portfolios, Endowus (code: 2V343) for CPF/SRS investing via fund wrappers, and IBKR for lowest-cost direct SGX access at larger position sizes. A17U trades in board lots of 100 shares on the SGX. Settlement is in SGD. Dividends are distributed semi-annually.
Start Your S-REIT Journey
Compare CLAR against the broader S-REIT universe, or use our free retirement calculator to see how a 5.5% yield portfolio contributes to your passive income goals.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.