DBS has set its sights on the most ambitious target in its history: S$1 trillion in wealth assets under management (AUM) by 2030. Announced on 25 September 2026 alongside an expanded 18-year partnership with Swiss fintech firm Avaloq, this goal would double the bank’s current wealth footprint. For Singapore retail investors navigating a crowded field of robo-advisors, digital banks and wealth platforms, here is exactly what this means — and whether it changes anything for your portfolio.
DBS’s Trillion-Dollar Vision: What the Numbers Say
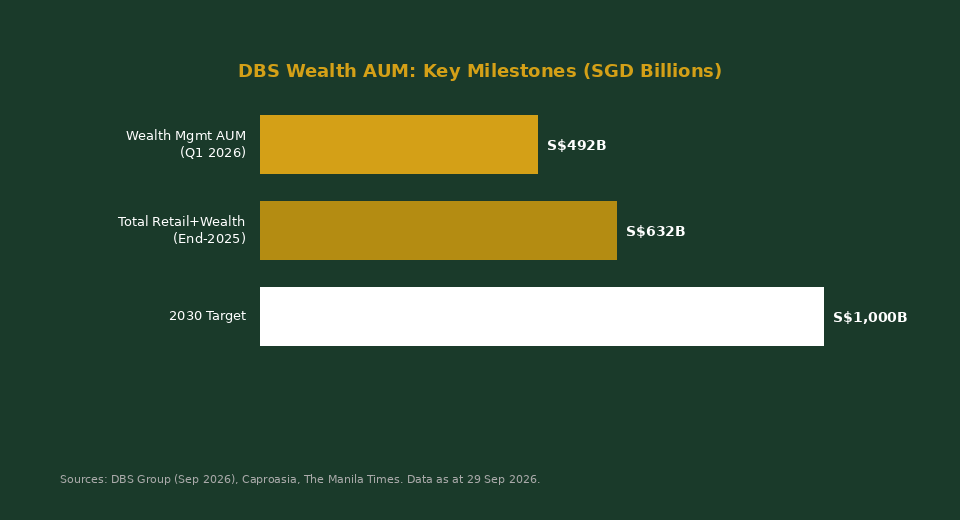
DBS currently manages approximately S$492 billion in wealth AUM as of Q1 2026 — a figure reported by industry publication Caproasia. When combined with its broader retail banking book, total customer assets across DBS’s retail and wealth segments reached S$632 billion at end-2025, according to The Manila Times. The S$1 trillion target therefore represents a doubling of the wealth management component within four years.
To get there, DBS is rolling out 18 new wealth centres across Asia and upgrading 36 existing ones — including a significant expansion of its Treasures Private Client (TPC) footprint in Singapore. The bank also reported that Treasures clients in Singapore grew by 50% year-on-year in H1 2026, suggesting the strategy is already gaining traction.
For broader context, DBS posted net profit of S$3.08 billion for Q2 2026 — up 9% year-on-year — driven in part by fee income from wealth management. You can read our earlier analysis in DBS Q2 2026 Results: What Investors Should Know.
The Avaloq Partnership: Technology at the Core
The strategic engine behind this expansion is DBS’s deepened tie-up with Avaloq, a Zurich-based banking software company owned by NEC Group. The two organisations have worked together for 18 years; the September 2026 expansion accelerates the deployment of Avaloq’s AI-powered wealth advisory tools across DBS’s Treasures and TPC segments.
The practical implication for customers: DBS is building the infrastructure to give every client — not just high-net-worth (HNW) customers — access to algorithmic investment guidance that was previously available only through human wealth advisers. The bank noted that 70% of DBS investors already have a dedicated wealth adviser, and that more than 40% of those without one say they want one. Avaloq’s technology is the mechanism for bridging that gap at scale.
This is where DBS is trying to compete with — and exceed — the offerings of fintechs like Endowus, Syfe, and StashAway, while layering in the credibility and distribution network that only a full-service bank can offer.
What This Means for Your Wealth Management Options
The practical question for most Singapore investors isn’t whether DBS hits S$1 trillion — it’s whether DBS’s offering is competitive enough to warrant moving assets there. The table below compares the key platforms on fees, CPF/SRS compatibility, and minimum investment:
| Platform | Management Fee (S$100k portfolio) | CPF OA / SRS | Minimum Investment |
|---|---|---|---|
| DBS digiPortfolio | 0.75% p.a. | No (cash only) | S$1,000 |
| Endowus | 0.60% p.a. (under S$200k tier) | Yes (CPF OA, SRS & cash) | S$1,000 |
| StashAway | 0.60% p.a. (S$50k–S$100k tier) | No (cash only) | No minimum |
| Syfe | 0.50% p.a. (S$20k–S$100k tier) | No (cash only) | No minimum |
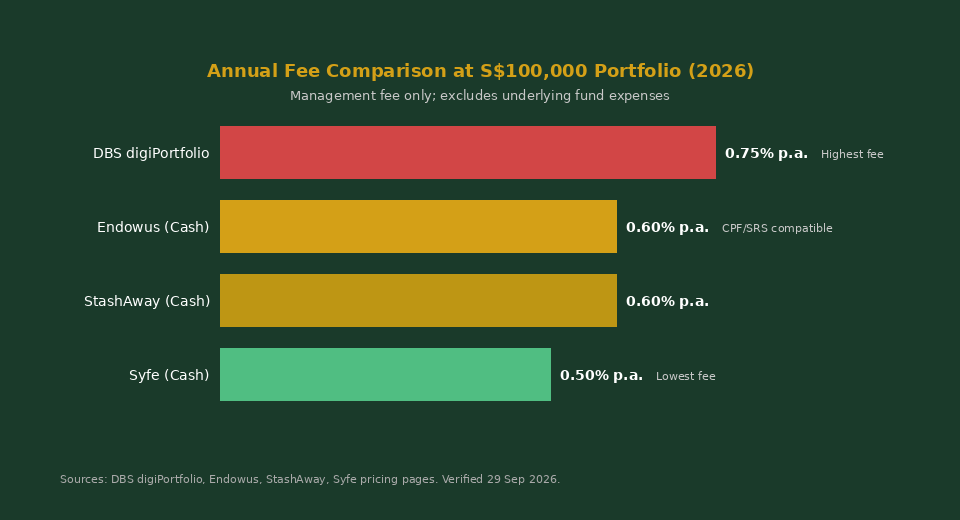
One clear disadvantage for DBS is that digiPortfolio does not support CPF Ordinary Account (OA) or SRS funds. For the many Singaporeans who want to put their CPF OA monies to work — particularly given that the OA floor rate of 2.5% may underperform a diversified equity allocation over the long run — Endowus remains the only major robo-advisor accepting CPF OA investments.
DBS’s Tiered Wealth Structure: Where Do You Fit?
DBS organises its wealth offering into three distinct tiers, each with different minimum balances and service levels:
- Treasures (S$350,000 minimum in total relationship balance): Dedicated Relationship Manager, priority banking, access to structured products and DBS CIO investment views. This tier saw 50% growth in Singapore in H1 2026.
- Treasures Private Client (TPC) (S$1.5 million minimum): Advanced planning services, family office-style solutions, exclusive investment opportunities.
- Private Bank (invitation-only, typically S$5 million+): Full discretionary portfolio management, philanthropy advisory, multi-generational estate planning.
For most retail investors — the core TKN reader — the Treasures tier is the target. Below S$350,000 in assets, clients are served through DBS’s standard banking channels with access to digiPortfolio and in-branch investment counters. There is also a S$50/month service fee if your total relationship balance falls below S$200,000, which is worth factoring into the total cost of banking with DBS.
If you’re building toward the Treasures threshold, our guide to Singapore T-bills and short-term instruments covers how to optimise your cash while you accumulate.
The CPF and SRS Angle: A Gap in DBS’s Offering
One of the most significant structural gaps in DBS’s retail wealth stack is its inability to accept CPF Ordinary Account (OA) funds through digiPortfolio. With Singapore’s CPF Special, Medisave, and Retirement Account (SMRA) floor rate held at 4% through end-2027, the urgency around CPF OA (at 2.5%) is arguably the most underappreciated retirement planning issue for Singapore’s middle class.
DBS does offer CPF Investment Scheme (CPFIS) access through its POSB banking platform — including unit trusts and Singapore ETFs — but this requires individual fund selection and is not managed via digiPortfolio. Investors who want a managed robo-advisory experience using CPF OA remain limited to Endowus.
For SRS investors, the story is similar. While DBS allows SRS funds to be invested in a range of products through its branch network and iWealth platform, digiPortfolio specifically does not accept SRS. Our comprehensive CPF investment guide covers all CPFIS-approved instruments and their risk ratings in detail.
How This Stacks Up Against Singapore’s Broader Investment Landscape
With Singapore’s core inflation running at 2.2% as of August 2026 and 6-month T-bill yields at approximately 1.92% (September 2026 auction), the real return from risk-free instruments is effectively zero or slightly negative. This is the environment in which DBS is pitching its S$1 trillion wealth story — one where investors need to take some risk to preserve purchasing power.
For S-REIT investors specifically, DBS’s expanded research capabilities and structured product access at the Treasures level could be compelling. DBS has historically been a leading voice on Singapore REIT research, and its wealth advisers are well-positioned to help clients build diversified S-REIT portfolios as part of a broader allocation strategy.
For the broader macro backdrop, the US Federal Reserve’s benchmark rate sits at 3.75–4.00% (post the September 16 meeting), which continues to keep Singapore dollar deposit rates at relatively attractive levels — but not attractive enough to make parking cash the optimal long-term strategy.
Bottom Line for SG Investors
DBS’s S$1 trillion target is more than a marketing headline — it signals a genuine structural shift in how Singapore’s largest bank views wealth management as a core growth engine. For investors with at least S$350,000 in liquid assets, the expanded Treasures proposition (more centres, AI-enhanced advisory, deeper product access) is worth a serious look, particularly if you already bank with DBS and value the consolidation of your financial relationship.
That said, DBS’s retail wealth proposition has real limitations for the majority of Singapore investors: the 0.75% digiPortfolio fee is the most expensive among the major robo-advisors, there is no CPF OA or SRS compatibility, and the enhanced services are gated behind a S$350,000 relationship threshold that excludes most retail participants.
Our view: DBS’s wealth expansion is good news for the industry — more competition and better technology will raise standards across the board. But for most TKN readers building wealth below the S$350,000 threshold, Endowus (for CPF/SRS), Syfe (for lowest fees), or a low-cost ETF portfolio via DBS’s own iWealth still represent better value than digiPortfolio. Keep watching this space: if DBS introduces CPF OA compatibility for digiPortfolio — which the technology could eventually support — the calculus changes significantly.
Frequently Asked Questions
What is DBS’s S$1 trillion wealth target and when is it due?
What is DBS digiPortfolio and how does it compare to other robo-advisors?
Can I invest CPF or SRS funds through DBS digiPortfolio?
What are the DBS Treasures and Treasures Private Client (TPC) minimum requirements?
What is Avaloq and why is it important for DBS’s wealth strategy?
How does Singapore’s current economic environment affect this strategy?
Is S-REIT investing available through DBS’s wealth platforms?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.