Endowus vs IBKR Singapore 2026: Managed Robo-Advisor or Self-Directed DIY Investing?
A side-by-side look at fees, CPF/SRS access and control — and which platform actually fits how you want to invest.
Endowus is a CPF, SRS and cash-eligible robo-advisor that builds and rebalances a diversified fund portfolio for you, charging 0.15%–0.60% a year. Interactive Brokers (IBKR) is a self-directed global broker with no CPF/SRS access but near-zero commissions on US-listed ETFs. Endowus suits hands-off investors who want their CPF and SRS working; IBKR suits DIY investors who want full control over what they buy and at what price.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Quick Answer: Which Should You Pick?
If you want your CPF Ordinary Account, CPF Special Account money (where still eligible) or SRS funds invested without opening a separate brokerage account, Endowus is the only one of the two that can touch that money at all — IBKR cannot accept CPF or SRS funds in any form. If you are investing cash only, want to pick individual ETFs or stocks, and are comfortable managing your own rebalancing, IBKR is materially cheaper once your portfolio moves past the low tens of thousands of dollars, because its commission on US-listed ETFs is effectively zero under IBKR Lite. Many Singapore investors in 2026 run both: Endowus for CPF/SRS, IBKR for cash.
Key Differences at a Glance
Endowus and IBKR are not really competing for the same job. Endowus is an advised, conflict-free wealth platform licensed by MAS (CMS Licence 101051) that builds a portfolio of institutional-class funds for you. IBKR is an execution-only global broker — it will not advise you on what to buy, but it will get you into almost any listed market in the world at a very low cost.
| Feature | Endowus | IBKR |
|---|---|---|
| Model | Managed, advised fund portfolios | Self-directed, execution-only brokerage |
| CPF OA/SA investing | Yes (CPFIS-approved) | No |
| SRS funds accepted | Yes | No |
| Annual fee (cash) | 0.15%–0.60% tiered (Endowus Fee) | No annual fee — commission per trade |
| US ETF/stock commission | N/A (fund-based, not direct stock trading) | US$0 under IBKR Lite |
| Rebalancing | Automatic, included in fee | Manual, you decide and execute |
| Market access | 400+ curated funds and portfolios | 150+ markets, direct stocks, ETFs, options, bonds |
| Minimum initial investment | S$1,000 | No minimum |
| Regulator | MAS, CMS Licence 101051 | MAS-licensed (Interactive Brokers Singapore Pte Ltd) |
Fees and Annual Cost Compared
Endowus charges what it calls the Endowus Fee — an all-in annual rate that covers advice, platform access, rebalancing and brokerage, with no separate sales charge. As at November 2026, cash invested in Endowus’s advised portfolios or multi-fund Fund Smart picks costs 0.60% a year below S$200,000, falling to 0.50% between S$200,000 and S$1 million, 0.35% up to S$5 million, and 0.25% above that. CPF OA/SA and SRS money is priced separately at a flat 0.40% for multi-fund portfolios (or 0.30% for a single Fund Smart fund), and short-term cash management sits at a flat 0.15% (Endowus pricing page, accessed November 2026).
IBKR has no annual management fee on a self-directed account. Under IBKR Lite, eligible investors trade US-listed stocks and ETFs commission-free; IBKR Pro users on US markets pay a small per-share rate (roughly US$0.0005–US$0.0035 per share, tiered by monthly volume) with a low per-order minimum. Singapore-listed stocks are commission-based, commonly cited around 0.08% of trade value with a S$2.50 minimum per order (SingSaver fee comparison, accessed November 2026) — always confirm the live rate on IBKR’s own Singapore commissions page before trading.
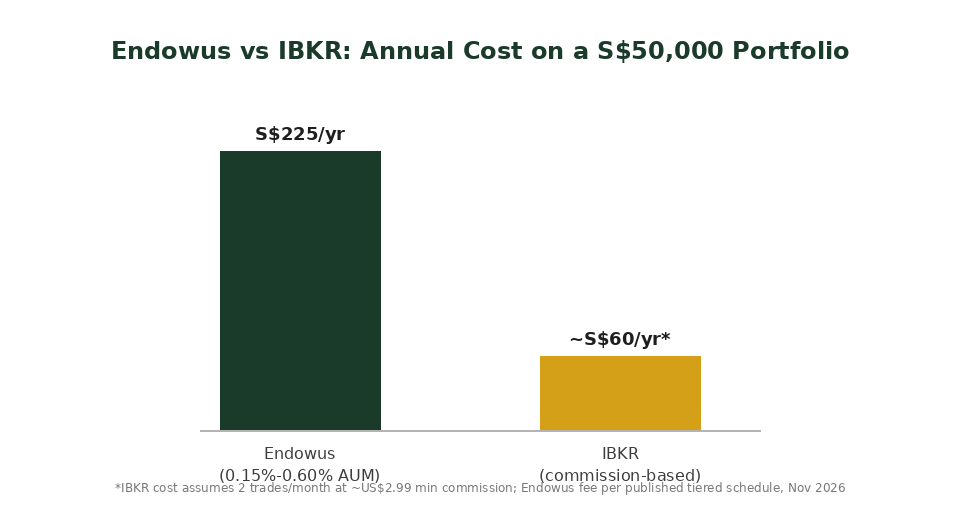
Worked example: on a S$50,000 portfolio invested for a year with minimal trading, Endowus’s blended access fee of roughly 0.45% works out to about S$225. An IBKR investor making two trades a month at IBKR’s roughly US$2.99 practical minimum per trade would pay in the order of S$60–S$80 a year in commissions — but that figure excludes the time cost of picking, sizing and rebalancing your own portfolio, which Endowus’s fee is paying for.
CPF, SRS and Cash Account Access
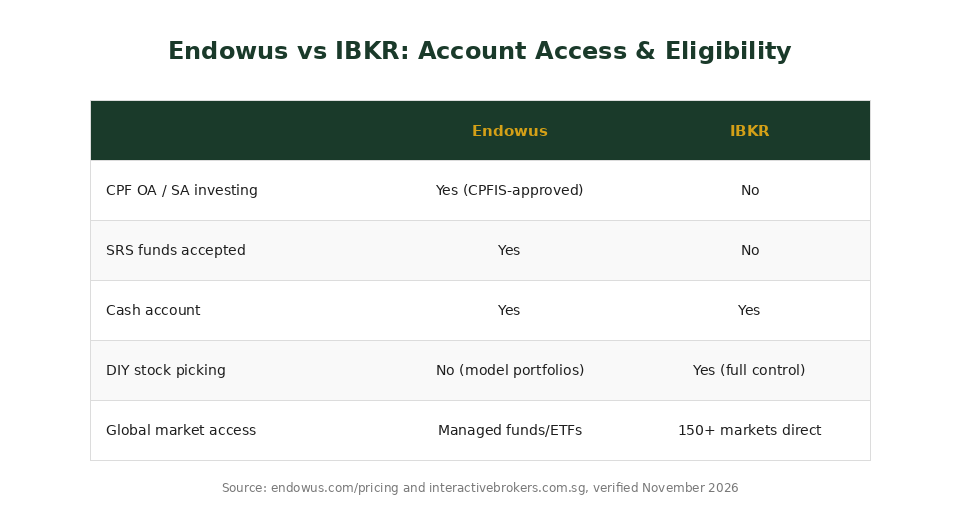
This is the single biggest structural difference between the two platforms, and it decides the question for most Singaporeans before cost even enters the picture. Endowus is one of a small number of CPFIS-approved platforms that can invest your CPF Ordinary Account and (where still eligible) Special Account money, plus your SRS contributions, directly into diversified fund portfolios — instead of leaving that money earning the CPF OA’s 2.5% floor or SRS’s near-zero default rate. IBKR has no CPFIS approval and cannot accept CPF or SRS funds in any form; everything on IBKR is cash money from your own bank account.
For SRS specifically, this matters at tax time too: Endowus lets you put your SRS contributions to work the same year you make them and still claim the SRS tax relief (capped at S$15,300 for Singapore Citizens and Permanent Residents), without needing to separately open and fund a brokerage account. An IBKR account simply isn’t part of that CPF/SRS conversation.
How Each Platform Actually Works
With Endowus, you answer a short risk-profiling questionnaire, choose a goal (General Investing, Cash Smart, CPF, SRS or Income), and Endowus’s investment office builds and auto-rebalances a diversified portfolio of institutional share-class funds on your behalf. You never pick individual holdings; you pick a goal and a risk level, and Endowus does the rest. Trailer fees that fund managers would normally pay the distributor are rebated 100% back to you, and there is no sales charge on any transaction.
With IBKR, you open a self-directed account, fund it by bank transfer, and place your own orders — stocks, ETFs, options, bonds, or futures, across more than 150 markets. There is no model portfolio and no automatic rebalancing; every decision, from asset allocation to when to buy and sell, is yours. IBKR’s Trader Workstation and mobile app give experienced investors far more control (limit orders, options strategies, margin, direct access to Singapore-listed S-REITs and ETFs on SGX) than a managed platform like Endowus ever will.
A Singapore investor building a CPF investment strategy who also wants to DIY their cash holdings commonly uses both: Endowus for the CPF/SRS side where only a CPFIS-approved platform will do, and IBKR for cash where direct market access and near-zero commissions matter more.
Who Should Pick Endowus, Who Should Pick IBKR
Endowus is the better fit if you want your CPF OA, SA or SRS money invested and don’t currently have another CPFIS-approved route; you’d rather pay a transparent annual fee than spend time picking and rebalancing a portfolio yourself; or you want institutional-class funds and 100% trailer fee cashback without opening multiple accounts.
IBKR is the better fit if you’re investing cash only and want the lowest possible cost on US-listed ETFs; you want to hold individual stocks, options, bonds or SGX-listed counters directly; or you’re comfortable doing your own research, sizing and rebalancing without an advisor layer. Readers comparing a similar trade-off for cash holdings specifically may also want our Syfe vs IBKR Singapore 2026 comparison, or our look at Endowus vs Trust Bank TrustInvest for a managed-vs-DIY comparison that stays entirely within the no-CPF/SRS cash lane.
Whichever you choose, run the numbers against your own Singapore retirement calculator projection before committing new money — fees matter less than whether the money is actually invested at all.
Frequently Asked Questions
Can I invest my CPF or SRS money with IBKR?
No. IBKR is not a CPFIS-approved platform and cannot accept CPF Ordinary Account, Special Account or SRS funds in any form. Only cash from your own bank account can be invested through IBKR. If you want to invest CPF or SRS money, Endowus (or another CPFIS-approved platform) is the only route.
Is Endowus or IBKR cheaper?
It depends on your portfolio size and how actively you trade. Endowus charges a flat 0.15%–0.60% a year depending on the amount and type of money invested, which is predictable but scales with your balance. IBKR has no annual fee and near-zero commission on US-listed ETFs under IBKR Lite, so for a buy-and-hold cash investor with a larger portfolio, IBKR is typically cheaper — but you give up the advice, rebalancing and CPF/SRS access that Endowus’s fee pays for.
Can I use both Endowus and IBKR at the same time?
Yes, and many Singapore investors do exactly this — using Endowus for CPF and SRS money (where it’s one of the few CPFIS-approved options) and IBKR for cash they want to invest directly in individual stocks, ETFs or other instruments. There’s no restriction on holding accounts with both.
Does Endowus let me pick my own stocks like IBKR does?
Not in the same way. Endowus’s advised portfolios (Flagship, Income, ESG, Cash Smart) are built and rebalanced for you. Its Fund Smart feature lets you choose from 400+ individual funds yourself, but this is still fund selection, not direct stock, ETF or options trading across global exchanges the way IBKR offers.
Is my money safe with Endowus or IBKR if the platform fails?
Both are regulated by the Monetary Authority of Singapore. Endowus holds client assets with custodians and is a CMS Licence holder (101051); underlying investments are not SDIC-insured but are typically ring-fenced from Endowus’s own balance sheet. IBKR Singapore is also MAS-licensed, and client securities and cash are segregated from IBKR’s own assets under SFA client money rules. Neither account type carries SDIC deposit insurance, since both are investment accounts rather than bank deposits.
Which is better for a complete investing beginner in Singapore?
Endowus is generally easier for a first-time investor: you answer a risk questionnaire, pick a goal, and the platform builds and maintains the portfolio for you with no need to understand order types, exchanges or rebalancing. IBKR’s power and low cost come with a steeper learning curve, since every allocation and trading decision is yours to make.
Ready to Put Your CPF, SRS or Cash to Work?
Whichever fits your investing style, open your account through our referral links below for sign-up perks.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.