Syfe Cash+ vs GXS Savings 2026: Guaranteed Fund Yield or SDIC-Insured Bank Rate?
A straight comparison of Syfe’s investment-based Cash+ portfolios against GXS Bank’s insured savings account — rates, risk, and which one actually fits your cash.
Syfe Cash+ pays up to 3.00% p.a. projected (Cash+ Enhanced) versus GXS Savings Account’s 2.00% p.a. top rate (Boost Pocket, 18-month lock-in) — but Syfe Cash+ is an uninsured investment product while GXS is a MAS-licensed bank account insured up to S$100,000 by SDIC. For a no-strings, zero-risk rate, GXS’s 1.20% p.a. Saving Pocket beats Syfe’s projected 1.70% p.a. Cash+ Flexi on safety, even though Syfe pays more on paper.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
Syfe Cash+ vs GXS at a Glance
What Is Syfe Cash+?
What Is the GXS Savings Account?
Rate Comparison 2026
SDIC Insurance: The Risk That Actually Matters
Which Should You Choose?
How to Open an Account
FAQ
Syfe Cash+ vs GXS Savings at a Glance
A Singapore saver parking S$20,000 in idle cash has two fundamentally different tools on offer here. Syfe Cash+ is a suite of managed investment portfolios — your money buys units in fixed deposits or short-duration bond funds that Syfe has negotiated on your behalf. GXS Savings Account is a bank deposit account, full stop, backed by a banking licence from the Monetary Authority of Singapore (MAS) and covered by the Singapore Deposit Insurance Corporation.
That distinction matters more than the headline rate. Here’s the comparison at a glance:
| Feature | Syfe Cash+ | GXS Savings Account |
|---|---|---|
| Product type | Managed investment portfolio | Bank deposit account |
| Regulator | MAS (Capital Markets Services Licence) | MAS (Digital Full Bank licence) |
| SDIC insured | No | Yes, up to S$100,000 |
| No-strings top rate | 1.70% p.a. (Cash+ Flexi, projected) | 1.20% p.a. (Saving Pocket, promo) |
| Maximum achievable rate | 3.00% p.a. (Cash+ Enhanced, projected) | 2.00% p.a. (Boost Pocket, 18-month) |
| Minimum / maximum funding | None | None (account cap applies, set in-app) |
| Management fee | 0% to 0.20% p.a. depending on portfolio | None |
Source: syfe.com/cash-management, gxs.com.sg/savings-account — as at November 2026.
What Is Syfe Cash+?
Syfe Cash+ isn’t one product — it’s three, and the differences between them explain most of the confusion around “the Syfe rate.” A Singapore investor choosing between the tiers is really choosing how much certainty they’re willing to give up for a higher number.
Cash+ Guaranteed
Cash+ Guaranteed locks your money into underlying bank fixed deposits for a fixed term — 3, 6 or 12 months in SGD, or 1, 3, 12 months in USD. According to the Syfe Cash+ Guaranteed page, the SGD rate as at the live fetch in late 2026 sits at 1.40% p.a. for 3 months, 1.50% p.a. for 6 months, and 1.65% p.a. for 12 months. The USD version pays considerably more — 3.75% to 4.30% p.a. — reflecting higher USD interest rates. Capital and returns are “guaranteed,” but Syfe is explicit that this guarantee is “subject to underlying bank risk,” and because it is an investment product rather than a deposit, SDIC coverage doesn’t apply. You also cannot withdraw before the term ends.
Cash+ Flexi
Cash+ Flexi has no lock-in and pays out daily, with a projected net return of 1.70% p.a. after fees (0.05% to 0.15% p.a. management fee) as at the fund manager’s 30 September 2026 yield estimate. It isn’t capital guaranteed — the underlying money market funds can lose value, even if that’s historically rare over short holding periods.
Cash+ Enhanced
The newest tier, Cash+ Enhanced, targets a projected 3.00% p.a. net of a 0.15% to 0.20% p.a. fee by holding short-duration bond funds with a higher yield-to-maturity than the Flexi tier’s money market funds. Same trade-off: no capital guarantee, no SDIC, daily liquidity.
None of the three tiers carry SDIC protection, because none of them are bank deposits. Syfe is upfront about this on its own comparison tables — a rare instance of a platform volunteering the caveat that usually gets buried in the fine print.
What Is the GXS Savings Account?
GXS Bank holds a full digital banking licence from MAS, which means the GXS Savings Account is a real bank deposit account, not a fund wrapper. According to GXS’s own savings account page, the account splits into three buckets:
Main Account
The default bucket pays 0.88% p.a., credited daily, with no salary crediting or spending requirement attached. It also earns instant cashback on linked GXS Debit Card transactions.
Saving Pockets
Up to eight Saving Pockets can be opened for specific goals. As at the current promotional period, Saving Pockets pay 1.20% p.a. with daily interest, no lock-in, no fees, and no hoops — withdraw anytime back to the Main Account with zero penalty.
Boost Pocket
Boost Pocket is where GXS’s top rate lives. You commit funds for a chosen tenure — 1, 3, 4, 8, 12 or 18 months — and earn a 0.88% p.a. base rate plus a bonus that scales with tenure: 0.13% at 1 month, 0.34% at 3 months, 0.52% at 4 months, 0.82% at 8 months, 0.87% at 12 months, and 1.12% at 18 months. That caps the total achievable Boost Pocket rate at 2.00% p.a. for the longest lock-in. Up to eight Boost Pockets can run concurrently, each with its own tenure.
Every dollar in a GXS Savings Account is insured up to S$100,000 per depositor by the Singapore Deposit Insurance Corporation (SDIC), the same scheme that protects deposits at DBS, OCBC and UOB.
Rate Comparison: Syfe Cash+ vs GXS Savings 2026
Lining up every tier side by side makes the shape of the trade-off clearer than any single headline number can.
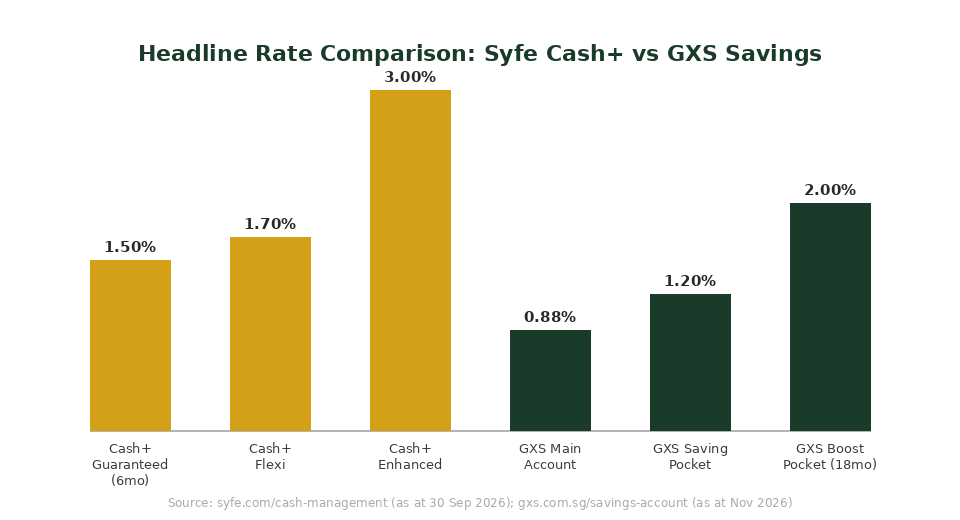
| Product | Rate (p.a.) | Lock-in | Capital guaranteed |
|---|---|---|---|
| Syfe Cash+ Guaranteed (6mo) | 1.50% | 6 months | Yes (bank risk) |
| Syfe Cash+ Flexi | 1.70% (projected) | None | No |
| Syfe Cash+ Enhanced | 3.00% (projected) | None | No |
| GXS Main Account | 0.88% | None | Yes (SDIC) |
| GXS Saving Pocket | 1.20% (promo) | None | Yes (SDIC) |
| GXS Boost Pocket (18mo) | 2.00% | 18 months | Yes (SDIC) |
Source: syfe.com/cash-management (projected returns as at 30 Sep 2026), gxs.com.sg/savings-account — as at November 2026.
On a S$20,000 balance, the dollar gap between GXS’s no-strings Saving Pocket (1.20%) and Syfe’s no-strings Cash+ Flexi (1.70% projected) works out to roughly S$100 a year — a modest premium for taking on fund risk instead of bank risk. The gap widens if you’re willing to lock in: Syfe Cash+ Enhanced’s 3.00% versus GXS Boost Pocket’s 2.00% (18-month) is about S$200 a year on the same balance, but Enhanced is the least protected tier on this entire list.
SDIC Insurance: The Risk Difference That Actually Matters
This is the section most comparison tables skip, and it’s the one that should drive your decision more than any rate column.
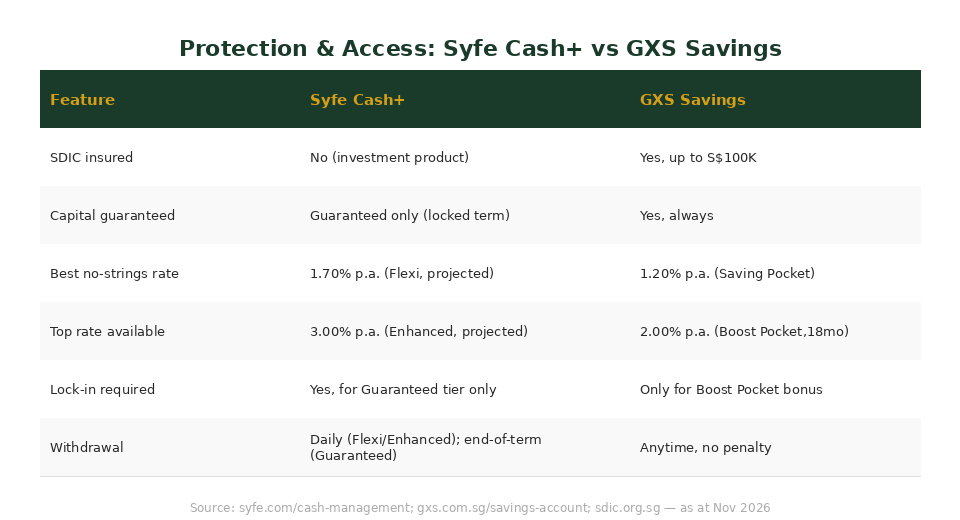
GXS Savings Account is a deposit at a MAS-licensed bank. If GXS Bank itself were to fail — a low-probability event under MAS supervision, but not a zero-probability one — the SDIC guarantees up to S$100,000 per depositor, paid out typically within seven working days. That protection applies to every bucket: Main Account, Saving Pockets, and Boost Pockets all count toward the same S$100,000 cap.
Syfe Cash+, across all three tiers, carries none of that. Even Cash+ Guaranteed — the tier marketed as “capital and returns guaranteed” — is explicit on Syfe’s own page that the guarantee is “subject to underlying bank risk” and that “as this is an investment product, SDIC coverage doesn’t apply.” In practice, Syfe diversifies Cash+ Guaranteed deposits across multiple MAS-regulated banking partners to reduce single-bank concentration risk, which is a sensible mitigant — but it is a risk-management technique, not a government-backed guarantee. Cash+ Flexi and Cash+ Enhanced go further: their underlying money market and bond funds can genuinely lose value, and Syfe does not claim otherwise.
None of this means Syfe Cash+ is unsafe — Syfe Pte. Ltd. is regulated by MAS under a Capital Markets Services Licence, and the underlying funds and deposits sit with established, regulated institutions. It means the two products sit in genuinely different risk categories, and a saver comparing “1.70% vs 1.20%” without factoring that in is comparing the wrong things.
Which Should You Choose?
There isn’t a single right answer — it depends on what the cash is for.
Choose GXS Savings Account if…
Your cash is a true emergency fund or short-term holding pot where capital preservation outranks yield. A Singapore investor keeping 3 to 6 months of expenses liquid has little reason to take on uninsured fund risk for an extra percentage point, and GXS’s Saving Pocket gives a genuinely no-strings 1.20% p.a. with same-bucket access and zero lock-in.
Choose Syfe Cash+ if…
You’re comfortable holding this money as an investment rather than a deposit, you’ve already got a separate SDIC-insured emergency buffer elsewhere (GXS, MariBank, or a traditional bank), and you want the extra yield on money you can afford to see fluctuate slightly, however briefly. Cash+ Enhanced’s 3.00% target and Cash+ Flexi’s daily liquidity make it a reasonable home for medium-term cash earmarked for, say, next year’s passive income reinvestment or a planned brokerage top-up.
Or run both
Plenty of Singapore savers do exactly this: GXS for the untouchable emergency layer (SDIC-insured, instant access), and Syfe Cash+ Flexi or Enhanced for the surplus cash that’s working toward a goal 6 to 18 months out. Spreading balances this way also means you’re never relying on a single institution for all your liquidity.
If you’re weighing GXS against other digital banks too, the GXS vs MariBank vs Trust Bank 2026 comparison breaks down how the three stack up on headline versus realistically achievable rates. And if Syfe’s cash tools specifically are your focus, see how Cash+ stacks up against a flat-rate digital bank in our Syfe Cash+ vs MariBank 2026 piece, or against Trust Bank’s scoop-based bonus system in Syfe vs Trust Bank 2026.
How to Open an Account
Both platforms can be set up entirely on your phone, with Singpass making verification almost instant.
Opening Syfe Cash+
Download the Syfe app or sign up on syfe.com, verify with Singpass, and select a Cash+ tier (Guaranteed, Flexi or Enhanced). There’s no minimum funding for any tier. New users signing up through the Syfe referral code and sign-up bonus page can pick up an additional welcome reward on top of whichever Cash+ portfolio they choose.
Opening a GXS Savings Account
Download the GXS app, verify with Singpass (typically under five minutes), and your Main Account is active immediately. From there you can create Saving Pockets or Boost Pockets directly in the app, and link your CPF investment strategy savings calculator against your GXS balance to see how your emergency fund stacks up against your long-term targets. For a broader view of where this cash fits into your overall plan, run the numbers through our Singapore retirement calculator.
Frequently Asked Questions
Is Syfe Cash+ or GXS Savings Account safer?
What is the highest rate I can get with GXS right now?
What is the highest rate I can get with Syfe Cash+?
Can I lose money with Syfe Cash+?
Does GXS charge any fees on its Savings Account?
Can I hold both Syfe Cash+ and a GXS Savings Account at the same time?
Is CPF or SRS money accepted by either platform?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.