SGD Fixed Deposit Rate Singapore 2026: Best Rate for Your Deposit Size
Independently verified against published bank data — October 2026
The best SGD fixed deposit rate in Singapore in October 2026 is 2.10% p.a. from RHB Bank for 12 months (minimum S$20,000). HL Bank follows at 2.05% p.a. (minimum S$10,000 via HLB Connect). For smaller deposits under S$10,000, Citibank offers 2.00% p.a. for 6 months from S$5,000, while GXS Boost Pocket locks in 1.75% p.a. for 12 months with just S$100 minimum. This guide ranks the top SGD FD rates at each deposit tier — from S$100 up to S$100,000.
Not financial advice. All figures are for educational reference only. Data verified as at 21 October 2026 against GrowBeanSprout (published 15 October 2026). Fixed deposit rates change frequently — always confirm the latest rate with your bank before placing funds.
Table of Contents
- Best SGD FD Rates — October 2026 Rankings
- Best Rate by Deposit Size (Tier Breakdown)
- Small Deposits: Under S$10,000
- Mid-Size Deposits: S$10,000 – S$49,999
- Large Deposits: S$50,000+
- How Much Will You Earn? Interest Comparison
- Digital Banks vs Traditional Banks
- Is Your Fixed Deposit Safe? SDIC Coverage
- Frequently Asked Questions
Best SGD Fixed Deposit Rates — October 2026
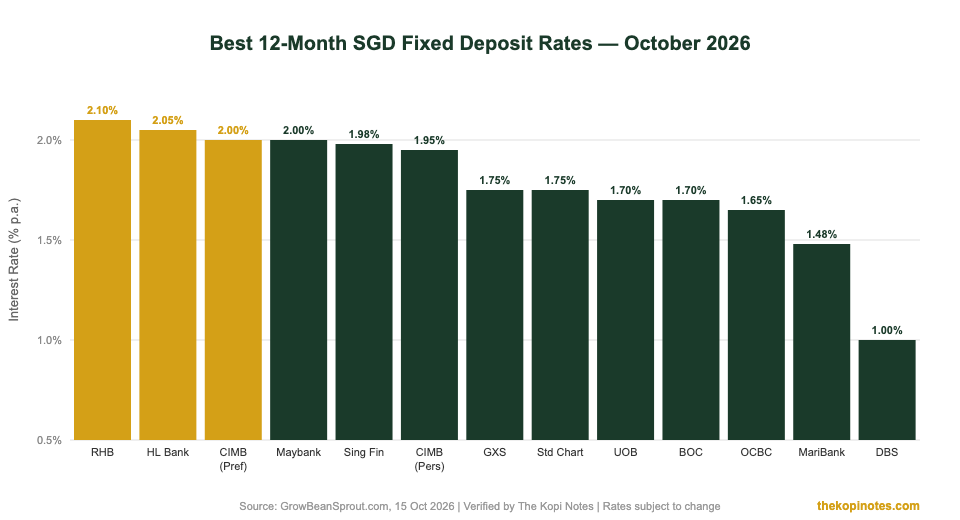
The SGD fixed deposit landscape in October 2026 is anchored by a cluster of foreign and regional banks offering 12-month rates between 1.95% and 2.10% p.a. — well above the local bank incumbents like DBS (1.00%) and OCBC (1.65%). If you have not compared rates recently, you may be leaving hundreds of dollars on the table each year.
The table below ranks all major Singapore fixed deposit providers by their best 12-month SGD rate:
| Bank | 12-Month Rate | Min. Deposit | Key Condition |
|---|---|---|---|
| RHB Bank | 2.10% p.a. | S$20,000 | Standard FD; no fresh funds required |
| HL Bank (HLB Connect) | 2.05% p.a. | S$10,000 | Online placement via HLB Connect app |
| CIMB (Preferred) | 2.00% p.a. | S$10,000 | Requires CIMB Preferred account |
| Maybank | 2.00% p.a. | S$20,000 | Standalone FD |
| Singapura Finance (Vivid) | 1.98% p.a. | S$10,000 | Vivid account required |
| CIMB (Personal) | 1.95% p.a. | S$10,000 | Standard account |
| GXS Boost Pocket | 1.75% p.a. | S$100 | 12-month lock-in; digital bank |
| Standard Chartered | 1.75% p.a. | S$25,000 | Fresh funds required |
| SBI Singapore | 1.75% p.a. | S$50,000 | — |
| UOB | 1.70% p.a. | S$10,000 | Fresh funds; promo until 31 Oct 2026 |
| Bank of China (Mobile) | 1.70% p.a. | S$500 | Mobile app placement; tiered rates |
| OCBC | 1.65% p.a. | S$20,000 | Online placement |
| MariBank | 1.48% p.a. | S$100 | Digital FD; no lock-in penalty waiver |
| HSBC | 1.30% p.a. | S$30,000 | 12 months (6-month rate: 1.80%) |
| DBS / POSB | 1.00% p.a. | S$1,000 | Drops to ~0.05% at S$20,000+ |
Source: GrowBeanSprout.com, 15 October 2026. Rates are indicative and subject to change — verify with your bank before placing funds.
Best SGD FD Rate by Deposit Size
Unlike most rate roundups that lead with a single “best” figure, this guide breaks the market down by how much you actually have to invest. A 2.10% rate from RHB is meaningless if you only have S$5,000 — you cannot meet the S$20,000 minimum. Here is the tier-by-tier winner:
| Deposit Size | Best Option | Rate | Tenor | Why It Wins |
|---|---|---|---|---|
| S$100 – S$999 | GXS Boost Pocket | 1.75% p.a. | 12 months | No meaningful minimum; best digital rate for small amounts |
| S$1,000 – S$4,999 | Bank of China (Mobile) | 1.70% p.a. | 12 months | Accessible via mobile app from S$500; competitive for this tier |
| S$5,000 – S$9,999 | Citibank (6 months) | 2.00% p.a. | 6 months | Best short-tenor rate in this range for new funds |
| S$10,000 – S$19,999 | HL Bank (HLB Connect) | 2.05% p.a. | 12 months | Top 12-month rate accessible from S$10,000 |
| S$20,000 – S$49,999 | RHB Bank | 2.10% p.a. | 12 months | Highest 12-month rate; available from S$20,000 |
| S$50,000+ | RHB Bank | 2.10% p.a. | 12 months | Still tops the table; also consider SBI (1.75%) or HSBC 6m (1.80%) |
Source: GrowBeanSprout.com, 15 October 2026. Citibank 6-month rate for new funds. All 12-month rates are per annum.
A key observation from the table: for deposits under S$10,000, your options narrow significantly. Most of the headline rates (2.00% and above) require at least S$10,000. If you have less than that, digital banks like GXS Bank Boost Pocket and MariBank fill the gap with competitive rates from as little as S$100. See our full guide to digital banks in Singapore for a deeper comparison.
Small Deposits (Under S$10,000): Where to Park Your Cash
Under S$1,000 — GXS Boost Pocket Leads
For truly small amounts, the traditional fixed deposit market offers little: DBS minimum is S$1,000 and most regional banks start at S$5,000–S$10,000. Digital banks step in here.
GXS Boost Pocket stands out with 1.75% p.a. for a 12-month commitment, starting from S$100. Technically it is a locked savings bucket within GXS Bank rather than a classic fixed deposit, but the mechanics are the same: you lock in for 12 months and earn a guaranteed rate. Note that GXS Bank referral code YONG477 may provide a sign-up bonus — check the GXS app for current offers.
MariBank FD offers a proper fixed deposit from S$100 at 1.48% p.a. for 12 months — lower than GXS but a genuine MAS-regulated FD product. MariBank referral code 2DCT80WQ is available if you are signing up new. For the full picture on MariBank, see our broader guide to Singapore Savings Bonds if you want a higher-liquidity alternative to a fixed deposit.
S$1,000 – S$4,999 — Bank of China (Mobile) Is Your Best Bet
Once you pass S$1,000, Bank of China’s mobile banking FD becomes the strongest option in this range at 1.70% p.a. for 12 months, with a minimum of S$500. Traditional banks like DBS offer only 1.00% p.a. for deposits below S$20,000.
If your goal is maximum returns and you do not need the guarantee of a FD structure, consider checking current Singapore Savings Bond rates — these offer comparable yields with full government backing and no lock-in penalty.
S$5,000 – S$9,999 — Citibank’s 6-Month Rate Punches Above Its Weight
For deposits in the S$5,000 to S$9,999 range, Citibank’s 6-month FD rate of 2.00% p.a. (for new funds) is the standout option — it is the only rate in this deposit tier that breaks the 2.00% barrier. The catch: it is a 6-month tenor, and the new funds condition means money already in Citibank does not qualify.
If you prefer 12 months, BOC mobile at 1.70% p.a. remains the leading option in this tier.
Mid-Size Deposits (S$10,000 – S$49,999): Where the Best Rates Live
This is where the real competition happens. Once you cross S$10,000, a range of foreign and regional banks compete aggressively for your deposit, offering rates two to three times the DBS rate.
S$10,000 – S$19,999 — HL Bank via HLB Connect Wins at 2.05%
HL Bank (Hong Leong Bank, a Malaysian bank with a Singapore branch) offers 2.05% p.a. for 12-month SGD fixed deposits placed through its HLB Connect mobile app, with a S$10,000 minimum. This is the single best 12-month rate available at the S$10,000 tier as at October 2026.
Runner-up: CIMB (Preferred) at 2.00% p.a. requires a CIMB Preferred account. If you already bank with CIMB personally, the standard 1.95% p.a. is still highly competitive. Singapura Finance’s Vivid account offers 1.98% p.a. — a close second if you already hold a Vivid account.
S$20,000 – S$49,999 — RHB Bank Takes the Top Spot at 2.10%
RHB Bank offers the highest 12-month SGD fixed deposit rate in Singapore at 2.10% p.a. for deposits of S$20,000 and above. One key advantage over most competitors: RHB does not require “fresh funds” — existing savings and rollovers from expiring FDs are eligible. A S$50,000 deposit at RHB earns S$1,050 in annual interest — compared to just S$500 at DBS (1.00%).
Maybank is a strong alternative at 2.00% p.a. (min S$20,000 standalone FD). Standard Chartered offers 1.75% p.a. (fresh funds, min S$25,000) — competitive but below RHB and Maybank for this tier. Also consider Singapore T-bills for shorter lock-ins — recent auction cut-off yields have tracked close to FD rates.
Large Deposits (S$50,000 and Above): Top Options
For deposits above S$50,000, RHB’s 2.10% p.a. remains the headline rate for 12 months. SBI Singapore enters at this tier with a competitive 1.75% p.a. for 12 months (minimum S$50,000).
HSBC is worth noting: while its 12-month rate (1.30% p.a.) is relatively low, the 6-month rate of 1.80% p.a. (minimum S$30,000) beats many 12-month options. If you need liquidity by mid-2027 and want to keep options open, HSBC’s 6-month product is worth comparing.
One important caveat for large deposits: SDIC insurance covers up to S$100,000 per depositor per institution. If your total deposit (including other accounts at the same bank) exceeds S$100,000, consider splitting across two MAS-licensed institutions rather than placing everything in one bank. See the SDIC section below for details.
How Much Will You Actually Earn?
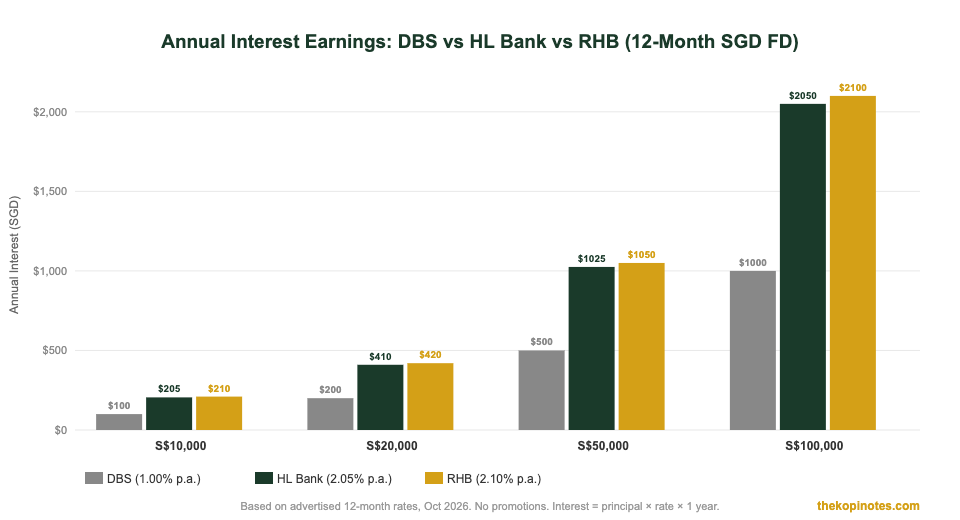
Here is a concrete look at annual interest earnings at four deposit sizes, comparing the top-rate options against DBS (the default for many Singaporeans):
| Deposit | DBS 1.00% (12m) | HL Bank 2.05% (12m) | RHB 2.10% (12m) | Extra vs DBS (Best Rate) |
|---|---|---|---|---|
| S$10,000 | S$100 | S$205 | N/A (min S$20k) | +S$105 vs DBS (HL Bank) |
| S$20,000 | S$200 | S$410 | S$420 | +S$220 vs DBS (RHB) |
| S$50,000 | S$500 | S$1,025 | S$1,050 | +S$550 vs DBS (RHB) |
| S$100,000 | S$1,000* | S$2,050 | S$2,100 | +S$1,100 vs DBS (RHB) |
*DBS rate drops to ~0.05% p.a. at S$20,000+ — actual interest on S$100,000 at DBS would be far lower (~S$50). Figures assume the best available rate for each scenario. All interest before tax; Singapore has no withholding tax on bank interest for residents.
Digital Banks vs Traditional Banks for SGD Fixed Deposits
In October 2026, MAS-licensed digital banks are not the rate leaders for large deposits — they are access leaders for small savers. Here is how they compare:
Digital banks shine when: you have under S$10,000 to lock away, you want no-fuss app-based placement, or you prefer a bank with a low minimum deposit. GXS Boost Pocket at 1.75% p.a. (from S$100) and MariBank FD at 1.48% p.a. (from S$100) both beat DBS and OCBC for small amounts. Trust Bank currently focuses on its savings product (no dedicated fixed deposit), so for locked-in FD returns, GXS and MariBank are the main digital choices.
Traditional (foreign/regional) banks win for larger deposits: RHB at 2.10% and HL Bank at 2.05% require S$20,000 and S$10,000 respectively, which is where they pull significantly ahead of digital banks.
Note that all three major digital banks — MariBank, GXS, and Trust Bank — are SDIC members, offering the same S$100,000 per-depositor protection as traditional banks. If you are exploring digital bank products more broadly, our passive income Singapore 2026 guide compares fixed deposits alongside other income options.
Is Your Fixed Deposit Safe? SDIC Coverage Explained
Every bank mentioned in this guide is a full bank or finance company licensed by the Monetary Authority of Singapore (MAS) and a member of the Singapore Deposit Insurance Corporation (SDIC). Your SGD fixed deposit is protected up to S$100,000 per depositor per institution in the unlikely event the bank fails.
DBS and POSB are the same institution for SDIC purposes. If you have a savings account at DBS and an FD at POSB, your total protection is S$100,000 combined — not S$100,000 each.
For deposits above S$100,000, consider spreading across two or more SDIC-member institutions. A S$200,000 deposit at a single bank means S$100,000 is uninsured. Splitting it between RHB (2.10%) and HL Bank (2.05%) keeps every dollar insured while maintaining competitive rates.
Joint accounts are treated as having equal shares per depositor — so a joint account with S$200,000 would give each holder S$100,000 of coverage, fully protected.
For a broader comparison of where to park your cash in Singapore — including higher-liquidity options — our Singapore Savings Bonds guide and Singapore T-bills 2026 guide are worth reading alongside this one.
Frequently Asked Questions
What is the best SGD fixed deposit rate in Singapore right now?
As of October 2026, the best 12-month SGD fixed deposit rate is 2.10% p.a. from RHB Bank (minimum S$20,000, no fresh funds requirement). HL Bank offers the next-best rate at 2.05% p.a. for deposits of S$10,000 and above via the HLB Connect app. For deposits under S$10,000, Citibank offers 2.00% p.a. for a 6-month tenor (new funds, minimum S$5,000), while GXS Boost Pocket offers 1.75% p.a. for 12 months from just S$100.
Which bank gives the best fixed deposit rate for S$10,000?
HL Bank (Hong Leong Bank Singapore) offers the best 12-month rate for S$10,000 deposits at 2.05% p.a. via its HLB Connect mobile app. CIMB (Preferred) offers 2.00% p.a. and Singapura Finance Vivid account offers 1.98% p.a. — both also require S$10,000 minimum. CIMB Personal (standard account) offers 1.95% p.a. for 12 months. These compare very favourably to DBS, which pays only 1.00% p.a. for the same tenor and deposit amount.
Are fixed deposits in Singapore safe?
Yes. All banks offering SGD fixed deposits in Singapore must be licensed by the Monetary Authority of Singapore (MAS) and are members of the Singapore Deposit Insurance Corporation (SDIC). The SDIC protects your deposits up to S$100,000 per depositor per institution. This coverage applies to both traditional banks (like DBS, OCBC, RHB) and digital banks (like GXS, MariBank, Trust Bank). For deposits above S$100,000, consider splitting across institutions to keep every dollar within the insured limit.
How does GXS Boost Pocket compare to a traditional fixed deposit?
GXS Boost Pocket is technically a locked savings pocket within the GXS Bank savings account, not a traditional fixed deposit product. However, it works similarly: you commit funds for a fixed period (12 months) and earn a guaranteed rate (1.75% p.a. as at October 2026). The main differences are (1) the entry barrier is just S$100 — far lower than most traditional FDs, and (2) GXS is a digital bank (MAS-licensed full bank) with no physical branches. The 1.75% rate beats all traditional banks with equivalent minimums, making it an excellent choice for small-to-medium savers.
Should I choose a 6-month or 12-month fixed deposit?
The choice depends on your liquidity needs and rate expectations. In October 2026, the general pattern is that 12-month rates are higher than 6-month rates for the same bank — except at Citibank (6-month: 2.00% beats its 12-month) and HSBC (6-month: 1.80% vs 12-month: 1.30%). If you need funds within 6 months, a 6-month FD makes sense. If interest rates are expected to fall, locking in for 12 months secures today’s rate for longer. If rates are expected to rise, a shorter tenor lets you reinvest at a higher rate sooner.
Can I place SGD fixed deposits at multiple banks to maximize returns?
Yes — and for deposits above S$100,000, it is advisable for SDIC coverage reasons. For example, you could place S$20,000 at RHB (2.10%), S$10,000 at HL Bank (2.05%), and S$5,000 with Citibank for 6 months at 2.00% — each at the most competitive rate for that amount. The main inconvenience is managing multiple banking relationships. Some banks (like CIMB and HL Bank) allow fully online placement, making the process manageable without visiting a branch.
What conditions typically apply to the best fixed deposit rates?
Most promotional FD rates in Singapore come with one or more conditions: (1) Fresh funds — money must be newly deposited and not previously held at the bank (common at UOB, Standard Chartered, Citibank — but notably NOT required at RHB); (2) Minimum deposit — amounts from S$100 (digital banks) to S$50,000 (SBI); (3) Account type — some rates require a premium account (e.g. CIMB Preferred, Singapura Finance Vivid); (4) Online placement — higher digital rates require mobile/internet banking (e.g. HL Bank’s 2.05% via HLB Connect). Always read the terms before placing funds.
Bottom Line: Which SGD Fixed Deposit Should You Open?
The answer is mostly about your deposit size. For S$20,000 or more, RHB at 2.10% p.a. leads all comers for a 12-month SGD FD — and unlike most competitors, it does not require fresh funds. From S$10,000, HL Bank’s 2.05% p.a. via HLB Connect is the target to beat. For smaller amounts, GXS Boost Pocket at 1.75% p.a. from just S$100 is the standout digital option. Whatever you choose, sticking with DBS or OCBC by default means leaving significant interest income on the table in the current rate environment.
Rates last updated: 21 October 2026. Always verify the latest rate directly with your bank or via the bank’s official app before placing funds.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.