TL;DR — CPF Withdrawal at 55: Key Facts
- What happens at 55: Your Special Account (SA) closes and transfers into a new Retirement Account (RA), topped up by your Ordinary Account (OA) if needed — up to the required retirement sum.
- No property pledge: You must retain the Full Retirement Sum (FRS: S$220,400 in 2026) in your RA. Anything above that is yours to withdraw.
- With property pledge: You only need to retain the Basic Retirement Sum (BRS: S$110,200 in 2026), freeing up an extra S$110,200 to withdraw.
- Minimum guarantee: The first S$5,000 in your OA is always withdrawable, even if your RA has not met the retirement sum.
- What stays in RA: Earns at least 4% p.a., with extra interest up to 6% on the first S$30,000 for members aged 55+. Converts into CPF LIFE income at 65.
- Deferring payouts to 70: Increases your monthly CPF LIFE payout by approximately 6% for each year of deferral.
- Tax: CPF withdrawal lump sums are not taxable in Singapore.
Turning 55 is one of the most consequential CPF milestones you will hit. For the first time, a portion of your CPF savings becomes accessible — but the rules governing how much you can take out, and what you must leave behind, are not always intuitive.
This guide explains the complete 2026 framework: how the Retirement Account is formed, the three retirement sums that set your withdrawal ceiling, the property pledge strategy that can more than double your accessible cash, and a worked example in Singapore dollars. It also covers what happens to the money you leave in CPF — because that decision has a compound return attached to it.
Note: The figures in this article use the 2026 CPF retirement sums, which took effect on 1 January 2026. All data is as at October 2026. This article is informational and does not constitute financial advice.
What Happens to Your CPF Accounts at 55
On or shortly after your 55th birthday, CPF Board makes three automatic moves.
1. Your Special Account closes. From 1 January 2025, the SA is closed for all members who turn 55. This is a permanent change. The interest rate advantage of the SA — 4% per year — does not disappear; it simply moves with your savings into the Retirement Account, which earns the same 4% floor rate.
2. A Retirement Account is created. Your SA balance transfers into the new RA first. If your SA balance alone is enough to meet the required retirement sum (the FRS, or BRS if you have a property pledge), the RA is funded and any remaining SA amount moves to OA. If the SA is not sufficient, your OA is used to top up the RA to the required sum.
3. The surplus becomes withdrawable. Whatever remains in your OA above the retirement sum top-up requirement — plus a guaranteed minimum of S$5,000 — can be withdrawn at any time from age 55 onward. There is no deadline to withdraw; the money simply sits in your OA at 2.5% per year until you claim it.
The critical question, then, is: what is the required retirement sum?
The Three Retirement Sums in 2026
CPF Board sets three tiers of retirement sum each year. These figures are reviewed annually and increase by approximately 3.5% per year, in line with long-term wage growth assumptions. For members who turn 55 in 2026, the applicable sums are:
| Retirement Sum | 2026 Amount | What it means | Est. CPF LIFE payout (age 65) |
|---|---|---|---|
| Basic Retirement Sum (BRS) | S$110,200 | Minimum sum if you own and pledge a property whose lease covers until age 95 | ~S$900–S$1,000/month |
| Full Retirement Sum (FRS) | S$220,400 | Standard minimum sum (= 2× BRS); required if you do not pledge a property | ~S$1,600–S$1,900/month |
| Enhanced Retirement Sum (ERS) | S$440,800 | Voluntary top-up ceiling (= 4× BRS since 2025); maximises CPF LIFE income | ~S$3,300–S$3,900/month |
The ERS became 4× BRS (instead of 3× BRS) from 2025, as part of CPF changes announced in Budget 2024. You cannot be required to set aside ERS — it is an opt-in ceiling. The CPF LIFE payouts shown are estimates for the Standard Plan at age 65. For a personalised estimate, use the retirement planning calculator.
For a deeper breakdown of how BRS, FRS and ERS are calculated and how they change year to year, see our CPF Retirement Sum 2026 guide.
How Much Can You Withdraw? The Formula
The withdrawal formula is simpler than it looks:
(Minimum S$5,000 from OA, regardless of retirement sum status)
The “required retirement sum” is either the FRS (S$220,400) if you have no property pledge, or the BRS (S$110,200) if you do. “Total CPF balance” means the combined value of your OA and SA at the point of computation — your MA is separate, governed by the Basic Healthcare Sum (BHS).
The Property Pledge: Halving Your Required Sum
The property pledge is one of the most significant levers available to CPF members at 55. By pledging your property to CPF Board, you reduce the retirement sum you must retain in your RA from FRS (S$220,400) to BRS (S$110,200). The difference — S$110,200 — becomes immediately withdrawable cash.
Who can pledge? You must own a residential property in Singapore (HDB flat or private property) whose remaining lease covers you to at least age 95. For most HDB flat owners, this is automatic if you bought the flat before a certain age. CPF Board checks lease coverage at computation.
What does pledging involve? You do not sell or transfer ownership. A pledge is a written undertaking that when the property is eventually sold, the RA shortfall (the difference between BRS set aside and FRS) will be refunded to CPF from sale proceeds — before you receive cash. If you die before selling, the shortfall is deducted from your estate.
Can you undo the pledge? Yes, with conditions. If your RA later grows to exceed FRS (through CPF LIFE interest credits and voluntary top-ups), CPF Board may release the pledge automatically. You can also top up the RA to FRS and have the pledge released.
The property pledge is discussed further on TKN’s CPF withdrawal at 55 glossary page and the CPF age-55 lump-sum withdrawal guide.
Worked Example: Mr Tan’s Withdrawal at 55
Meet Mr Tan, a 55-year-old Singaporean Citizen turning 55 in 2026. His CPF balances on computation day are:
- Ordinary Account (OA): S$120,000
- Special Account (SA): S$150,000
- Total (excl. MA): S$270,000
He owns a 3-room HDB flat. We look at two scenarios.
| Step | No property pledge (FRS) | With property pledge (BRS) |
|---|---|---|
| 1. Reserve from OA (always withdrawable) | S$5,000 | S$5,000 |
| 2. SA transfers to RA | S$150,000 → RA | S$110,200 → RA; S$39,800 → OA |
| 3. OA top-up to reach required sum | S$70,400 from OA → RA | None needed (RA already at BRS) |
| 4. RA balance (locked until 65) | S$220,400 | S$110,200 |
| 5. OA remaining | S$44,600 | S$154,800 (incl. S$39,800 from SA) |
| Total withdrawable (incl. S$5,000 reserve) | S$49,600 | S$159,800 |
By pledging his HDB flat, Mr Tan can withdraw an additional S$110,200 — the exact difference between FRS and BRS. To calculate your own withdrawable amount, use TKN’s CPF withdrawal at 55 calculator.
The S$5,000 Minimum Guarantee
If your total CPF savings (OA + SA) are below the required retirement sum, you might assume you cannot withdraw anything at 55. That is partially correct — but CPF Board carves out a guaranteed minimum of S$5,000 from your OA that is always accessible at 55, regardless of your RA’s funding status.
In practice: if your total CPF balance is S$150,000 (below FRS of S$220,400, no property pledge), your entire balance goes to fund your RA — but S$5,000 of your OA is set aside first and is available to withdraw. The S$5,000 ensures that members at 55 are never completely locked out of their own savings.
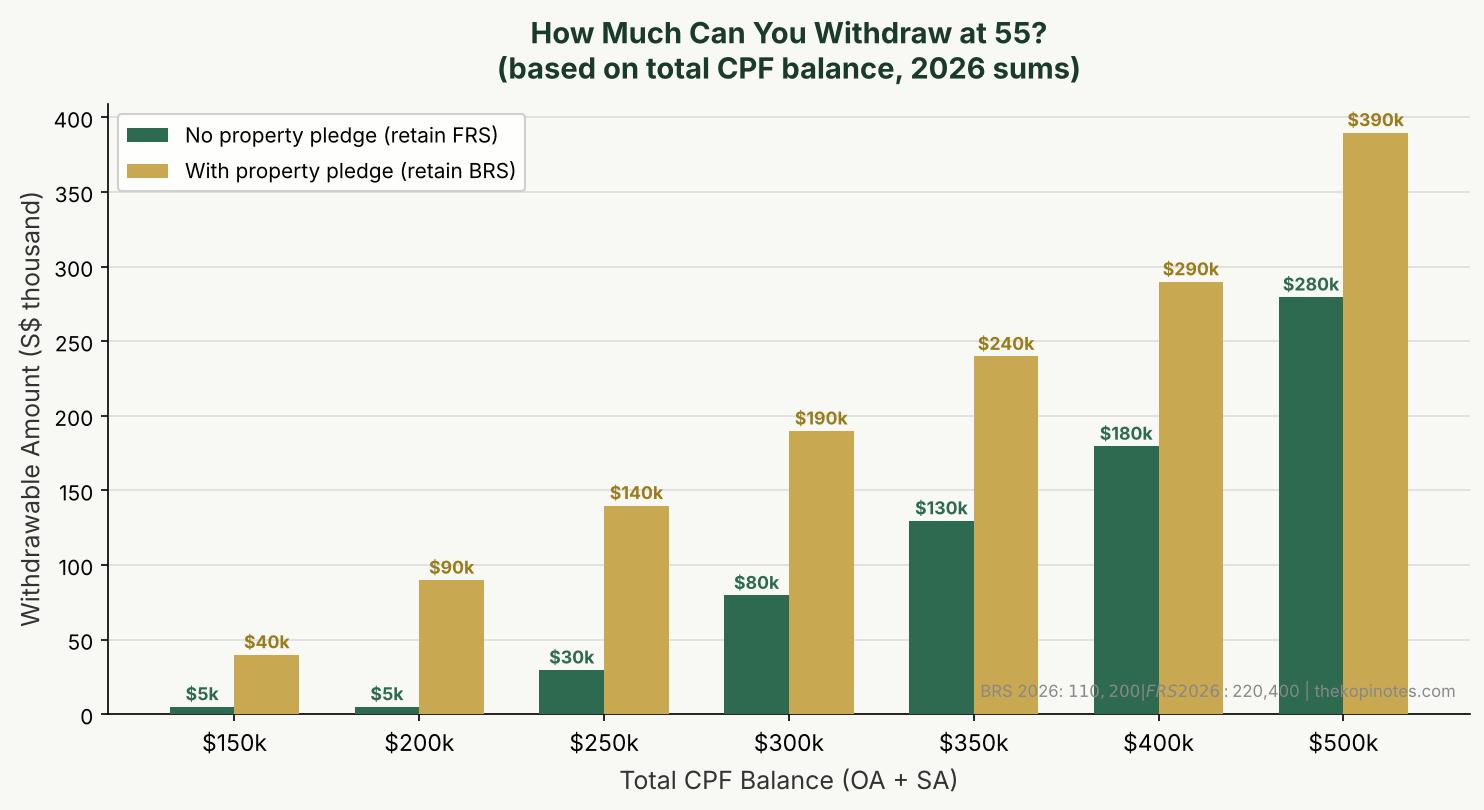
Chart 1: Illustrative withdrawable amounts at different total CPF balances (OA+SA), 2026 retirement sums. Minimum S$5,000 applies in all cases.
What Happens to the Money You Leave in the RA?
Not withdrawing everything at 55 is not simply a matter of leaving money idle. The Retirement Account earns at least 4% per year, guaranteed by the Singapore government — one of the highest risk-free rates available to retail investors in Singapore. Members aged 55 and above receive additional interest on top of this base rate:
- Extra 1% interest on the first S$60,000 of combined CPF balances (OA capped at S$20,000 towards this)
- Additional 1% (total 2% extra) for members aged 55 and above, on the first S$30,000 of combined balances
In practice, the effective rate on the first S$30,000 of RA is 6% per year (4% base + 1% extra + 1% extra for 55+), the next S$30,000 earns 5%, and the remaining balance earns 4%.
| Age | FRS in RA (S$220,400) | Example RA (S$170,800) | BRS in RA (S$110,200) |
|---|---|---|---|
| 55 | S$220,400 | S$170,800 | S$110,200 |
| 57 | S$239,517 | S$185,576 | S$120,132 |
| 60 | S$267,344 | S$207,124 | S$135,253 |
| 62 | S$289,428 | S$224,264 | S$147,195 |
| 65 (payout starts) | S$325,893 | S$252,614 | S$166,876 |
Illustrative only. Assumes 4% base + extra interest on first S$60k/S$30k (55+ bonus). For personalised projection, see the CPF LIFE payout planner at my.cpf.gov.sg.
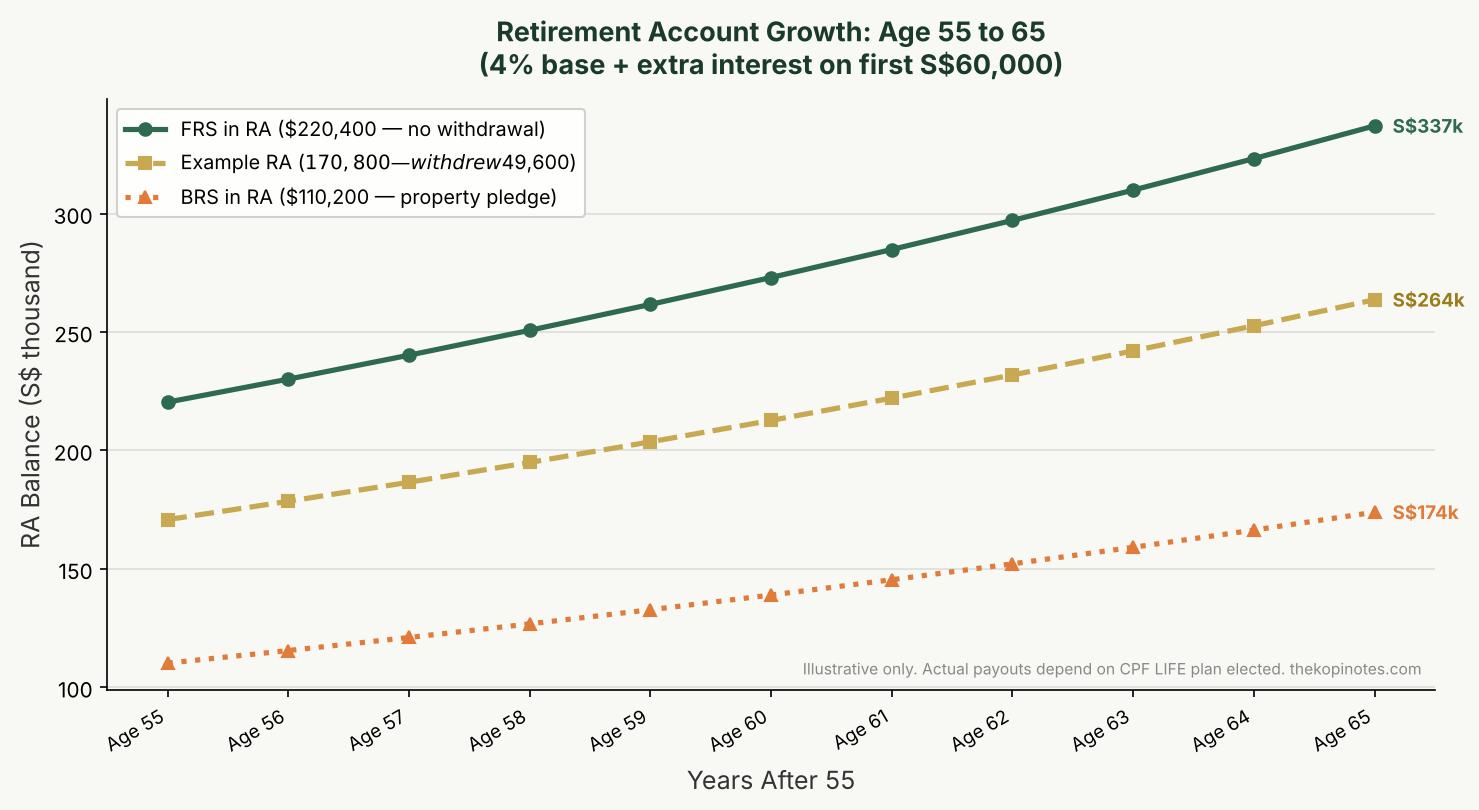
Chart 2: Projected RA balance at age 65. Money left in RA compounds at 4%+; money withdrawn does not. Illustrative only.
CPF LIFE: What Happens to Your RA at 65
The money you leave in your RA does not sit there indefinitely. At age 65 (or a deferred age up to 70), CPF Board automatically enrols you into CPF LIFE (Lifelong Income For the Elderly) — Singapore’s national longevity insurance scheme. Your RA balance is pooled with other members, and you receive a guaranteed monthly income for the rest of your life.
You choose from three plans: the Standard Plan (higher monthly payout, decreasing bequest), the Basic Plan (lower payout, larger bequest for beneficiaries), and the Escalating Plan (payouts start lower but increase by 2% per year, helping pace with inflation).
Deferring payouts to age 70: Each year you defer beyond 65 increases your eventual monthly payout by approximately 6–7%. A member who defers from 65 to 70 could receive roughly 35% more each month — funded by continued RA compound growth during the deferral period. This strategy suits members who have other income sources bridging the gap from 65 to 70.
How to Apply for CPF Withdrawal at 55
Withdrawals do not happen automatically. You must apply. The process is entirely online:
- Log in to my.cpf.gov.sg using your SingPass.
- Navigate to My Statement → Retirement to review your RA balance, retirement sum status, and estimated withdrawable amount.
- Go to Services → Withdrawals → Withdraw my CPF savings.
- Select the amount you wish to withdraw (partial or full surplus) and your nominated bank account.
- Review and submit. Processing typically takes 5–7 business days.
There is no deadline to withdraw — your surplus sits in OA at 2.5% per year until you request it. You can make multiple withdrawals over time.
Property pledge application: Apply separately through my.cpf.gov.sg before or around your 55th birthday. CPF Board checks your property’s lease coverage and confirms eligibility. The pledge adjusts your RA requirement for the withdrawal computation.
Key Considerations: Withdraw or Leave It In?
This question does not have a universal answer. Here are the key tradeoffs:
Reasons to withdraw the surplus: You have high-return investment opportunities outside CPF (after accounting for risk). You need liquidity for near-term expenses such as renovation, healthcare, or mortgage clearance. Your other retirement income sources are already sufficient.
Reasons to leave the surplus in OA (or top up RA): The guaranteed 4%+ in RA (or 2.5% in OA) is hard to beat on a risk-adjusted basis, especially after fees. Money in OA can still be deployed for CPF Investment Scheme (CPFIS) investments. Topping up your RA beyond FRS (up to ERS, S$440,800) voluntarily increases your CPF LIFE payouts further.
The property pledge is almost always worth exploring if you own a qualifying property. If you intend to age in place and never sell, the pledge essentially frees up S$110,200 at no real cost. If you do sell, the refund reduces but does not eliminate your net proceeds — and your RA has had the benefit of compounding on the extra S$110,200 you did not set aside.
For a fuller picture of how much you actually need in retirement, see the FIRE Singapore: The Number guide.
Related Tools
Calculate your CPF retirement picture:
- CPF Withdrawal at 55 Calculator — Enter your OA and SA balances to see exactly how much you can withdraw, with and without a property pledge.
- Retirement Planning Calculator — Project your retirement readiness, CPF LIFE income, and savings gap in one dashboard.
Disclaimer: This article is for general informational purposes only and does not constitute financial, legal or tax advice. CPF rules, retirement sums and interest rates are subject to change by the CPF Board and the Singapore government. All figures are as at October 2026. Verify current figures at cpf.gov.sg and consult a licensed financial adviser before making CPF-related decisions.
Frequently Asked Questions
Can I withdraw all my CPF savings at 55?
What is the Basic Retirement Sum (BRS) for 2026?
Does the Special Account still earn 4% after it closes at 55?
Is my CPF withdrawal lump sum taxable?
What happens if I die before withdrawing or before CPF LIFE starts?
Can I top up my RA after 55 to get higher CPF LIFE payouts?
I own a private condo — can I still pledge my property?
What is the difference between CPF withdrawal at 55 and CPF LIFE payouts at 65?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.