Endowment Plan Maturity Singapore 2026: 5 Smart Ways to Invest Your Payout
When your endowment plan matures, make your money work harder in Singapore’s 2026 post-rate-hike environment.
Table of Contents
📋 Jump To
- What Happens When Your Endowment Matures
- Option 1: Roll Into a New Endowment Plan
- Option 2: Singapore Savings Bonds (SSB)
- Option 3: CPF Voluntary Top-Up
- Option 4: ETFs or Unit Trusts
- Option 5: High-Yield Savings Account or Fixed Deposit
- Decision Framework: Which Option Is Right for You?
- Frequently Asked Questions
Your endowment plan has matured — and your insurer is about to pay out a lump sum. Whether it’s S$20,000 or S$200,000, what you do next determines how hard that money works for you. In Singapore’s Q4 2026 environment — where T-bill yields have dipped to 1.60–1.92% and CPF rates remain steady at 2.5–4.0% — you have five smart reinvestment paths to consider. Here’s a clear breakdown of each option so you can make the right call for your goals.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026 unless noted.
What Happens When Your Endowment Plan Matures
When your endowment plan reaches its maturity date, the insurer pays out your guaranteed sum assured plus any accumulated bonuses (for participating/par plans) or the full guaranteed maturity value (for non-participating/non-par plans). This payout is credited directly to your bank account, usually within 5–10 business days of the maturity date.
Singapore does not impose capital gains tax or tax on insurance payouts — so your entire endowment maturity payout is tax-free, regardless of the plan type or payout amount.
Par vs Non-Par Maturity Payouts Compared
| Feature | Non-Par Endowment | Par Endowment |
|---|---|---|
| Maturity Payout | Fully guaranteed from day one | Guaranteed sum + non-guaranteed bonuses |
| Bonus Component | None | Reversionary + terminal bonus (varies yearly) |
| Typical Return Range | 1.44% – 3.38% p.a. (guaranteed) | 3.25% – 4.25% p.a. (illustrated, not guaranteed) |
| Tax on Payout | Nil (no capital gains tax in Singapore) | Nil |
Source: MAS guidelines on par fund illustration rates; insurer factsheets (October 2026). Actual par returns depend on insurer par fund performance.
Once you receive your maturity proceeds, you are under no obligation to reinvest immediately. That said, leaving a large lump sum in a standard savings account earning 0.05% while inflation runs at 2–3% means your purchasing power is eroding daily. Act within 30–60 days for best results.
Option 1: Roll Into a New Endowment Plan
The most common choice — and often the right one if you valued the capital guarantee — is to reinvest your maturity payout into a new endowment plan tranche. You benefit from your insurer’s loyalty discount (some offer 0.05–0.1% extra return for existing customers) and keep your familiar discipline of forced savings.
As at October 2026, the best available non-par single-premium endowment rates in Singapore include:
| Plan | Tenor | Guaranteed Return | Notes |
|---|---|---|---|
| AIA #Wealth Savvy (III) | 2 years | 3.38% p.a. | Subject to availability; verify with insurer |
| AIA #Wealth Savvy (IV) | 3 years | 2.80% p.a. | Single premium; capital fully guaranteed |
| Prudential PRUAssure Growth | 3 years | 1.70% p.a. | Part of PRU portfolio; check current tranche |
| Great Eastern GREATLife Endowment 3 | Variable | Up to 3.58% p.a. (illustrated) | Par plan; return includes non-guaranteed bonus |
Source: Insurer product pages (AIA, Prudential, Great Eastern). Rates are indicative and subject to change. Verify directly before committing. October 2026.
Best for: Conservative investors (typically 50+) who want guaranteed returns and no market exposure. Particularly attractive if you can access a 2-year tranche offering above 3% — above current T-bill levels.
Watch out for: Surrender penalties if you exit before maturity. A 3-year plan locks your funds until 2029 — don’t commit money you might need before then.
Option 2: Singapore Savings Bonds (SSB)
Singapore Savings Bonds are issued monthly by the Singapore government and offer a step-up interest rate structure — you earn more the longer you hold. Unlike endowment plans, you can exit any month with no penalty (though redemption takes approximately one month to process).
The October 2026 SSB tranche averages approximately 2.63% p.a. over 10 years. Year-1 returns are typically lower than the long-term average, making SSBs more attractive as a medium-term (3–5 year) hold. The individual cap per person is S$200,000.
For a full breakdown of October 2026 SSB rates and how to apply, see our guide to Singapore Savings Bonds 2026.
Best for: Investors who need flexibility and want government-guaranteed returns. Ideal as a “holding pattern” while you research longer-term allocation options. Also suits retirees who want capital preservation with the option to withdraw if medical expenses arise.
Key constraint: If your endowment payout exceeds S$200,000, you’ll need to split the remainder across other instruments.
Option 3: CPF Voluntary Top-Up
For many working Singaporeans, a CPF Voluntary Top-Up to the Special Account (SA) or Retirement Account (RA) offers the highest risk-free return available domestically: 4.00% p.a., with an extra 1% on the first S$60,000 of combined CPF balances (effectively 5% on that portion).
Under the CPF Retirement Sum Topping-Up (RSTU) Scheme, you can top up your own or a family member’s SA/RA using cash (including endowment maturity proceeds) and receive dollar-for-dollar income tax relief:
- Up to S$8,000 per calendar year for self top-up
- Another S$8,000 per year for topping up a spouse, parent, parent-in-law or grandparent’s account
A Singaporean in the 11.5% tax bracket who tops up S$8,000 saves S$920 in taxes immediately — a guaranteed 11.5% “return” in year one before CPF interest even starts.
However, CPF top-ups are irreversible and governed by CPF withdrawal rules. Funds top up into CPF SA cannot be withdrawn until age 55 or as part of the CPF LIFE scheme. This is unsuitable for investors who may need the cash for non-retirement purposes.
For more on maximising your CPF, see our CPF investment strategy guide.
Best for: Mid-career Singaporeans (30–52) who want to maximise retirement savings, earn 4% risk-free, AND reduce this year’s income tax bill.
Option 4: ETFs or Unit Trusts
If you’re reinvesting for growth over a 10–20 year horizon and can tolerate market volatility, broad-market ETFs deliver materially higher long-term returns than any guaranteed product — at the cost of short-term price swings you must be comfortable holding through.
A Singapore investor who reinvested a S$50,000 endowment payout into a globally diversified ETF like VWRA (Vanguard FTSE All-World UCITS) has historically earned 8–12% annualised returns over a decade. However, these returns are not guaranteed — in a severe bear market, a 20–40% drawdown is possible and you must be willing to hold through it.
Fee drag matters: Traditional unit trusts charge 1.0%–2.5% TER plus up to 5% upfront sales charges. Low-cost ETFs like CSPX or VWRA charge just 0.07%–0.22% TER. On a S$50,000 investment compounded over 10 years at 8% gross, a 1.75% fee drag costs you approximately S$14,000 more than a 0.22% ETF — purely in fees.
For platforms, Syfe (referral code: SRPRFFFCD) offers commission-free ETF portfolio investing with low minimums. Endowus (referral code: 2V343) allows CPF-OA and SRS money to be invested in institutional-class unit trusts at significantly lower fees than retail. FSMOne provides a broad fund marketplace with zero sales charges on most unit trusts.
For context on Singapore’s REIT ETFs as a hybrid income+growth option, see our Singapore REIT ETF guide.
Best for: Investors aged 20–45 with a 10+ year horizon, comfortable with volatility. Consider dollar-cost averaging your maturity payout over 6–12 monthly tranches rather than investing the full lump sum at once.
Option 5: High-Yield Savings Account or Fixed Deposit
For investors who haven’t decided yet — or who anticipate needing the cash within 12 months — a high-yield savings account or short-term fixed deposit provides the best liquidity with still-meaningful returns.
As at October 2026, top bank fixed deposit rates in Singapore range from 2.0%–2.8% p.a. for 3-to-12-month tenors (promotional rates can be higher for new-to-bank funds). Digital bank savings accounts from MariBank, GXS and Trust Bank offer 2.5%–3.5% p.a. with daily interest and no lock-in.
MariBank (referral code: 2DCT80WQ) and Trust Bank (referral code: HTWYQP95) both offer competitive savings rates for Singapore residents — check their latest terms before transferring, as rates change frequently.
Best for: Investors in transition: awaiting a property purchase, expecting a major expense, or simply wanting 30–60 days to research before committing to a longer-term option.
Decision Framework: Which Option Is Right for You?
Use this quick-reference matrix to match your situation to the right reinvestment path:
| Your Situation | Best Option | Expected Return | Risk |
|---|---|---|---|
| Need the money in < 12 months | HYSA / Fixed Deposit | 2.0%–3.5% p.a. | Very Low |
| Want guaranteed growth, 2–3 years | New Endowment Plan | 1.44%–3.38% p.a. | Very Low (capital-guaranteed) |
| Want flexibility + govt backing | Singapore Savings Bond | ~2.63% p.a. avg | Zero (Govt-guaranteed) |
| Max risk-free + tax savings, under 55 | CPF SA Top-Up | 4.00%–5.00% p.a. | Zero (govt-backed) |
| Long-term growth, 10+ year horizon | ETFs (VWRA / CSPX) | 8%–12% p.a. (hist.)* | Medium–High (market risk) |
Source: CPF Board, MAS, insurer product sheets, Vanguard/iShares historical data. October 2026. *ETF historical returns are not a guarantee of future performance.
If you are unsure how large a retirement corpus you need before deciding on aggressive vs conservative reinvestment, use our Singapore retirement calculator to model your target first.
For a broader view of Singapore’s passive income landscape in 2026, see our guide on passive income strategies for Singapore.
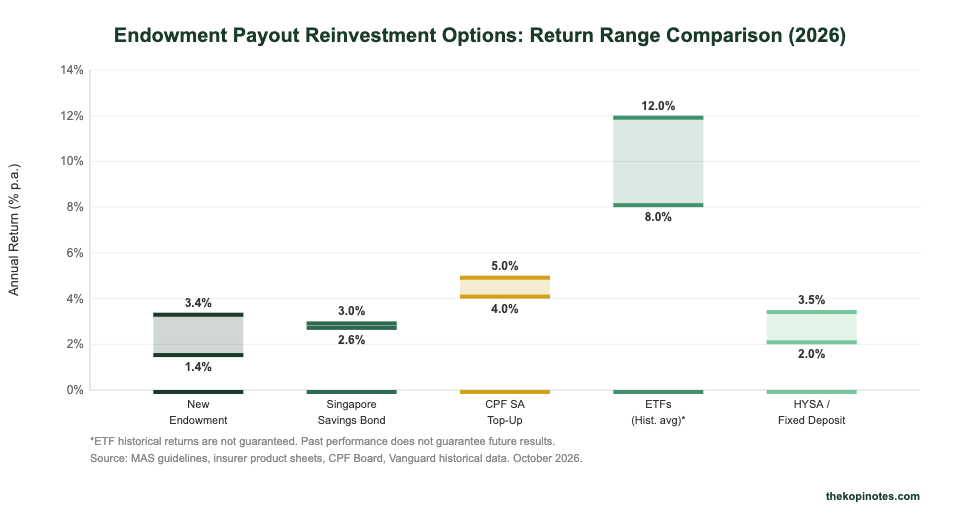
📊 Returns vs Risk: All 5 Options Compared
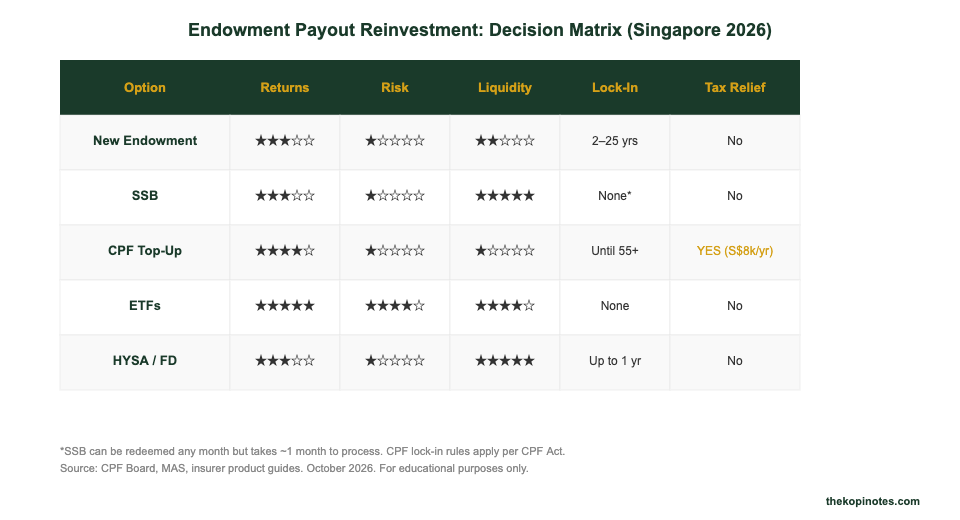
📊 Decision Matrix: 5 Factors at a Glance
Frequently Asked Questions
What happens if I don't claim my endowment payout?
Is my endowment maturity payout taxable in Singapore?
Can I use my endowment payout to top up CPF?
Should I reinvest in another endowment plan or switch to ETFs?
What is the Singapore Savings Bond individual cap?
How soon after maturity should I reinvest?
Ready to Put Your Endowment Payout to Work?
Compare Singapore’s best savings and investment platforms and earn welcome bonuses when you sign up through The Kopi Notes referral links.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.