Mari Credit Card Review Singapore: Cashback, Fees & Is It Worth It? (2026)
An honest, data-backed review of MariBank’s credit card — cashback structure, overseas spending, how it compares, and who should get it.
The Mari Credit Card is a Mastercard issued by MariBank — Singapore’s MAS-licensed digital bank backed by the SEA Group and Grab consortium. It pays 1.5% unlimited cashback on all local spend with no minimum spend, no annual fee, and zero FX fees on overseas transactions. For Singaporeans who want a simple, no-fuss cashback card that works everywhere, it is one of the strongest options in 2026.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
Table of Contents
Contents — Click to expand
What Is the Mari Credit Card?
The Mari Credit Card is a Mastercard credit card issued by MariBank Singapore — a fully MAS-licensed digital bank that launched in 2023 as part of the SEA Group and Grab consortium. Unlike traditional bank credit cards, the Mari Credit Card is applied for and managed entirely through the MariBank app. There is no branch to visit and no paper forms to fill out.
The card is designed around simplicity. There are no complicated cashback categories to track, no minimum spend thresholds to hit, and no annual fee to worry about. You earn a flat 1.5% cashback on every eligible local transaction — groceries, dining, transport, bills, online shopping — without any cap. For overseas spending, you also earn 1.5% cashback on the first S$1,500 of eligible foreign currency spend per month, with zero FX fees (as at October 2026, according to MariBank’s official product page).
Shopee users get an additional perk: 1.5% unlimited Shopee Coins when paying via Mari Credit Card Instant Checkout, making it especially rewarding if you regularly shop on the platform. The card also supports Apple Pay and Google Pay, and you can order a physical numberless card through the app.
MariBank is one of only four digital banks licensed by the Monetary Authority of Singapore (MAS), alongside GXS Bank, Trust Bank, and Green Link Digital Bank. Your deposits with MariBank are protected under the Singapore Deposit Insurance Corporation (SDIC) scheme up to S$100,000 per depositor. If you want to learn more about the bank itself, read our guide on what MariBank is and how it works.
Key Features at a Glance
| Feature | Detail |
|---|---|
| Card Network | Mastercard |
| Local Cashback | 1.5% unlimited, no minimum spend, no cap |
| Overseas Cashback | 1.5% on first S$1,500 of foreign currency spend/month |
| FX Fee | Waived (valid till 31 Dec 2027) |
| Annual Fee | S$0 (no annual fee) |
| Minimum Income | S$30,000/year (21–55); S$15,000/year (55+); below S$30k may qualify for S$500 limit |
| Minimum Age | 21 years old |
| Shopee Coins | 1.5% unlimited via Instant Checkout (valid till 31 Dec 2027) |
| Instalment Plans | Split Payment at 0% interest (3, 6, 12, 18 months) |
| Mobile Wallet | Apple Pay, Google Pay |
| Card Design | Numberless physical card + virtual card |
Source: MariBank official product page, October 2026
Cashback Structure Breakdown
The cashback structure of the Mari Credit Card is deliberately simple — and that is its biggest selling point. Here is how it works in detail.
Local Spend (SGD Transactions)
Every eligible Singapore Dollar transaction posted to your card earns 1.5% cashback. There is no minimum monthly spend to qualify, and there is no cashback cap. This means whether you spend S$50 or S$5,000 in a month, every dollar earns the same flat rate. Cashback is credited automatically to your card account.
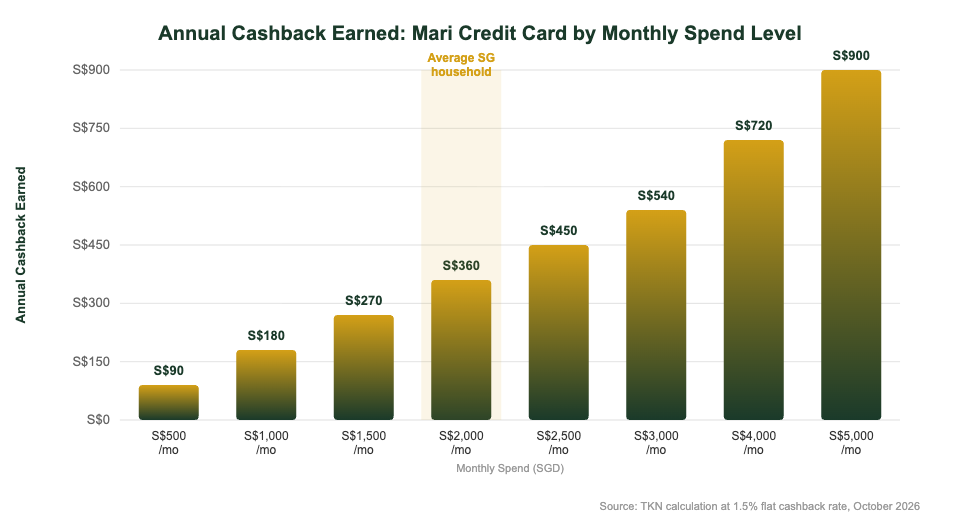
To put this in perspective: on a monthly spend of S$2,000, you earn S$30 in cashback per month, or S$360 per year — with zero effort and no categories to optimise.
Overseas Spend (Foreign Currency Transactions)
The card earns 1.5% cashback on eligible overseas spending in foreign currencies, capped at S$1,500 of eligible foreign currency spend per month. This means the maximum overseas cashback you can earn is S$22.50 per month (1.5% × S$1,500). FX fees have been fully waived since 1 January 2026 and this waiver has been extended through 31 December 2027, according to MariBank’s official terms. MariBank also advertises “best-in-class FX rates” using the Mastercard wholesale exchange rate for eligible currencies including MYR, KRW, CNY, JPY, THB, and more.
Shopee Spend (via Instant Checkout)
When you pay on Shopee using Mari Credit Card Instant Checkout, you earn 1.5% unlimited Shopee Coins instead of cashback. 100 Shopee Coins = S$1, and you can use up to 30% of your total purchase amount as coin offset, with a daily redemption limit of 1,000 coins. This promotion is valid until 31 December 2027.
What Doesn’t Qualify for Cashback
According to MariBank’s terms and conditions, certain transaction types are excluded from cashback. These typically include cash advances, balance transfers, instalment plan fees, interest charges, late payment fees, and government-related payments. Always check the latest MariBank fees and charges page for the full exclusion list.
| Spend Category | Cashback Rate | Cap | Min Spend |
|---|---|---|---|
| Local (SGD) | 1.5% | Unlimited | None |
| Overseas (foreign currency) | 1.5% | S$1,500 spend/month | None |
| Shopee (Instant Checkout) | 1.5% Shopee Coins | Unlimited | None |
| FX Fee | Waived | — | — |
Source: MariBank product page and promotion T&Cs, October 2026
How It Compares: Mari vs Trust vs GXS vs Traditional Cards
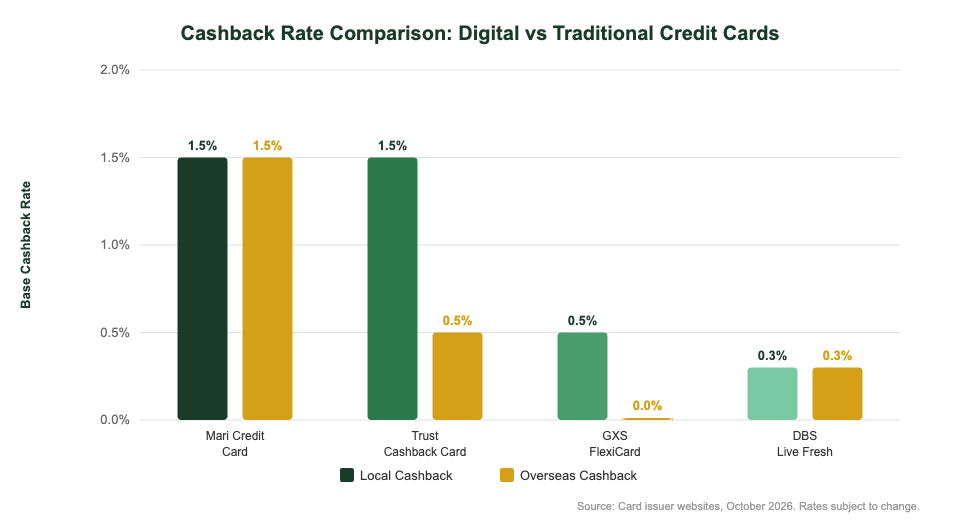
The Mari Credit Card’s main competitors are other digital bank cards — specifically the Trust Bank credit card and the GXS FlexiCard — as well as traditional bank cashback credit cards from DBS, OCBC, and UOB. Here is how they stack up.
| Feature | Mari Credit Card | Trust Cashback Card | GXS FlexiCard | DBS Live Fresh |
|---|---|---|---|---|
| Base Cashback | 1.5% unlimited | Up to 1.5% local | Varies by promo | Up to 5% (capped) |
| Annual Fee | S$0 | S$0 | S$0 | S$194.40 (waivable) |
| Min Spend | None | None | Varies | S$600/month |
| FX Fee | Waived | Waived | Varies | ~3.25% |
| Overseas Cashback | 1.5% (capped S$1,500/mo) | 0.5% unlimited | Varies | Up to 5% (capped) |
| Min Income | S$30k (S$500 limit below) | None stated | None stated | S$30k |
| Best For | Everyday + travel | NTUC shoppers | Grab users | Online shopping |
Source: Respective card issuer websites, October 2026. Rates and terms may change.
Mari vs Trust Bank Credit Card
Both cards charge no annual fee, no minimum spend, and have waived FX fees. The key difference is the cashback model. Mari gives a flat 1.5% on everything local, while Trust offers up to 1.5% on local spend plus a bonus category system where you choose one preferred category per quarter for up to 15% cashback (capped at S$250/quarter). If you are the type who prefers set-and-forget simplicity, Mari wins. If you actively optimise and shop frequently in one category (dining, groceries, transport), Trust may yield higher returns in that specific category. For overseas spending, Mari’s 1.5% (capped at S$1,500/month) beats Trust’s 0.5% unlimited. For travel, Mari is the stronger pick. Want to see the full breakdown? Read our Trust Bank referral code and sign-up guide.
Mari vs GXS
GXS launched the FlexiCard in 2026 — a credit card that charges a flat fee instead of revolving interest. GXS’s primary strength is its savings account ecosystem (higher interest on Boost Pockets) and Grab integration. For a pure credit card cashback comparison, Mari’s 1.5% flat rate with no conditions is simpler and more predictable. If you are already deep in the Grab ecosystem, GXS may complement your spending. Otherwise, Mari offers better standalone credit card value. Compare the full digital bank landscape in our GXS Bank referral code guide.
Mari vs Traditional Bank Cards (DBS, OCBC, UOB)
Traditional bank cashback cards like the DBS Live Fresh, OCBC 365, or UOB One Card can offer higher peak cashback rates (3–8%) but always come with conditions: minimum monthly spend (often S$600–S$800), cashback caps (S$20–S$80/month), specific spending categories, and annual fees that require a phone call to waive. For moderate spenders — those spending S$1,000–S$3,000/month without wanting to optimise categories — the Mari Credit Card’s guaranteed 1.5% on everything often beats what traditional cards deliver after caps and exclusions. If you have the patience and spend volume to maximise a traditional card, you can earn more. But most Singaporeans do not consistently hit those thresholds every month. Use our Singapore retirement calculator to see how even small cashback differences compound over a 20–30 year savings horizon.
Credit Limit: How It Works & How to Increase It
Your initial credit limit on the Mari Credit Card is determined by MariBank based on your income declaration, credit bureau data, and internal risk assessment. There is no fixed starting limit published — it varies by applicant. Singaporeans and PRs who earn below S$30,000 per year can still qualify for the card, but with a lower credit limit of S$500, according to MariBank’s eligibility page.
How to Increase Your MariBank Credit Card Limit
To request a credit limit increase, follow these steps in the MariBank app:
- Log in to the MariBank app
- Tap Mari Credit Card on the home screen
- Go to Settings
- Tap Request Credit Limit Increase under the Account(s) section
- Complete and submit your application
You have a higher chance of approval if your annual income is S$30,000 or above, you have no outstanding overdue payments, and you have received a recent income increase or bonus. If you choose not to upload bank statements, the request is processed immediately. If you upload bank statements for verification, processing takes up to 3 working days, according to MariBank’s help centre.
Pros and Cons
| Pros | Cons |
|---|---|
|
1.5% unlimited cashback on local spend — no cap, no categories, no minimum
Zero annual fee — permanently, not waivable-on-request Zero FX fees on overseas spend (till Dec 2027) No income requirement barrier — earners below S$30k can still get a S$500 limit 1.5% Shopee Coins via Instant Checkout 0% interest Split Payment for instalments (3–18 months) Apple Pay & Google Pay supported |
Overseas cashback capped at S$1,500 spend/month (max S$22.50 cashback/month)
No ATM withdrawals — local or overseas FX fee waiver is promotional — currently extended to Dec 2027, but not guaranteed permanently Requires MariBank app/account — cannot apply standalone Lower initial credit limits compared to traditional banks for some applicants Limited rewards ecosystem — no miles, no points, cashback only No lounge access or premium perks that come with higher-tier traditional cards |
Who Is the Mari Credit Card Best For?
The Mari Credit Card is ideal for several specific spending profiles:
Everyday spenders who hate complexity. If you spend S$1,000–S$3,000/month across groceries, dining, transport, and bills, and you do not want to track categories or hit minimum thresholds, the Mari Credit Card gives you a reliable 1.5% return on everything. On S$2,000/month, that is S$360 per year in cashback — completely hands-off.
Frequent travellers. The combination of zero FX fees and 1.5% overseas cashback (on the first S$1,500 of foreign currency spend per month) makes this a strong travel card. For a 10-day overseas trip where you spend S$1,200 in foreign currency, you save the ~3% FX fee you would pay on most traditional cards (S$36 saved) and earn S$18 in cashback — a total of S$54 in value from a single trip.
Young professionals and first-time cardholders. The fact that Singaporeans earning below S$30,000 can still qualify (with a S$500 limit) makes this one of the most accessible credit cards in the market. You do not need to meet the S$30,000 income bar that most traditional bank cards require, making it one of the best first credit cards you can get in Singapore. Read our guide on the best credit cards for young adults in Singapore to see how it stacks up.
Shopee regulars. With 1.5% unlimited Shopee Coins via Instant Checkout plus 0% interest Split Payment, this is the default card for Shopee shoppers.
The card is not ideal for heavy spenders who can consistently hit bonus cashback tiers on traditional cards (e.g., S$2,000/month in a single category on the OCBC 365), miles collectors who want to convert spend into flight rewards, or users who need overseas ATM cash withdrawals.
How to Apply for the Mari Credit Card (Step by Step)
The application is fully digital and takes about 5–10 minutes:
- Download the MariBank app from the App Store, Google Play, or Huawei AppGallery
- Register for a MariBank account using your Singapore mobile number (this creates a Mari Savings Account)
- Apply for the credit card — on the home screen, tap “Mari Credit Card” → “Get Card Now” or “Apply”
- Verify via Singpass — your identity and income details are retrieved automatically through MyInfo. No documents needed for Singaporeans and PRs
- Receive your virtual card — upon successful application, your virtual card is activated instantly. You can add it to Apple Pay or Google Pay immediately
- Order a physical card (optional) — request a free numberless physical card through the app at any time
Eligibility recap: You must be 21 years or older, a Singaporean/PR or foreigner with a valid pass (6+ months validity), and your details are verified via Singpass. Foreigners need to upload a passport photo during application.
Use our MariBank referral code 2DCT80WQ when signing up to receive the latest sign-up bonus.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Credit card terms, cashback rates, and promotions are subject to change. Always verify the latest terms on MariBank’s official website before applying. The Kopi Notes may earn a referral fee if you sign up through our referral links — this does not affect our editorial independence or your sign-up experience.
Frequently Asked Questions
Is the MariBank credit card good?
Yes, the Mari Credit Card is a strong everyday cashback card for most Singaporeans. It offers 1.5% unlimited cashback on all local spend with no minimum spend, no cap, and no annual fee. For moderate spenders (S$1,000–S$3,000/month) who do not want to track spending categories, it consistently outperforms most traditional bank cards on a net cashback basis. It is also one of the best travel credit cards in Singapore thanks to its zero FX fees and 1.5% overseas cashback.
What is the cashback rate on the Mari Credit Card?
The Mari Credit Card pays 1.5% cashback on all eligible local (SGD) transactions with no minimum spend and no cap. For overseas foreign currency transactions, it pays 1.5% cashback on the first S$1,500 of eligible spend per month. On Shopee via Instant Checkout, it earns 1.5% unlimited Shopee Coins. All rates are as at October 2026.
Does the Mari Credit Card charge FX fees for overseas spending?
No. MariBank waived all foreign exchange fees on the Mari Credit Card from 1 January 2026. This waiver has been extended through 31 December 2027. This means you pay no additional FX markup on any overseas or online foreign currency transaction. MariBank uses the Mastercard wholesale exchange rate for eligible currencies, which is typically more competitive than traditional bank FX markups of 2.5–3.5%.
How do I increase my MariBank credit card limit?
To request a credit limit increase, open the MariBank app, tap your Mari Credit Card, go to Settings, and select “Request Credit Limit Increase.” If you do not upload bank statements, the request is processed immediately. If you upload statements, it takes up to 3 working days. You have a better chance of approval if your annual income is at least S$30,000, you have no overdue payments, and you have had a recent income increase or bonus.
Can I get the Mari Credit Card with income below S$30,000?
Yes. Singaporean Citizens and Permanent Residents aged 21 to 55 who earn below S$30,000 per year can still apply for the Mari Credit Card. If approved, you will receive a lower credit limit of S$500. This makes the Mari Credit Card one of the few credit cards in Singapore accessible to lower-income earners, making it a strong first credit card option.
Is the Mari Credit Card better than the Trust Bank credit card?
It depends on your spending style. The Mari Credit Card offers a flat 1.5% cashback on all local spend with no conditions, while Trust Bank’s Cashback Card offers up to 1.5% local plus a bonus category system (up to 15% on one chosen category per quarter, capped at S$250). For simplicity and overseas travel, Mari is better. For shoppers who can maximise a single spending category, Trust may yield higher cashback in that category. Both have zero annual fees and waived FX fees.
What are the fees and charges on the Mari Credit Card?
The Mari Credit Card has no annual fee and no FX fee (waived till December 2027). Other fees include a late payment fee, a cash advance fee, and interest on outstanding balances if you do not pay your statement in full. The prevailing interest rate and specific fee amounts are listed on the MariBank Interest, Fees and Charges page at maribank.sg/fees-rates/mari-credit-card. As with any credit card, always pay your full statement balance by the due date to avoid interest charges.
Can I use the Mari Credit Card with Apple Pay and Google Pay?
Yes. The Mari Credit Card supports both Apple Pay and Google Pay. You can add your virtual card to either mobile wallet immediately after approval — you do not need to wait for the physical card to arrive. This means you can start earning cashback on contactless payments right away. The physical card, which is numberless for security, can be ordered for free through the MariBank app at any time.
Ready to Get the Mari Credit Card?
Use our referral code for the latest sign-up bonus. Apply in 5 minutes — fully digital, no documents needed.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.