UOB Fixed Deposit Rate Promotion Singapore (September 2026): Up to 1.55% p.a.
Everything you need to know about the latest UOB FD promotional rates — tenors, eligibility, and whether it beats competing banks.
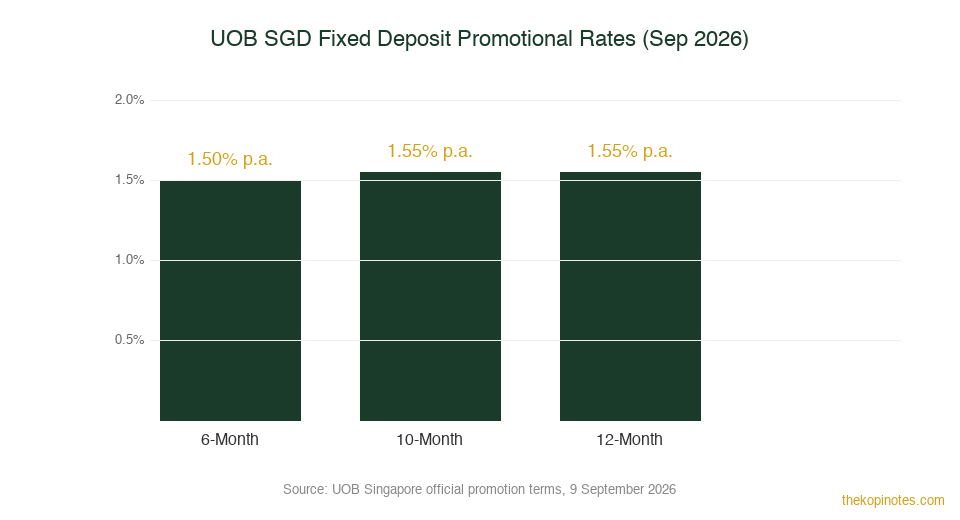
UOB’s September 2026 Singapore Dollar fixed deposit promotion runs from 9 to 30 September 2026, offering up to 1.55% p.a. on eligible fresh-fund placements. Three promotional tenors are available: 6 months at 1.50% p.a., and both 10 and 12 months at 1.55% p.a. A minimum placement of S$10,000 in fresh funds is required. The deposit must be held to maturity to receive the promotional rate.
Not financial advice. All figures are for educational reference only. Data verified as at 16 September 2026.
- UOB’s current promotion gives 1.55% p.a. on 10- and 12-month tenors with S$10,000+ in fresh funds.
- This is lower than CIMB (2.58%), SSB (2.32%), and Standard Chartered (2.00%) — but convenient if you are already a UOB customer.
- Money must come from outside UOB and be held to maturity — no early withdrawal allowed.
Table of Contents
Contents — Click to expand
UOB September 2026 Promotional Rates
UOB’s latest fixed deposit promotion started on 9 September 2026 and runs until 30 September 2026. It covers three tenors and requires a minimum placement of S$10,000 in fresh funds.
| Tenor | Min. Placement | Promotional Rate |
|---|---|---|
| 6 months | S$10,000 (fresh funds) | 1.50% p.a. |
| 10 months | S$10,000 (fresh funds) | 1.55% p.a. |
| 12 months | S$10,000 (fresh funds) | 1.55% p.a. |
Source: UOB Singapore official promotion terms, 9 September 2026. Rates are for fresh funds only and subject to change.
To put these numbers in context: if you place S$50,000 in a 12-month UOB fixed deposit at 1.55% p.a., you earn S$775 in interest over the year. That’s before tax considerations — though Singapore currently has no withholding tax on SGD fixed deposit interest for residents.
What Counts as Fresh Funds?
This is the most important term to understand. Fresh funds mean money that comes from outside your existing UOB accounts. Specifically:
- ✅ Transfers from a non-UOB bank account (e.g. DBS, OCBC, MariBank)
- ✅ A non-UOB cheque
- ❌ Money moved from an existing UOB savings, current, or fixed deposit account
- ❌ A UOB cheque
If you move money from your UOB savings account into the fixed deposit, it does not qualify as fresh funds. You will not receive the promotional rate — only the standard board rate, which is much lower. Always fund from a non-UOB source to qualify.
How to Apply for the UOB FD Promotion
You can place the fixed deposit entirely online — no need to visit a branch. UOB offers two digital channels:
Via UOB TMRW Mobile App
- Transfer fresh funds from your non-UOB bank account to an eligible UOB savings or current account.
- In the TMRW app, go to Services > Fixed deposit placement.
- Enter your preferred tenor and amount, then swipe to confirm.
Via UOB Personal Internet Banking
- Log in to UOB Personal Internet Banking.
- Navigate to Investment > Fixed Deposit.
- Fill in the required details and confirm.
Online placement is available Monday to Friday 9.30am–9.30pm, and Saturday 8.00am–9.30pm. Instructions outside these hours are processed the next business day. Each online placement is capped at S$999,999.
If you are a new UOB customer, you will need to open a UOB savings or current account first before you can place a fixed deposit. Singaporeans and PRs aged 18 and above can apply online using MyInfo for an instant account opening.
How UOB’s Promotional Rate Has Changed in 2026
UOB has steadily increased its fixed deposit promotional rates throughout 2026. Each hike has come in 0.10 percentage point (10 basis point) steps:
| Promotion Round | Headline Rate | Change |
|---|---|---|
| April 2026 | 1.25% p.a. | — |
| July 2026 | 1.35% p.a. | +0.10 pp ↑ |
| August 2026 | 1.45% p.a. | +0.10 pp ↑ |
| September 2026 (current) | 1.55% p.a. | +0.10 pp ↑ |
Source: SINGPromos.com, compiled from UOB official promotion rounds, April–September 2026.
The September 2026 rate of 1.55% p.a. is the highest UOB has offered in this tracked sequence. That said, competing banks are offering even higher rates — more on that below.
UOB vs Other Banks: Fixed Deposit Rate Comparison (Sep 2026)
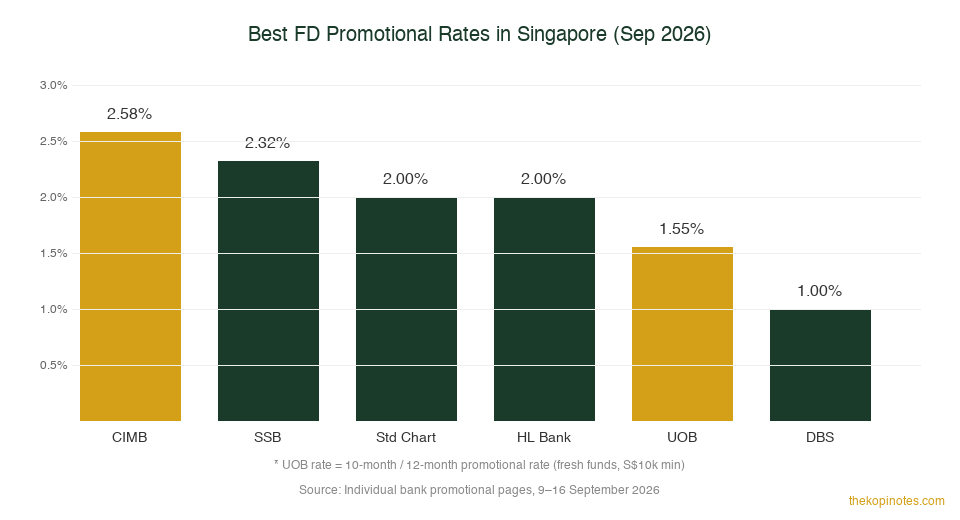
How does UOB stack up against the competition this month? Here’s a quick comparison of the best promotional rates available in Singapore as at September 2026:
| Bank | Best Rate | Tenor | Min. Amount |
|---|---|---|---|
| CIMB | 2.58% p.a. | Fresh funds promo | Varies |
| Singapore Savings Bonds (SSB) | 2.32% p.a.* | 10-year avg | S$500 |
| Standard Chartered | 2.00% p.a. | 6 months (Priority Banking) | S$10,000 |
| HL Bank | 2.00% p.a. | 24 months | S$10,000 |
| UOB (current promo) | 1.55% p.a. | 10 or 12 months | S$10,000 fresh |
| DBS | ~1.00% p.a. | Standard tenors | S$1,000 |
Source: Individual bank promotional pages and SingSaver, 9–16 September 2026. *SSB 10-year average return; actual 1-year return differs. Rates subject to change.
The honest picture: UOB’s 1.55% promotion is competitive among the local Big Three banks (DBS/OCBC/UOB). However, smaller banks like CIMB and certain Citibank offers currently beat it by a significant margin. If you are purely rate-chasing and comfortable with CIMB or other banks, you can earn more elsewhere.
That said, many Singaporeans prefer the convenience of UOB — especially if their salary credit, credit cards, and savings are already with UOB. Consolidating also helps with the UOB ONE Account bonus interest tiers.
Is the UOB FD Promotion Worth It?
Whether UOB’s fixed deposit promotion is “worth it” depends on your situation. Here are three common scenarios:
Scenario 1: You already bank with UOB
If your savings are at DBS or OCBC but you have a UOB account, moving S$10,000 in as fresh funds gets you 1.55% p.a. — without having to open a new bank account. That’s a straightforward win compared to leaving money in a standard savings account earning 0.05%.
Scenario 2: You want the absolute best rate
Open a CIMB account and place under their fresh funds promotion at 2.58% p.a. On S$50,000, that’s S$1,290/year vs S$775/year with UOB — a difference of S$515. The extra steps may be worth it for larger sums.
You can also consider Singapore Savings Bonds (2.32% 10-year average) if you can wait for the monthly application window. SSBs have no lock-in — you can redeem any month with 1-business-day notice.
Scenario 3: You want full flexibility
Fixed deposits require you to lock in money until maturity. If you withdraw early, UOB pays zero interest. For funds you might need anytime, consider a high-yield savings account instead — or look into the retirement planning calculator to see how liquidity fits your broader goals.
Eligibility and Key Terms to Know
- Who can apply: Individual UOB customers (not joint accounts for this promotion). Singaporeans and PRs aged 18+.
- Minimum placement: S$10,000 in fresh funds.
- Hold to maturity: Premature or partial withdrawal means the promotional rate is not paid. No partial redemption.
- One-time lock-in: Once UOB confirms your placement rate, it stays fixed for the tenor — even if UOB later changes the promotion.
- Early closure fee: A S$30 fee applies if the SGD Fixed Deposit Account itself is closed within 6 months of opening.
- Deposit insurance: SGD deposits are covered under the Singapore Deposit Insurance Scheme (SDIC) up to S$100,000 per depositor per member institution.
- Promotion expiry: This round ends 30 September 2026. UOB may extend, modify, or withdraw it without prior notice.
For the full terms, download the official PDFs from UOB:
6-month terms (PDF) |
10-month terms (PDF) |
12-month terms (PDF)
Not financial advice. Always read the full terms and conditions on UOB’s official website before placing any deposit. The Kopi Notes may earn referral fees through certain links on this page.
Frequently Asked Questions
What is the current UOB fixed deposit promotional rate?
The current UOB Singapore Dollar fixed deposit promotional rates (9–30 September 2026) are: 1.50% p.a. for 6 months, and 1.55% p.a. for both 10 and 12 months. A minimum of S$10,000 in fresh funds is required. The promotional period runs until 30 September 2026.
What happens if I withdraw my UOB fixed deposit early?
If you withdraw your UOB fixed deposit before it matures — even partially — the promotional interest rate will not be paid. UOB pays zero interest on prematurely withdrawn fixed deposits. You will only get back your principal. This is why it is critical to place only funds you are sure you will not need during the tenor.
Can I use money from my existing UOB savings account?
No. Money transferred from an existing UOB savings, current, or fixed deposit account does not count as fresh funds for this promotion. You must bring in money from outside UOB — for example, from a DBS, OCBC, or MariBank account — to qualify for the promotional rate. UOB cheques also do not count.
How do I place a UOB fixed deposit online?
You can place it via the UOB TMRW mobile app (Services > Fixed deposit placement) or via UOB Personal Internet Banking (Investment > Fixed Deposit). Online placements are available Monday to Friday 9.30am–9.30pm and Saturday 8.00am–9.30pm. Instructions outside these hours are processed the next business day. Each placement is capped at S$999,999.
Is the UOB fixed deposit rate better than DBS or OCBC?
Currently, UOB’s promotional rate of 1.55% p.a. is generally higher than DBS’s standard fixed deposit rates (around 1.00% p.a.) for comparable tenors. It is broadly in line with OCBC’s promotional offerings. However, both CIMB (up to 2.58%) and Singapore Savings Bonds (2.32% average) currently offer higher returns. If you are already a UOB customer and want convenience, UOB’s promotion is competitive among the Big Three local banks.
Is my UOB fixed deposit protected by deposit insurance?
Yes. SGD deposits with UOB are insured under the Singapore Deposit Insurance Corporation (SDIC) Scheme up to S$100,000 per depositor per Scheme member institution. This applies to fixed deposits, savings accounts, and current accounts combined. If you hold more than S$100,000 across all UOB accounts, the amount above the cap is not insured. Foreign-currency and investment products are not covered.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.