ParkwayLife REIT Dividend 2026: DPU Up 14.6%, Hospital Yield & Is C2PU Worth Buying?
A complete Singapore investor’s guide to ParkwayLife REIT’s dividend history, 1H2026 results, hospital portfolio, and 2026 outlook.
ParkwayLife REIT (SGX: C2PU) is Singapore’s largest listed healthcare REIT, owning 73 properties across Singapore, Japan, and France valued at S$2.56 billion. Its 1H2026 Distribution Per Unit (DPU) jumped 14.6% year-on-year to 8.77 Singapore cents, driven by a 24.3% Singapore hospital rent reset. At ~S$4.15 per unit, the trailing yield is approximately 4.0% — lower than the S-REIT sector average but backed by the most defensive lease structure in Singapore real estate.
Not financial advice. All figures are for educational reference only. Data as at August–October 2026 unless noted.
Table of Contents
Contents — Click to expand
- What Is ParkwayLife REIT?
- Key Facts at a Glance
- 1H2026 DPU: The 14.6% Jump Explained
- DPU History 2021–2026
- Singapore Hospital Portfolio: The Income Engine
- Japan & France: Diversification and Risks
- Is ParkwayLife REIT Worth Buying in 2026?
- How to Buy ParkwayLife REIT (C2PU) in Singapore
- Frequently Asked Questions
What Is ParkwayLife REIT?
ParkwayLife REIT (C2PU) was listed on the Singapore Exchange in August 2007 and is managed by Parkway Trust Management, a wholly-owned subsidiary of IHH Healthcare — one of Asia’s largest private hospital groups. This parentage is no accident: IHH’s flagship Singapore hospitals, including Mount Elizabeth Hospital, Gleneagles Hospital, and Parkway East Hospital, are the anchor tenants of the REIT’s Singapore portfolio.
The REIT’s structure is unusually defensive by S-REIT standards. All Singapore hospital leases are long-term, triple-net arrangements with a minimum rent floor and a variable rent component tied to hospital gross operating revenue. This means distributions do not fall below a minimum even if the hospitals have a bad year — a structural protection that no industrial or retail REIT in Singapore offers.
As at June 2026, ParkwayLife REIT owns 73 healthcare properties across three geographies: three iconic private hospitals in Singapore, 69 nursing homes and healthcare facilities in Japan, and two nursing homes in France. Total portfolio valuation stands at S$2.56 billion. For investors seeking passive income in Singapore, C2PU represents a fundamentally different risk profile compared to most S-REITs — defensive, inflation-linked, and backed by essential healthcare infrastructure.
Key Facts at a Glance
| Metric | Detail |
|---|---|
| Full Name | ParkwayLife Real Estate Investment Trust |
| SGX Ticker | C2PU |
| Listing Date | 23 August 2007 |
| Manager | Parkway Trust Management (IHH Healthcare) |
| 1H2026 DPU | 8.77 Singapore cents (+14.6% YoY) |
| Trailing Yield (est.) | ~4.0% at S$4.15 unit price |
| Portfolio Valuation | S$2.56 billion (as at 30 Jun 2026) |
| Number of Properties | 73 (3 SG hospitals + 69 JP + 1 FR) |
| Gearing Ratio | ~35–36% (well within MAS 50% limit) |
| Distribution Frequency | Semi-annual (H1 + H2) |
Source: ParkwayLife REIT SGX announcements, August 2026.
1H2026 DPU: The 14.6% Jump Explained
ParkwayLife REIT’s 1H2026 DPU of 8.77 cents — up from 7.65 cents in 1H2025 — is one of the strongest half-year dividend growth figures recorded by any S-REIT in 2026. To understand why this jump happened, investors need to understand how Singapore hospital leases are structured.
The three IHH-anchored hospitals (Mount Elizabeth, Gleneagles, and Parkway East) are leased under a formula that resets the minimum guaranteed rent every few years, using the Consumer Price Index (CPI) as the base escalator. In FY2026, this periodic rent reset triggered a 24.3% step-up in the minimum Singapore hospital rent — a large, one-time uplift reflecting the cumulative inflation since the last reset cycle. Variable rent on top of the minimum guaranteed component is tied to each hospital’s gross operating revenue, creating upside leverage as Singapore’s private healthcare market continues growing.
This reset effect is substantial but should be understood in context: it reflects catch-up inflation over multiple years, not recurring annual growth. Investors should not expect another 14.6% DPU jump in 1H2027 from this same mechanism. However, the step-up does permanently raise the income base, supporting a materially higher baseline DPU for the years ahead.
On the negative side, 1H2026 saw gross revenue fall 1.6% to S$77.1 million and NPI ease 2.0% to S$72.4 million. This counterintuitive result — growing DPU despite declining revenue — reflects two factors: the higher Singapore minimum rents more than offset a weaker contribution from Japan (discussed below), and a one-time French tax provision recorded in 1H2025 was absent in 1H2026, boosting distributable income by a one-off amount. Distributable income for the period was S$57.2 million.
Additionally, the Board approved a Distribution Reinvestment Plan (DRP) for 1H2026, issuing new units at approximately a 2% discount to the VWAP for unitholders who elect to receive additional units rather than cash. This is standard practice for C2PU and does not signal any financial stress.
DPU History 2021–2026
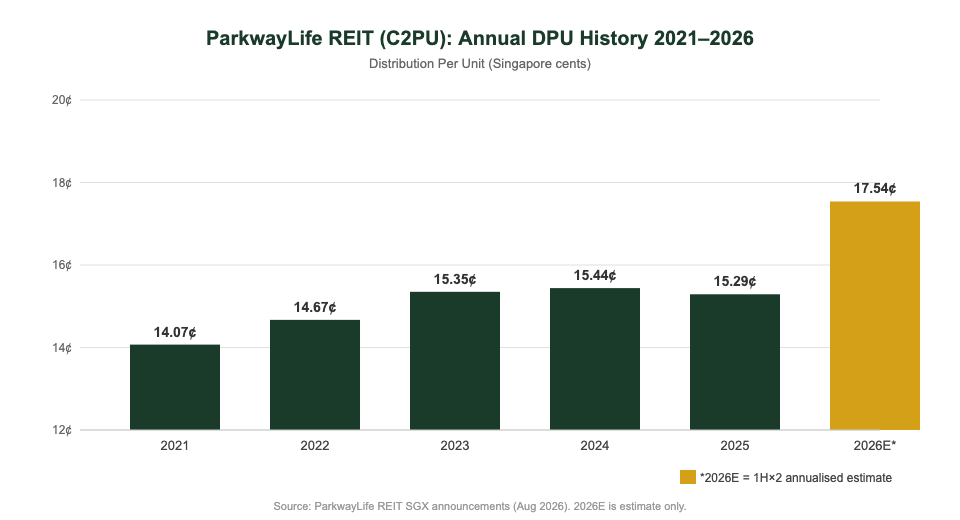
ParkwayLife REIT has delivered consistent dividend growth over the past five years, making it one of the rare S-REITs with a near-unbroken upward DPU trajectory. The table below summarises the full-year DPU for each calendar year and the half-year figures for 2025 and 2026.
| Period | DPU (Singapore cents) | YoY Change | Key Driver |
|---|---|---|---|
| FY2021 | 14.07¢ | +2.0% | Post-COVID healthcare recovery |
| FY2022 | 14.67¢ | +4.3% | Singapore hospital rent escalation |
| FY2023 | 15.35¢ | +4.6% | Rent step-ups + Japan occupancy growth |
| FY2024 | 15.44¢ | +0.6% | JPY headwinds partially offset growth |
| FY2025 (Full Year) | 15.29¢ | -1.0% | JPY weakness; one-time France provision |
| 1H2025 | 7.65¢ | — | Base period for 1H2026 comparison |
| 1H2026 | 8.77¢ | +14.6% | SG hospital rent reset (+24.3%) |
| FY2026E (annualised) | ~17.54¢ | ~+14.7% | Estimate only; 2H2026 not yet announced |
Source: ParkwayLife REIT SGX announcements and quarterly results. FY2026E is an estimate extrapolated from 1H2026 DPU × 2 — not a company forecast. Past DPU is not a guarantee of future distributions.
Singapore Hospital Portfolio: The Income Engine
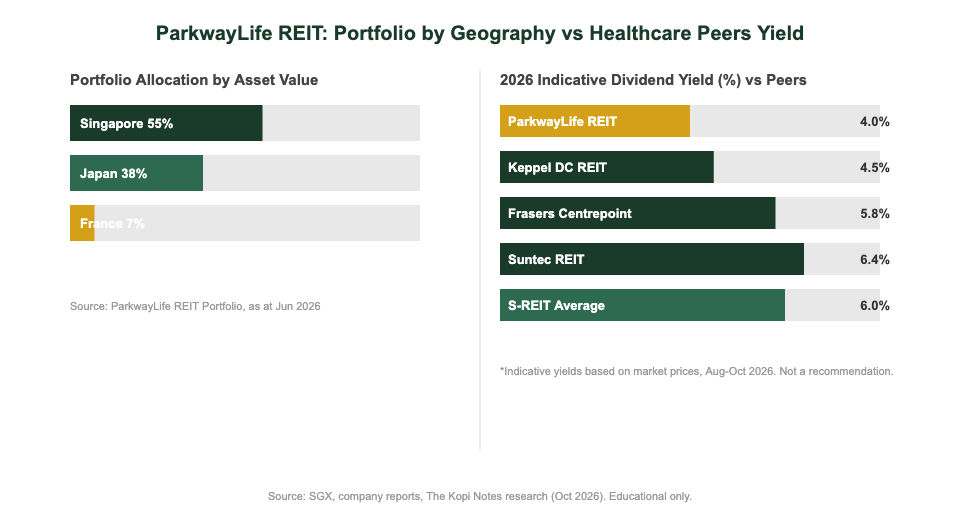
Although Singapore contributes only three properties out of 73, it accounts for approximately 55% of portfolio value and the vast majority of distributable income. This concentration is the REIT’s most important structural feature. The three hospitals — Mount Elizabeth (Orchard and Novena campuses), Gleneagles Hospital, and Parkway East Hospital — are anchored by Singapore’s best-known private hospital operator, IHH Healthcare, which is also the REIT’s parent company.
The Singapore master leases are structured as follows:
- Minimum Guaranteed Rent (MGR): A fixed floor rent that resets periodically using a CPI-linked formula. This ensures distributions never drop below a defined minimum regardless of hospital performance.
- Variable Rent: A percentage of each hospital’s gross operating revenue above the MGR threshold, providing upside when private hospital patient volumes and revenue grow.
- Long tenure: The leases are structured for the very long term, effectively providing income visibility that most REITs cannot match.
The FY2026 rent reset — a 24.3% step-up in the MGR — reflects cumulative CPI growth since the previous reset. At a portfolio level, a Singapore investor holding 10,000 units at S$4.15 per unit (S$41,500 invested) would receive approximately S$877 from the 1H2026 distribution alone, annualising to around S$1,660 per year at current run-rate. This compares with the S$765 the same holding would have generated from 1H2025, illustrating the real-world impact of the rent reset. While this jump is exceptional and not expected to repeat at the same magnitude, the permanently higher income base is a durable benefit.
Japan & France: Diversification and Risks
Japan makes up approximately 38% of portfolio value and includes 69 nursing homes and long-term care facilities, almost all leased to Japanese healthcare operators. The Japan portfolio provides sector diversification but introduces currency risk. ParkwayLife REIT reports in SGD, and the Japanese Yen (JPY) depreciation in recent years has meaningfully reduced the SGD-translated income contribution from Japan, offsetting what are otherwise stable and growing yen-denominated rents.
In 1H2026, Japan portfolio occupancy stood at 94.3%. The manager divested one Japanese nursing home for S$9.4 million — approximately 5% above its independent valuation — reflecting the continuing attractiveness of Japanese aged-care real estate to buyers even as the JPY is weak. The manager has stated it would continue selectively recycling capital from Japan into higher-yield opportunities, though the pace of divestment has been measured rather than aggressive.
France (approximately 7% of portfolio value) consists of two nursing homes operated under long-term leases with contractual step-ups. The France contribution benefited 1H2026 from the absence of a one-off tax provision that was recognised in 1H2025, boosting distributable income on a comparative basis. Underlying, France is a stable but small contributor.
For Singapore retail investors focused purely on retirement income planning, the key takeaway is that Japan currency risk is a structural headwind that has already been partially “priced in” to the REIT’s current valuation. Whether JPY recovers or weakens further will be a swing factor for total distributions in 2H2026 and beyond.
Is ParkwayLife REIT Worth Buying in 2026?
ParkwayLife REIT occupies a unique position in the S-REIT universe: it is the most defensive REIT in Singapore by lease structure, but also one of the lowest-yielding. Investors who buy C2PU are paying a premium for certainty — minimum guaranteed rent, essential healthcare assets, and an institutional-grade operator as anchor tenant. Whether that premium is appropriate depends on each investor’s portfolio objectives.
Yield Comparison
At ~4.0% trailing yield, C2PU offers significantly less income per dollar invested than the average S-REIT (approximately 6.0%). It also offers less than most individual industrial REITs like Keppel DC REIT or Frasers Centrepoint Trust. However, unlike those REITs, C2PU’s income is underpinned by minimum rent guarantees from hospitals that cannot simply close or relocate.
Valuation Metrics
| Metric | C2PU (ParkwayLife) | S-REIT Sector Avg |
|---|---|---|
| Trailing Dividend Yield | ~4.0% | ~6.0% |
| Price-to-Book (P/B) | ~1.6x | ~0.9x (average) |
| Gearing Ratio | ~35–36% | ~38–42% |
| DPU Growth (1H2026) | +14.6% | Mixed; most REITs flat or modest |
| Lease Structure | MGR floor + variable | Mostly market-rate leases |
Source: SGX, company reports, The Kopi Notes estimates (Oct 2026). Not investment advice.
C2PU trades at a substantial premium to book value (~1.6x P/B), compared with the S-REIT sector average of around 0.9x. This premium is structural and persistent — the market has long valued healthcare REITs more highly than their industrial or retail counterparts because of the certainty of income. Investors comparing C2PU to the broader best S-REITs in Singapore should factor in that a lower yield with minimum guarantees may be more appropriate for capital preservation goals, while higher-yielding REITs carry more income volatility risk.
For those using CPF investment strategy to hold REITs within their CPF accounts, ParkwayLife REIT is CPF-investible under the CPF Investment Scheme (CPFIS) as a SGX-listed REIT.
How to Buy ParkwayLife REIT (C2PU) in Singapore
C2PU units are traded on the Singapore Exchange (SGX) in board lots of 100 units. At ~S$4.15 per unit, a single board lot represents approximately S$415 — among the higher per-lot entry costs for S-REITs, but well within reach for most retail investors.
Recommended Brokers
Interactive Brokers (IBKR): Best for active traders and larger portfolios. SGX trade commission is USD 1.50 minimum, with very competitive currency conversion rates. If you sign up using the moomoo Singapore review for an alternative, note IBKR referral code jianxiong368 offers fee rebates for new accounts.
Syfe Brokerage: Simplest interface for beginners. Zero commission on SGX trades for qualifying accounts. Use the Syfe referral code SRPRFFFCD for account opening bonuses (terms apply).
FSMOne: Good for SRS (Supplementary Retirement Scheme) investing. FSMOne allows you to buy SGX REITs using SRS funds, making C2PU’s 4% yield SRS-tax-advantaged. FSMOne referral code P0544985 may provide a fee credit on your first trade (subject to eligibility).
Endowus: Primarily a fund platform, but Endowus also allows SGX stock investing. The Endowus referral code 2V343 provides an access fee waiver for new clients.
SRS and CPF
ParkwayLife REIT is investible under the SRS (Supplementary Retirement Scheme) and CPFIS (Ordinary Account). Buying a yield asset like C2PU within your SRS account means the ~4% distributions compound tax-deferred until retirement withdrawal — effectively increasing your net yield over long holding periods. Investors planning ahead can use the Singapore retirement calculator to model the impact of REIT income on their retirement projections.
Frequently Asked Questions
What is ParkwayLife REIT's dividend for 2026?
Why is ParkwayLife REIT's yield lower than other S-REITs?
Is ParkwayLife REIT's dividend sustainable?
How does ParkwayLife REIT compare to other healthcare REITs globally?
Can I invest in ParkwayLife REIT using CPF or SRS?
What are the main risks of investing in ParkwayLife REIT?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.