CPF Full Retirement Sum 2026: S$220,400 Explained — Cohorts, Payouts and the 2027 Rise
The CPF Full Retirement Sum (FRS) for 2026 is S$220,400. If you are turning 55 this year, this is the benchmark that determines your CPF LIFE income from age 65. Understanding the FRS — and how it relates to the Basic Retirement Sum (BRS) and Enhanced Retirement Sum (ERS) — is one of the most useful things you can do for your retirement planning. This article is a detailed look at the numbers, what they mean for your cohort, and how to work towards them.
Read our full CPF Retirement Sum guide for a comprehensive overview of the BRS, FRS and ERS framework and how it has evolved since 2016.
⚡ TL;DR — Key Numbers for 2026
- FRS 2026 = S$220,400 — set at age 55, locked for your cohort
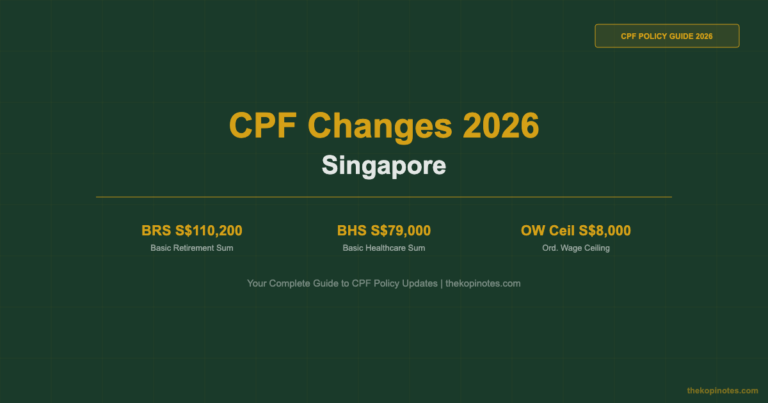
- BRS 2026 = S$110,200 (half of FRS; applies if you own a pledged/charged property)
- ERS 2026 = S$440,800 (double FRS; optional top-up for higher CPF LIFE income)
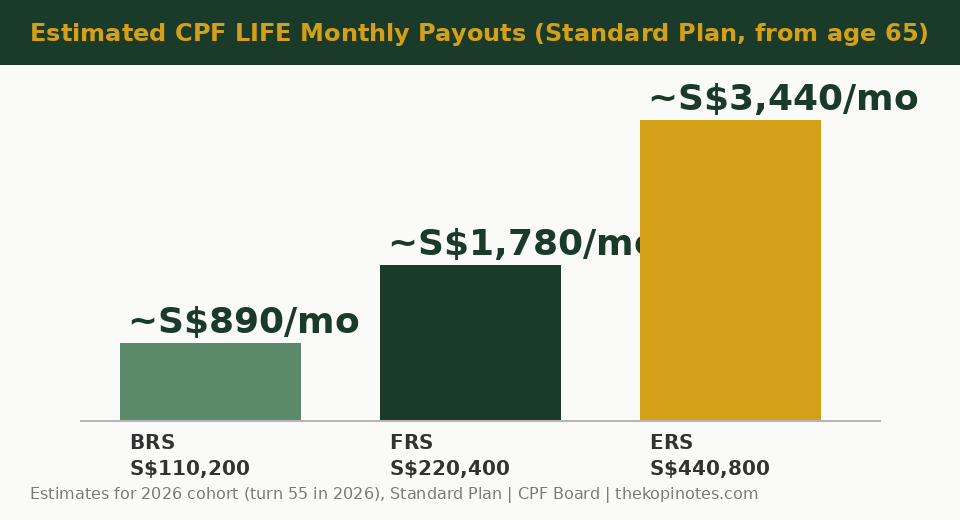
- CPF LIFE monthly payouts (Standard Plan, from 65): BRS ≈ S$890 · FRS ≈ S$1,780 · ERS ≈ S$3,440
- FRS rises every year — 2027 FRS will be S$228,200
- The retirement sum that counts is the one in the year you turn 55
What Is the Full Retirement Sum?
The Full Retirement Sum is the target balance in your CPF Retirement Account (RA) at age 55. When you turn 55, CPF Board creates your RA and transfers funds from your Special Account (SA) and then Ordinary Account (OA) until the prevailing retirement sum is reached — or until those accounts are exhausted.
Once the RA is set up, the money inside it is used to join CPF LIFE at age 65 (or when you start payouts, whichever comes later), which then pays you a monthly income for life.
The critical point: the retirement sum that applies to you is fixed by the year you turn 55, not by future changes. If you turn 55 in 2026, the 2026 FRS of S$220,400 is your benchmark — even if the 2030 FRS later rises to S$260,000.
The 2026 Retirement Sum in Numbers
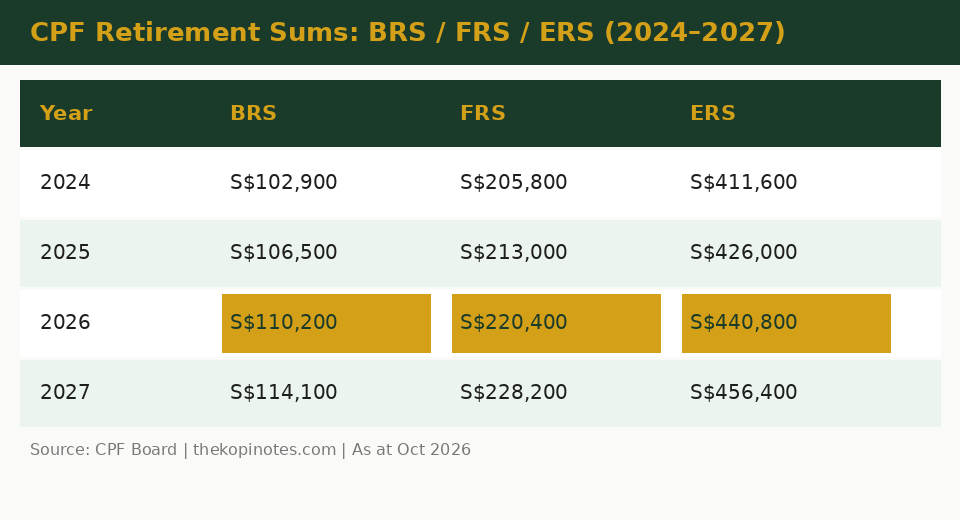
CPF Board publishes three retirement sum tiers each year. Here is the full picture from 2024 through 2027.
| Year (turn 55) | BRS | FRS | ERS |
|---|---|---|---|
| 2024 | S$102,900 | S$205,800 | S$411,600 |
| 2025 | S$106,500 | S$213,000 | S$426,000 |
| 2026 ← this year | S$110,200 | S$220,400 | S$440,800 |
| 2027 | S$114,100 | S$228,200 | S$456,400 |
Source: CPF Board. ERS = 2× FRS; BRS = 0.5× FRS. Figures confirmed at cpf.gov.sg.
Why Does the FRS Rise Every Year?
CPF Board increases the retirement sums annually to keep pace with wage growth and inflation. The government has stated that increases will be roughly in line with long-run core inflation, which has generally been 3–4% per year in recent years. This means S$220,400 in 2026 buys roughly the same standard of retirement as S$205,800 did in 2024.
The year-on-year jumps from 2026 to 2027 — FRS rising S$7,800, BRS rising S$3,900 — reflect this 3.5% annual adjustment schedule.
BRS vs FRS vs ERS: Which Applies to You?
Whether BRS, FRS or ERS applies depends primarily on your property situation at age 55.
| Retirement Sum | When it applies | 2026 Amount |
|---|---|---|
| BRS — Basic | You own a property and pledge it (or charge it) to CPF | S$110,200 |
| FRS — Full | Default if you do not pledge property; or if you prefer not to | S$220,400 |
| ERS — Enhanced | Optional top-up; you voluntarily put more into your RA up to this level | S$440,800 |
Read our detailed article on the Enhanced Retirement Sum if you are considering topping up to ERS level.
Estimated CPF LIFE Payouts at Each Level
Once your RA money enters CPF LIFE, you receive a monthly payout for life from age 65. The amounts below are estimates for the 2026 cohort (those turning 55 in 2026) under the Standard Plan:
| Retirement Sum | RA Balance at 55 | Est. Monthly Payout (from 65) |
|---|---|---|
| BRS | S$110,200 | ≈ S$890 |
| FRS ← most common | S$220,400 | ≈ S$1,780 |
| ERS | S$440,800 | ≈ S$3,440 |
Estimates only. Actual payouts depend on CPF LIFE interest crediting, plan choice, and the year payouts begin. Source: CPF Board projections.
Worked Example: Turning 55 in 2026
Let’s say you are turning 55 in October 2026 and your CPF balances just before your 55th birthday are:
| Account | Balance |
|---|---|
| Special Account (SA) | S$190,000 |
| Ordinary Account (OA) | S$80,000 |
| Total CPF | S$270,000 |
What happens at 55:
- CPF creates your Retirement Account (RA).
- S$190,000 from SA is transferred to RA first.
- Another S$30,400 from OA is transferred to RA to reach the FRS of S$220,400.
- The remaining S$49,600 stays in OA — you can withdraw it immediately or leave it to earn 2.5% p.a.
At 65, assuming steady CPF LIFE crediting, your RA would have grown to approximately S$310,000–S$330,000, and you would receive roughly S$1,780–S$1,950/month for life under the Standard Plan.
Are You on Track? A Quick Sense Check
A rough way to assess your position: divide the 2026 FRS of S$220,400 by your number of working years remaining, and compare it to your current combined SA + OA.
For example, if you are 45 years old in 2026 with S$100,000 in SA+OA today, you have roughly 10 years to bridge a gap of around S$120,400 — or about S$12,000/year in additional CPF savings and interest. This is achievable for most consistent contributors, especially as SA earns 4% p.a. interest.
Use our CPF Retirement Sum Calculator to project your own balance at 55 based on your current accounts and contribution rate.
How to Grow Your CPF Towards the FRS
There are several ways to build your CPF RA balance towards or beyond the FRS:
1. Regular CPF contributions. If you are employed, your employer and you contribute automatically — 37% of wages if you are under 55 (employee 20%, employer 17%). This flows primarily into OA and SA, compounding at 2.5%–4% p.a.
2. Voluntary CPF top-ups (RSTU). Under the Retirement Sum Topping-Up Scheme, you can top up your SA (before 55) or RA (after 55) with cash or CPF transfer from a family member. Top-ups receive no-withdrawal treatment, but the SA/RA 4% interest accelerates growth significantly. You may also qualify for tax relief of up to S$8,000 per year for your own top-ups.
3. SA shielding (before 55). Because CPF first fills your RA from SA, some members invest their SA funds in CPF-approved instruments before turning 55, then liquidate after the RA is formed — preserving more in the higher-interest SA. This strategy has nuances and is subject to CPF Board policy review; seek professional advice if considering it.
4. Voluntary housing refund. If you used OA money to pay for your HDB flat, voluntarily refunding that principal (with accrued interest) back into OA once you sell or downgrade can substantially boost your CPF balances before 55.
Frequently Asked Questions
What is the CPF Full Retirement Sum for 2026?
How much CPF LIFE income does the FRS 2026 give?
Will the retirement sum that applies to me change if I turn 55 in 2027?
Can I withdraw CPF at 55 if I have not reached the FRS?
Is the FRS the same as the Medisave Required Amount?
Does topping up to ERS make sense?
When is the 2027 FRS expected to be announced?
Related Tools & Guides
- 📊 CPF Retirement Sum Calculator — project your SA+OA balance at 55
- 📘 CPF Retirement Sum Guide — BRS, FRS and ERS framework explained
- 📗 Enhanced Retirement Sum — is topping up to ERS worth it?
- 📖 CPF LIFE Complete Guide — Standard, Basic and Escalating plans compared
Wrapping Up
The CPF Full Retirement Sum of S$220,400 in 2026 is the benchmark you need if you are turning 55 this year. It determines how much of your CPF is set aside in your Retirement Account, and ultimately how much CPF LIFE income you will receive from age 65. Whether you are aiming to hit the FRS, settle at the BRS with a pledged property, or go further to the ERS, the earlier you understand these numbers, the more time you have to take meaningful action.
For the full framework — including how the retirement sums have evolved since 2016 and what the CPF LIFE plans actually pay — see our CPF Retirement Sum guide.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment or legal advice. Retirement sum figures and CPF LIFE estimates are sourced from CPF Board and are correct as at October 2026. Individual CPF circumstances vary. Please consult a licensed financial adviser before making retirement planning decisions.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.