HOME → GUIDES → INSURANCE
Insurance in Singapore 2026: The Complete Guide
Your authoritative resource for understanding life insurance and investment insurance in Singapore — data-driven analysis, not sales pitches.
Last updated: May 2026 · 15 min read · By The Kopi Notes
📍 Start Here
New to insurance? These are the guides our readers find most useful.
What This Guide Covers
Insurance in Singapore falls into two broad categories that serve fundamentally different purposes. Life insurance — including term life, whole life, and universal life — exists to protect your family financially if you die or become permanently disabled. Investment insurance — including endowment plans and investment-linked policies (ILPs) — combines a smaller protection element with savings or investment components.
The Monetary Authority of Singapore (MAS) regulates all 28 licensed life insurers operating here. As at 2026, Singaporeans can also purchase Direct Purchase Insurance (DPI) through compareFIRST.sg without going through an agent — often at lower premiums.
This hub page provides a high-level overview of both categories and helps you navigate to the detailed guides for each insurance type. We focus on data-driven comparisons, real cost calculations, and practical decision frameworks — not product recommendations.
Not financial advice. All figures are for educational reference only. Data as at May 2026 unless noted.
Insurance Types at a Glance
Life Insurance
Life insurance protects your family’s finances if you die or become permanently disabled. The core question isn’t whether you need it — if anyone depends on your income, you do. The question is what type and how much. Term life gives you the most coverage per dollar. Whole life adds a forced savings component at 5–10x the cost. Universal life offers flexibility but complexity.
Our life insurance guide covers the term vs whole life decision, how to calculate your coverage needs (typically 9–12x annual income), provider comparisons with actual premium quotes, and the DPI option that lets you skip agents entirely.
Investment Insurance
Investment insurance products — ILPs and endowment plans — combine protection with wealth accumulation. The trade-off: higher fees than direct investing, surrender penalties if you exit early, and (for ILPs) market-dependent returns without the cost efficiency of index funds. Endowments offer some guarantees but typically deliver 2–3% p.a. net returns — below what a simple bond portfolio achieves.
Our investment insurance guide breaks down the real costs (including distribution charges, fund management fees, and insurance charges), compares projected returns against ETF and robo-advisor alternatives, and explains the specific scenarios where these products might still make sense.
Which Insurance Type Is Right for You?
Decision Framework
Do you have dependants (spouse, children, elderly parents)?
→ Yes: You need life insurance. Start with term life for maximum coverage per dollar.
Do you want forced savings with guaranteed returns?
→ Consider endowment plans — but compare against SSBs and fixed deposits first.
Do you want market-linked returns with insurance coverage?
→ Read our ILP guide — in most cases, term life + ETFs delivers better outcomes.
Do you need lifetime coverage (e.g., estate planning)?
→ Whole life or universal life may be appropriate. See our life insurance guide.
Are you single with no dependants?
→ You likely don’t need life insurance yet. Focus on health insurance (MediShield Life + IP) and investing directly.
All Insurance Articles
Browse all our insurance guides and analysis.
Insurance Articles
Guides on life insurance, investment insurance, endowment plans, ILPs, and more for Singapore residents.
Compare guaranteed returns, liquidity and risk — data-driven guide for Singapore investors.
Read article
Should you buy whole life or term life insurance in Singapore? The answer depends on your life stage. This 2026 guide maps the decision across five stages — from fresh graduate to pre-retiree — with coverage benchmarks, premium comparisons, and a clear action plan.
Read article
Should Singapore retirees put money in endowment plans? We compare endowment plans against CPF LIFE and Singapore Savings Bonds, with verified return data and a clear verdict for retirees aged 55–75.
Read article
LIFE INSURANCE · SINGAPORE 2026
Read article
Should 25–35 year olds in Singapore buy an endowment plan in 2026? We compare guaranteed returns, surrender value lock-in, and opportunity cost versus CPF, SSB, and ETFs — with a verdict for every scenario.
Read article
HDB owners in Singapore are automatically covered by the Home Protection Scheme (HPS) for their outstanding mortgage — but HPS only pays the bank, not your family.
Read article
SSBs offer full flexibility with ~2.70% yields; endowment plans deliver higher guaranteed IRRs (3.0–3.5%) for committed 5–10 year goals. Here's the complete side-by-side comparison for Singapore savers in 2026.
Read article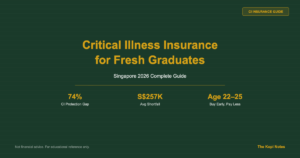
What your employer's group policy won't tell you — and why buying early changes everything.
Read article
Use an endowment plan to supplement your CPF Life payout and close the Singapore retirement income gap. 2026 guide with CPF Life figures, laddering strategies, and worked examples.
Read article
Everything about coverage as a single — DPS limits, the 9× income rule, and why waiting costs more than you think.
Read article
Endowment plan payouts in Singapore are not subject to income tax. Under IRAS rules, maturity proceeds, surrender values, and bonuses from participating endowment policies are…
Read article
Critical illness insurance for seniors in Singapore is still available after 60, though premiums rise sharply and options narrow. Find out whether CI cover is worth it after retirement, how much coverage retirees actually need, and what to do if you want to buy CI for elderly parents.
Read article
Should Singapore couples buy a joint endowment plan or separate policies? We compare SDIC protection, CPF OA usage, nomination rights, and projected returns at LIA illustration rates to help you decide.
Read article
As a parent, the instinct is to protect your child from every risk. But does that extend to critical illness (CI) insurance? In this guide, we cut through the marketing noise to…
Read article
A data-backed breakdown of your three CPF OA options — stay put at 2.5%, invest via a CPFIS endowment plan, or go into the market.
Read article
A practical guide to how term life insurance payouts work in Singapore — the sum assured, what triggers it, what's excluded, and how nomination determines who actually receives the money.
Read article
An endowment plan's cash value is the amount your policy has accumulated at any point before maturity — made up of a guaranteed portion and, on participating plans, non-guaranteed bonuses.
Read article
In Singapore, couples cannot purchase a joint critical illness insurance policy — every CI plan is individually underwritten and tied to one life assured.
Read article
An endowment plan is a life insurance policy in Singapore that combines a savings component with a death benefit. You pay regular or single premiums over a fixed term — typically 10 to 25 years — and receive a lump-sum payout at maturity.
Read article
Learn about Singapore life insurance in 2026 — term, whole life, endowment, and ILP plans explained, with premium comparisons, coverage guidelines, and how to choose the right policy.
Read article
Everything you need to know about the PPF Scheme caps, what is and is not covered, and how to check your real protection level.
Read article
The LIA-recommended benchmark is 5× your annual income — roughly S$316,000 for a median earner — yet the average Singaporean holds only S$60,000.
Read article
Category: Investment Insurance · Updated November 2026 · 10 min read
Read article
No employer benefits, no group cover — here's exactly how to protect yourself and your family.
Read article
The free look period for endowment plans in Singapore is a mandatory 14-day window to cancel and get a full refund. After Day 14, surrender charges of 15–100% apply. Here's what to review, and how to cancel correctly.
Read article
Critical illness insurance pays a lump sum on diagnosis. Health insurance reimburses hospital bills. In Singapore, you need both — they cover completely different financial risks. Here is what each covers and which to buy first.
Read article
Disclosure: This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial adviser before making insurance decisions. Data verified as at 30 October 2026.
Read article
CI insurance in Singapore covers 37 conditions but every policy has exclusions. Learn about pre-existing conditions, waiting periods (30-90 days), survival periods (14-30 days), and other exclusions that can void your claim.
Read article
CI insurance in Singapore covers 37 conditions but every policy has exclusions. Learn about pre-existing conditions, waiting periods (30-90 days), survival periods (14-30 days), and other exclusions that can void your claim.
Read article
A data-driven guide for Singapore investors — break-even timelines, IRR calculations, and when to exit early.
Read article
A practical step-by-step guide for policyholders and their families
Read article
Learn how endowment plan nomination works in Singapore 2026 — compare Statutory Nomination (Section 49M) vs Trust Nomination (Section 73), how to protect your payout, and what happens without one.
Read article
Early stage vs late stage critical illness insurance Singapore: which do you actually need? Covers LIA 2024 standard CI, early/multi-pay CI differences, premium cost comparison, and who needs early CI coverage in 2026.
Read article
INVESTMENT INSURANCE GUIDE
Read article
Your age is the single biggest factor affecting CI insurance cost and value — understanding the sweet spot can save you thousands.
Read article
Which policy covers your mortgage best? A plain-English comparison for Singapore homeowners.
Read article
Learn how endowment plan partial withdrawal works in Singapore 2026 — when you can access cash early, the impact on sum assured, and how it compares to a policy loan or full surrender.
Read article
Most expats at Singapore international schools are NOT automatically covered by DPS — here's what that means for you.
Read article
A complete guide to policy loans on endowment plans — interest rates, lapse risks, and when it beats surrendering your policy.
Read article
What Income's Standard travel plans cover, what they cost, and how to tell whether a yearly plan beats buying per trip, flash sales included.
Read article
No sick pay. No group insurance. If you freelance or run your own business in Singapore, a serious illness diagnosis could cost you everything — unless you plan ahead.
Read article
Comparing guaranteed-return insurance plans with low-cost global index ETFs — the numbers may surprise you.
Read article
Critical illness insurance premiums in Singapore range from approximately S$912 to over S$3,100 per year for a 30-year-old male non-smoker with S$100,000 sum assured — with the wide range explained by plan type, not just insurer.
Read article
Updated: October 2026 | 8 min read | Investment Insurance
Read article
37 LIA Conditions, Exclusions, Claims Process & Top Plans
Read article
A data-driven comparison of guaranteed returns, liquidity, and real SGD earnings — so you can decide where to park your savings in 2026.
Read article
DPS Singapore premiums range from S$18/year at age 34 and below to S$298/year at 55–64. This 2026 breakdown shows whether keeping the Dependants' Protection Scheme is worth it at every age bracket.
Read article
In Singapore, endowment plans currently offer 3.20%–4.20% p.a. with lock-up periods of 2–25 years, while money market funds (MMFs) yield approximately 1.04%–1.64% p.a. with full liquidity.
Read article
A step-by-step formula to calculate your ideal CI sum assured — income replacement, medical costs, and the LIA framework explained.
Read article
A complete Singapore comparison — accumulation vs income, payout scenarios, flexibility, and our verdict on which suits your retirement stage.
Read article
MoneySense and the LIA recommend at least 9× your annual income — here is how to calculate your exact coverage target.
Read article
Par endowment plans share insurer investment profits as non-guaranteed bonuses; non-par plans lock in a fixed guaranteed rate. Here's how to choose the right structure for your savings goals in Singapore 2026.
Read article
Choosing between a CI rider and a standalone critical illness plan in Singapore? This 2026 guide explains the key differences, trade-offs, and which option suits your protection needs.
Read article
Last updated: 17 Oct 2026 | Category: Investment Insurance | 8 min read
Read article
CPF mandatory life insurance for HDB flat owners — how it works, what it covers, and when you might opt out for a private alternative.
Read article
Key person insurance in Singapore is a term life policy taken out by a business on a director, partner, or critical employee whose death or permanent disability would cause serious financial loss.
Read article
Singapore endowment plan bonus rates explained: how reversionary bonuses (guaranteed once declared) and terminal bonuses (non-guaranteed) work, plus LIA illustration caps of 4.25% and 3.00% for 2026.
Read article
CI insurance pays a lump sum on diagnosis of 37 LIA-standardised conditions. DI insurance replaces up to 75% of your monthly salary (MAS cap) when you cannot work. Here is how to decide which Singapore workers need — and why most need both.
Read article
An honest analysis of education endowment plans — guaranteed returns, real costs, and smarter alternatives for Singapore parents.
Read article
In Singapore, the Life Insurance Association (LIA) recommends a minimum of 4× your annual income in critical illness (CI) insurance coverage.
Read article
Not all returns from a Singapore endowment plan are created equal — only one portion is contractually promised.
Read article
Critical illness insurance for young adults in Singapore is one of the most cost-effective financial decisions you can make in your 20s or 30s.
Read article
A plain-language comparison of Singapore's two most popular savings-linked insurance products — covering guaranteed returns, premiums, flexibility, and who each product really suits.
Read article
How much coverage does your family really need — and which policy fits your budget?
Read article
A data-driven comparison of guaranteed returns vs dividend yields — for Singapore investors seeking passive income without the guesswork.
Read article
CI insurance for retirees in Singapore pays a lump sum upon diagnosis of cancer, heart attack, or stroke — protecting your retirement savings when you have no salary to fall back on. 2026 guide.
Read article
A data-driven comparison of two popular retirement savings tools — guaranteed returns, tax relief, flexibility, and the combination strategy that maximises both.
Read article
The Freelancer's Complete Protection Guide — Coverage, Plans & Setup
Read article
A practical guide to CPFIS-approved endowment policies, the S$20,000 investment floor rule, real return comparisons, and why most Singaporeans are better off leaving their CPF OA untouched.
Read article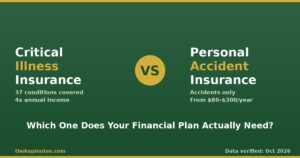
Data verified as at 8 October 2026. Sources: CPF Board (March 2026), MoneySense/MAS Basic Financial Planning Guide, Life Insurance Association (LIA) Singapore, MoneySmart 2026.
Read article
Stagger your endowment plans across multiple tenors — 2Y, 5Y, 10Y, and 20Y+ — to unlock guaranteed payouts exactly when you need them.
Read article
Women in Singapore pay 20-25% less for term life than men — but most are still underinsured. This guide covers cancer risk, maternity exclusions, coverage formulas and the best term life plans for Singapore women in 2026.
Read article
Endowment plans guarantee you 2.5–4.25% p.a. in Singapore (2026), while unit trusts offer higher historical returns of 6–12% p.a. but with full market risk and no capital protection.
Read article
The complete 2026 guide to calculating your CI coverage gap as an HDB owner — and closing it before a diagnosis forces a fire sale.
Read article
Surrendering an endowment plan early in Singapore almost always means losing money. Most par plans return zero in Year 1 and only recover your total premiums around Year 7–8 for 10-year policies.
Read article
Data verified as at 4 October 2026 · Source: CPF Board (last updated Jul 2026)
Read article
Your endowment plan just matured — what now? Compare 5 smart reinvestment options in Singapore's Q4 2026 environment, from new endowment plans and SSBs to CPF top-ups and ETFs.
Read article
A practical needs-analysis guide using the DIME method — with real premium data, a worked example for a typical Singapore family, and step-by-step buying advice.
Read article
Comparing the best education endowment plans in Singapore 2026 — POSB MyEduPlan (1.41% guaranteed), OCBC MaxEdu Goal (135% sum assured), and Singlife Choice Saver (up to 4.25% illustrated) — against T-bills and CPF.
Read article
A complete guide to critical illness insurance claims in Singapore — the 37 covered conditions, step-by-step claims process, documents needed, and how to avoid rejection.
Read article
Insurance Plans · SSB · T-Bills · Fixed Deposits · CPF — Compared
Read article
Your plain-English guide to term life insurance meaning, how it works in Singapore, how much cover you need, and how to choose the right policy — verified October 2026.
Read article
An investment-linked policy (ILP) is a Singapore life insurance product that bundles death coverage with unit-linked fund investments — sold by insurers like AIA, Prudential, and Manulife.
Read article
MediShield Life covers your hospital bills. Critical illness insurance pays a lump sum directly to you upon diagnosis of a covered condition — regardless of what your medical bills cost.
Read article
After the Sep 2026 Fed rate hike, Singapore endowment plans offer up to 3.60% p.a. guaranteed. Learn how to ladder across tenors to maximise Q4 returns while maintaining flexibility.
Read article
Compare premiums by age — and see how much delaying really costs you.
Read article
Compare guaranteed rates, lock-in periods, and flexibility to find the right fit for your money.
Read article
With Q2 2026 retrenchments at a 4-year high, learn how to protect your CI coverage during a job gap — and which plans waive premiums when you lose your job.
Read article
Data verified as at 28 September 2026. Rates sourced from MAS auction results, MAS SSB announcements, and publicly available insurer product sheets. Specific plan availability and rates should be confirmed directly with insurers before committing.
Read article
LIFE INSURANCE GUIDE • DATA VERIFIED 27 SEP 2026
Read article
Data verified as at 27 September 2026 | Investment Insurance
Read article
Data verified as at 26 Sep 2026 | Life Insurance | 8 min read
Read article
If you have an endowment plan or whole life policy in Singapore, your returns are likely linked to a participating fund — commonly called a par fund. Understanding how par funds work is essential before you commit to a long-term policy.
Read article
No employer group CI. No paid sick leave. No employer CPF during recovery. Here is how to close all three gaps.
Read article
Choosing a savings plan in Singapore comes down to one question: lump sum now, or monthly contributions over time? Both structures build your wealth with insurance protection —…
Read article
Term life insurance laddering is a strategy where you buy two or three smaller policies with different coverage periods — instead of one large single policy.
Read article
Data verified as at 24 September 2026. Source: DBS Bank (dbs.com.sg). This article is for informational purposes only and does not constitute financial advice.
Read article
Self-employed Singaporeans have no employer sick leave — DI insurance fills the gap. Learn the MAS 75% cap, best deferment periods for freelancers, and how AIA, Singlife, and GE plans compare in 2026.
Read article
Par fund vs non-par endowment plan in Singapore 2026: compare guaranteed yields vs participating fund returns, with a side-by-side table and real plan examples to help you decide which pays more.
Read article
Whole life insurance premiums cost 6-7x more than term life. In a high-rate environment, the opportunity cost of that gap has never been higher. This article breaks down the real numbers.
Read article
Traded endowment policies (TEPs) let you buy second-hand endowment plans in Singapore. Understand how they work, why MAS doesn't regulate TEP intermediaries, and whether they make sense in 2026.
Read article
Critical illness insurance pays you a tax-free lump sum if you are diagnosed with cancer, heart attack, stroke, or any of 36 other major illnesses under the LIA CI Framework 2024.
Read article
The Fed hiked +25bps in September 2026. Here is how to choose between 1-year, 2-year, and 3-year endowment plans for Q4 2026 — tenor decision framework for Singapore savers.
Read article
The waiting period on your disability income insurance is the one variable that can cut your annual premium by 30 to 45 percent — or leave you scrambling for cash when you need it most.
Read article
A plain-English comparison of returns, fees, and risk — updated after the Fed's September 2026 +25bps hike
Read article
Most CI insurance in Singapore has a 90-day waiting period. Claims for cancer, heart attack, or stroke within the first 90 days will be rejected. Here is what to know before you buy.
Read article
Updated September 2026
Read article
Coverage from S$413/yr · Fed at 3.75–4.00% · Compare AIA, Prudential, Singlife, FWD
Read article
The Fed raised rates by 25 basis points to 3.75%–4.00% on 17 September 2026 — its first hike since 2023. For Singapore endowment plan buyers, this is a pivotal moment. Existing tranches are closing.
Read article
With the Fed at 3.75–4.00%, the buy-term-invest-the-rest math now strongly favours term + standalone CI over whole life CI riders. Here’s what changed and how to decide.
Read article
The US Federal Reserve raised its benchmark rate by 25 basis points to 3.75–4.00% on 17 September 2026 — the first rate hike since 2023. For Singapore savers holding endowment plans, T-bills, and fixed deposits, this changes the calculus.
Read article
6 clauses that can void your payout — and how to make sure your family is actually protected.
Read article
Rates, How It Works and FOMC Timing — Updated September 2026
Read article
Critical illness insurance claims in Singapore get rejected for 6 key reasons. Learn how to avoid CI claim rejection with this evidence-based guide for Singapore policyholders.
Read article
INVESTMENT INSURANCE · 15 SEPTEMBER 2026
Read article
Income vs Singlife vs Great Eastern — Which Tops Up Your Payout?
Read article
Multi-pay CI insurance pays out for each new critical illness diagnosis — not just the first. Compare top Singapore plans from Singlife, Tokio Marine and AIA, and find out if paying 30–50% more is worth it for your situation.
Read article
Which Singapore endowment plans are still accepting applications, what guaranteed yields they offer right now, and how the Federal Reserve’s September 17–18 meeting affects your decision.
Read article
Your base term life plan covers death and terminal illness. Riders extend that coverage for a price. Some are worth every cent. Others duplicate what you already have. This guide covers the five most common riders in Singapore and when to add them.
Read article
With the Fed meeting on 17-18 September 2026, here is what falling rates mean for your endowment plan decision.
Read article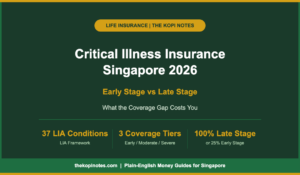
Standard CI plans only pay for late-stage diagnoses. Early stage CI covers cancer at Stage 1, carcinoma in situ, and mild heart attacks. Here is what the coverage gap means in practice.
Read article
A Singapore insurance savings plan is a hybrid financial product that combines life insurance cover with a structured savings component.
Read article
Data verified as at 9 Sep 2026 | Sources: MOH, LIA
Read article
Universal Life Insurance (ULI) is a type of permanent life insurance that combines lifelong death benefit coverage with a flexible savings component. Unlike term insurance, it never expires.
Read article
Use the LIA income multiplier formula to find your exact sum assured — with worked SGD examples and 2026 premium data.
Read article
The Life Insurance Association's updated CI definitions have been in force since 1 October 2025. Here is what the 37 standardised conditions actually require for a payout — and the common reasons claims fail.
Read article
Available Plans, Rates & What You Need to Know
Read article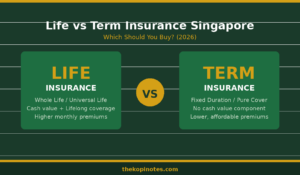
ⓘ Data verified as at 6 September 2026. Premiums and product details change — confirm with your insurer before buying.
Read article
Data verified as at 6 September 2026 | This article is for informational purposes only and does not constitute financial advice. Please consult a licensed financial adviser before making any investment decisions.
Read article
LIFE INSURANCE · 2026 GUIDE
Read article
OCBC Bank distributes three endowment insurance plans underwritten by Great Eastern Life Assurance Company Limited — an OCBC Group subsidiary and one of Singapore's oldest life insurers.
Read article
A step-by-step coverage calculator guide for Singapore residents — LIA benchmarks verified
Read article
Updated September 2026 · 12 min read · Covers real numbers, fee drag, and a 20-year projection
Read article
Your complete guide to all four types — and which combination you actually need.
Read article
Many Singapore investors search for a “UOB endowment plan” expecting to find a savings product created by United Overseas Bank.
Read article
A data-backed breakdown for Singapore policyholders
Read article
Investment Insurance Guide · 2 Sep 2026
Read article
If you pay S$1,200 a year in CI insurance premiums and expect a tax deduction at year-end, you may be in for a surprise.
Read article
An endowment plan in Singapore is a short-to-medium-term insurance savings product that pays guaranteed returns upon maturity — most run 2 to 5 years and suit lump-sum investors.
Read article
The complete guide to plugging Singapore's income protection gap — with real numbers
Read article
Your SRS cash earns just 0.05% if left uninvested. This guide compares the best SRS-eligible single-premium savings plans in Singapore for 2026 — plus how to maximise your SRS tax relief and withdrawal strategy.
Read article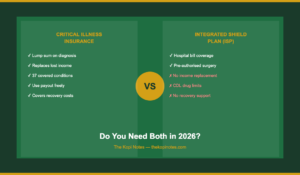
Data verified as at 30 August 2026 | Category: Life Insurance
Read article
Should you lock in a 2-year, 3-year, or 5-year endowment plan in Singapore? Compare guaranteed rates, maturity payouts, and which tenor suits your financial goals in 2026.
Read article
Data verified as at 29 August 2026. Premium figures are indicative benchmarks based on published market data — always obtain a personal quote directly from your insurer or licensed adviser before making any decision.
Read article
Singapore's benchmark interest rate SORA has fallen from nearly 3% in early 2025 to around 1.06% as of mid-2026. Yet short-term endowment plans from major insurers still offer guaranteed returns of 2.0%–2.8% p.a.
Read article
Is the Extra Premium Worth It?
Read article
Data verified as at 28 August 2026 | Category: Investment & Insurance
Read article
A plain-English guide to term life insurance riders in Singapore 2026 — CI rider, TPD, waiver of premium, disability income, and accidental death. Find out which add-ons are worth paying for.
Read article
Data verified as at 27 August 2026 — CPF rates from cpf.gov.sg, endowment yields from insurer product pages, cash management projections from platform disclosures.
Read article
LIFE INSURANCE · THE KOPI NOTES
Read article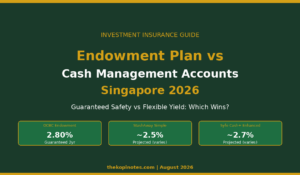
A detailed comparison of locked-in guaranteed returns vs flexible projected yields for conservative Singapore investors.
Read article
Data verified as at 25 August 2026. Term life insurance is the most cost-effective way to protect your family's financial future in Singapore — but many buyers get the sum assured wrong.
Read article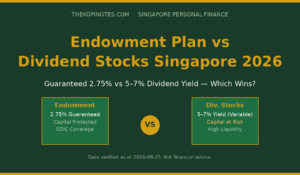
Endowment plans offer 2.75–2.80% p.a. guaranteed. Singapore blue-chip dividend stocks yield 5–7%. One protects your capital; the other can grow it — but comes with real risk.
Read article
Both promise capital protection and predictable returns. But which one actually delivers more — and which carries hidden risks? We break it down for you.
Read article
Data verified as at 23 August 2026. This article covers the LIA CI Framework 2024 changes, what the 37 standard critical illness conditions cover, and how to assess your coverage needs.
Read article
Which builds more wealth in 10 years — a guaranteed policy or a rallying precious metal?
Read article
A plain-English review of all three China Life term life plans - who can buy each one, what they cover, and where the benefit limits sit.
Read article
A side-by-side look at endowment plans and Singapore's retail corporate bonds — real coupon rates, a worked S$20,000 projection, and who each one actually suits.
Read article
A plain-English breakdown of AIA's flagship regular-premium ILP — the 3.90% p.a. supplementary charge, welcome bonuses up to 75%, and what S$1,000/month really grows into after charges.
Read article
i-Protect, i-Care & DIRECT–Term compared — sum assured, riders, real premiums, and SDIC protection
Read article
A plain-English breakdown of Manulife's flagship whole-life ILP — admin charges, welcome bonuses, and what S$800/month really grows into after fees.
Read article
HSBC Life Term Protector is HSBC Life Singapore's flagship term insurance plan, covering death and terminal illness from S$100,000 up to age 99, with a higher-tier Term Protector Prime version starting at S$2,000,000 for high-net-worth buyers.
Read article
Fees, Welcome Bonus, Loyalty Bonus and a fee-drag calculation for Singapore investors considering this whole-life ILP.
Read article
DPS is not compulsory — here's the real trade-off between cancelling it and keeping it, with 2026 premiums straight from CPF Board.
Read article
Two very different investment-linked plans under one insurer — here's which one (if either) fits your goals.
Read article
Your endowment plan's guaranteed rate never changes, but its bonus can. We trace exactly how Fed policy and Singapore bond yields flow through to your payout in 2026.
Read article
Standard CI plans only pay for major-stage cancer. Compare Income Lady 360, HSBC CritiCare for Her and AIA Glow of Life for early-stage female cancer cover in Singapore.
Read article
A side-by-side look at every savings plan Singlife sells in 2026 — what's guaranteed, what's not, and which product actually fits your goal, sourced from Singlife's own product pages.
Read article
Conversion Privilege Explained, Insurer Comparison & A Worked Example
Read article
Prudential PRUVantage Assure II reviewed: Growth/Flex account structure, Welcome Bonus up to 65%, admin charges up to 3.30% p.a., and a worked S$500/month example.
Read article
Self-employed and freelance in Singapore? Here's how much critical illness insurance you actually need, real 2026 premium ranges, and what MediSave doesn't cover.
Read article
LIA's 4.25% and 3.00% illustration rate caps explained, and how to tell your guaranteed return from a projection.
Read article
Singlife's flagship term life plan now comes in two flavours — Regular Pay and Limited Pay. Here's what each actually costs, and whether the "get your premiums back" promise is as good as it sounds.
Read article
Is DBS's digital-only, no-medical-checkup endowment plan worth locking your cash into for two years?
Read article
HPS, MRTA and level term life insurance all protect your mortgage — but they work very differently. Here's how to pick the right one.
Read articleSame S$220,400, two completely different guarantees -- we ran the actual crossover-age numbers.
Read article
If nobody relies on your income, life insurance can feel pointless. But "single" doesn't always mean "no financial risk.
Read article
A side-by-side look at endowment plans and Singapore Government Securities (SGS) bonds — with real 2026 rates, worked examples, and who each one actually suits.
Read article
Same $500 a month, two completely different paths -- we ran the actual 20-year numbers.
Read article
Documents, timelines, and payout rules straight from LIA's official claims guidelines
Read article
Both come wrapped in an insurance policy. Only one of them guarantees you anything.
Read article
7 major insurers' whole life plans compared side by side — features, riders, and the real cost vs term life, plus how LIA's illustrated rate caps affect your projected returns.
Read article
Two very different tools that get compared for the wrong reasons — here's how they actually work.
Read article
Two Singapore insurers let you get something back if you outlive your term policy — but they don't pay back the same thing. Here's the difference, with real product terms.
Read article
Endowment plans guarantee ~1.81% p.a., unit trusts offer higher potential returns with market risk. We compare fees, a S$20,000 3-year worked example, and which fits your goals.
Read article
What keeps your life insurance policy alive if you're diagnosed with a critical illness and can't pay the premiums yourself.
Read article
Guaranteed Returns vs Flexible, Liquid Growth — Which Wins for Your Idle Cash?
Read article
A plain-English guide to how TPD riders really work — the age-based definitions, the accelerated payout structure, and what it costs in 2026.
Read article
How to buy up to S$400,000 of term life cover directly from an insurer — no adviser, no commission
Read article
A side-by-side look at endowment plans against globally diversified ETFs like VWRA and CSPX — guaranteed rates, real historical returns, fees, tax, and who should pick which in 2026.
Read article
A Singapore investor's real-numbers comparison of endowment plan guaranteed returns against S-REIT dividend yields, tax treatment, and a worked S$20,000 growth scenario.
Read article
AIA's newest critical illness plan launched in May 2026 — here's what it covers, what it costs, and why it isn't open to everyone.
Read article
Comparing a guaranteed 1.81% p.a. endowment plan against Syfe and Endowus robo-advisor portfolios — fees, projected growth, and which fits your risk profile in 2026.
Read article
Singapore 2026 — the three fine-print rules that decide if your CI claim actually gets paid
Read article
High-yield savings accounts advertise up to 4.45% p.a., but most Singaporeans never hit that rate. Here's the real guaranteed-returns comparison against endowment plans in 2026.
Read article
TPD protection to age 84, four different term plans for four different budgets — here's how Singapore's largest home-grown insurer's term life lineup stacks up.
Read article
The 6-month T-bill's yield has risen for three straight auctions, hitting 1.59% p.a. on 30 July. The average Singapore endowment plan still guarantees more, at 1.81% p.a.
Read article
Your DPS baseline, the DIME method, and Singapore's S$373 billion protection gap — a step-by-step way to find your real number.
Read article
CPF’s Special/Retirement Account floor pays 4% p.a. guaranteed. The average Singapore endowment plan guarantees just 1.8%. Here’s the full breakdown — including whether you can actually use CPF to buy one.
Read article
TPD protection to age 86, renewal to 90, and a rider suite that covers early and severe-stage critical illness — here's what Etiqa's flagship term plan gets right, and where it doesn't fit.
Read article
An independent look at Singlife's newest capital-guaranteed savings plan — what it guarantees, what it doesn't, and how it fits after Secure Saver was discontinued.
Read article
GREAT Term 2's real cost vs 4 other insurers, its critical illness rider, and why Singapore's oldest life insurer isn't the cheapest — but might still be worth it.
Read article
A real 2026 premium comparison, and what actually drives the price
Read article
Guaranteed monthly or yearly payouts, plus the real 2023-2025 Par Fund return data Tokio Marine doesn't put on its own product page.
Read article
The LIA's 4x-income rule, real SGD treatment costs, and a step-by-step framework to find your number.
Read article
1.6% p.a. guaranteed over 2 years, 100% capital guarantee at maturity — but the current tranche is sold out. Here's what's inside, and what to do while you wait.
Read article
SaveForward, FlexiCash Growth, and the truth about the “10% guaranteed cash benefit” — verified against China Life’s own product pages.
Read article
LIA Singapore's Q1 2026 results reveal the highest first-quarter payout in six years — here's what it means for your coverage
Read article
Etiqa's full savings plan lineup reviewed — capital-guaranteed endowments from just $125/month, with real numbers from official product pages.
Read article
How April 2026’s Integrated Shield Plan rider overhaul shifts your out-of-pocket risk — and what it means for your critical illness coverage.
Read article
Guaranteed capital, real declared bonus rates, and what the reported Allianz sale could mean for your policy.
Read article
PRUActive Term's real cost vs 6 other insurers, its critical illness riders, and when PRUVital Cover or the DIY DIRECT plan beats it on price.
Read article
A plain-English look at AIA’s short-term guaranteed #Wealth Savvy tranches and the longer-term Smart Wealth Builder Series, with real numbers pulled straight from AIA’s own policy documents.
Read article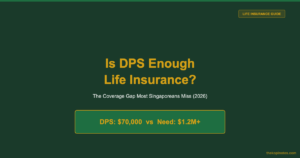
CPF's Dependants' Protection Scheme gives you free term life cover — but for most working adults, it covers only a fraction of what their family actually needs.
Read article
Guaranteed 1.70% p.a. over 3 years, a par-fund plan that locks capital after 10 years, and how both stack up against CPF, SSB and T-bills.
Read article
A plain-English look at PRUActive Protect and Prudential's five other critical illness plans — coverage, riders, and who each one actually fits.
Read article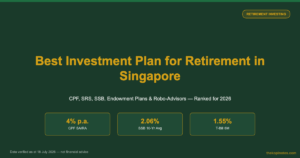
CPF, SRS, SSB, T-Bills, Endowment Plans & Robo-Advisors — Compared Side by Side
Read article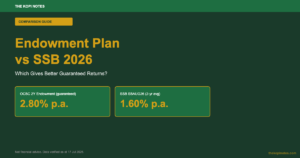
OCBC's 2-Year Endowment Plan guarantees 2.80% p.a. today. The latest Singapore Savings Bond averages just 1.60% over the same two years. Here's the full breakdown, plus the one thing the SSB does better than any endowment plan.
Read article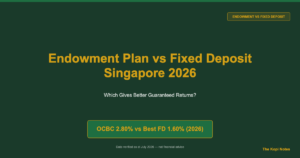
Real 2026 rates, a S$20,000 worked example, and an honest verdict on which guaranteed option actually pays more.
Read article
Real premium comparisons, the DPI shortcut, and the exact moves that lower your quote — without cutting the coverage you actually need.
Read article
Guaranteed returns, participating bonuses, fees and how Singapore's oldest insurer's endowment plans actually work
Read article
A complete breakdown of AIA's flagship term life plan — premiums, riders, AIA Vitality discounts, and how it stacks up against FWD, Singlife and Manulife.
Read article
Actual AIA, Prudential, Manulife and GreatLink fund factsheet data — plus the pricing quirk that quietly eats your first-year returns.
Read article
A 2026 employer's guide to group medical insurance in Singapore — costs, top providers, and how it fits with IRAS tax rules and MOM requirements.
Read article
Gro Cash Sure vs Gro Saver Flex Pro vs Gro Capital Ease — real payout examples, guaranteed vs non-guaranteed returns, and who each plan actually suits.
Read article
What's compulsory, what's optional, and how SME owners and HR teams should set up employee cover in 2026.
Read article
Goal 2026, IncomeGen, IncomeSecure, GrowSecure and WealthGen compared side by side — guaranteed returns, minimum premiums and who each plan suits.
Read article
INVESTMENT INSURANCE GUIDE
Read article
Manulife term life insurance in Singapore centres on the ManuProtect Term (II) — a flexible plan covering death and terminal illness for 5 to 40 years, renewable to age 85 without a medical examination.
Read article
Compare Singapore's best endowment plans in 2026 — NTUC Income, Etiqa, Manulife, AIA & GE. Returns 3.5–4.2% p.a., vs T-bills 1.50%, FD 1.45–1.60%. SRS strategy & buyer's guide.
Read article
From $16/month for $500,000 coverage — our honest assessment of FWD's term life plans, premiums, and claims service.
Read article
A practical side-by-side comparison to help you choose the right life insurance in Singapore.
Read article
Term insurance covers you for a fixed period — typically 10 to 30 years — and pays a lump sum only if you die within that term. Whole life insurance covers you for your entire life and builds a cash value you can access later.
Read article
Everything you need to know before committing your savings to OCBC's short-term endowment plan.
Read article
Most Singapore employees have group term life insurance through work — but many do not know the coverage limits, portability risks, or when they need their own individual policy.
Read article
How ILPs work, what they cost, and whether buying one makes sense for you — honest breakdown for Singapore investors.
Read article
The best savings plans in Singapore 2026 compared — endowment, CPF SA, SSB, T-Bills, robo-advisors and high-yield savings accounts. Find the right plan for your goals and risk appetite.
Read article
Your complete guide to LIA Singapore — the industry body that voices the interests of members, addresses industry issues through engagement with stakeholders, and works with members to develop guidelines and codes of practice.
Read article
An honest, data-driven look at Singlife — MAS-licensed, digitally-native, and growing fast. Here's everything Singaporeans need to know before buying a policy.
Read article
Compare the right plan for your stage of life — clear premiums, payouts, and honest trade-offs.
Read article
Is this short-term endowment worth it — or do T-bills and savings bonds beat it hands down?
Read article
Universal life insurance offers flexible premiums and cash value growth — but is it right for Singaporeans? We break down the real costs, pros, cons, and cheaper alternatives for 2026.
Read article
Compare term CI, whole life CI, and multipay critical illness plans from AIA, Prudential, Great Eastern, and Singlife — with real premium data for Singapore residents.
Read article
Compare term CI, whole life CI, and multipay critical illness plans from AIA, Prudential, Great Eastern, and Singlife — with real premium data for Singapore residents.
Read article
Singlife Multipay Critical Illness II covers 135 conditions with up to 900% payout. Here's how it compares to AIA, Manulife, Prudential and FWD multi-pay CI plans.
Read article
A complete guide to buying and selling pre-owned insurance policies on Singapore's secondary market — how it works, what it costs, and whether it makes financial sense for you.
Read article
A life insurance savings plan combines protection with wealth-building. This guide compares the best plans in Singapore 2026 — returns, fees, and who should buy.
Read article
Complete guide to insurance nominations in Singapore. Learn the difference between revocable and trust nominations, how to nominate online since 2024, and why every policyholder needs one.
Read article
A plain-English comparison of every CI plan type available in Singapore — with real premium estimates, worked examples, and a decision framework.
Read article
A neutral, data-driven comparison — real fees, worked SGD examples, and what r/singaporefi actually says about both approaches.
Read article
Compare FWD, Singlife, Manulife, AIA, Prudential & NTUC Income — side by side, with real 2026 premium data.
Read article
How to calculate your surrender value, when it's worth surrendering, and what you'll actually lose — explained in plain English.
Read article
6 Insurers • Term, Whole Life & Critical Illness • CPF Medisave Tips
Read article
An honest, independent review — product specs, surrender penalties, Reddit questions answered, and how it compares to SSBs, T-bills, and fixed deposits.
Read article
Term, Whole Life, Critical Illness & DPS — What You Need, How Much Cover, and How to Buy
Read article
A complete guide to Manulife's participating fund — par fund mechanics, bonus history, returns, and how it compares to alternatives for Singapore investors in 2026.
Read article
Compare AIA, Manulife, Singlife, Prudential and Great Eastern — prices, coverage, and our verdict for each type of buyer.
Read article
Your complete guide to capital guaranteed insurance savings plans — how they work, which insurers offer the best returns, and whether they belong in your Singapore financial plan.
Read article
Get paid at diagnosis — not just at the final stage.
Read article
Updated June 2026 · 8 min read
Read article
How multi-pay CI works, what stages are covered, and whether the higher premium makes sense for you.
Read article
An honest, data-driven comparison of Singapore's top ILPs — so you can decide if one belongs in your financial plan.
Read article
Whole life premiums, cash value, best plans and the honest verdict — for Singapore residents in 2026.
Read article
Compare 2-year and 3-year endowment plans from Singapore's top insurers — projected returns, capital guarantees, and who should buy.
Read article
TM Term Assure II, FlexiAssurance & FlexiCover compared — with real premium data and a plain-English verdict
Read article
Compare investment linked policy Singapore plans from AIA, Prudential, Great Eastern, Manulife and NTUC Income — with a clear fee breakdown and honest ILP vs ETF verdict.
Read article
Compare the best critical illness insurance plans in Singapore 2026. FWD Big 3 CI from S$198/yr, Manulife multi-pay, AIA Power Critical Care — premiums, conditions covered, and who should buy each plan.
Read article
Everything you need to know before putting a lump sum into a single premium endowment plan.
Read article
Protect up to 75% of your salary if illness or injury stops you working — here's everything you need to know about DI insurance in Singapore.
Read article
Compare the top ISPs in Singapore — guaranteed returns, projected yields, SRS tax savings, and who should buy in 2026.
Read article
Compare the best term life insurance plans in Singapore 2026. Real premium tables by age and insurer, how much cover you need, and a step-by-step buyer's guide.
Read article
Looking for a capital-guaranteed way to grow your savings while getting life insurance coverage? An insurance savings plan in Singapore combines disciplined saving with guaranteed returns — but the devil is in the details.
Read article
Compare guaranteed yields, capital protection, and how short term endowment plans stack up against T-bills and fixed deposits in 2026.
Read article
Not financial advice. All figures are for educational reference only. Data verified as at 28 July 2026 unless otherwise noted — see each linked insurer review for its individual fact-check date.
Read article
A critical illness diagnosis can derail your finances in weeks. Critical illness insurance Singapore pays a tax-free lump sum on diagnosis — giving you cash to cover treatment…
Read article
A complete guide to the Dependants' Protection Scheme (DPS) — Singapore's CPF-linked group term life insurance covering millions of working Singaporeans.
Read article
Universal life insurance combines lifelong death benefit protection with a cash-value savings component — but is it the right fit for Singapore investors? This guide covers how…
Read article
Critical illness insurance Singapore is one of the most important financial safety nets you can have — yet most Singaporeans are dangerously underinsured.
Read article
If you want a capital-guaranteed way to grow your savings in Singapore — without the volatility of stocks — an endowment plan could be your answer.
Read article
Read the full article on The Kopi Notes.
Read article
The most cost-effective way to protect your family’s financial future — how term life works, how much coverage you need, and the best options available in Singapore.
Read article
A clear-eyed look at how endowment plans work, what returns to realistically expect, and whether your money could be working harder elsewhere.
Read article
Understand how ILPs work, what they really cost, and whether they make sense for your financial goals — a no-nonsense Singapore investor’s perspective.
Read articleFrequently Asked Questions
How much life insurance do I need in Singapore?
A common rule of thumb is 9–12x your annual income, minus existing assets and CPF. For a 30-year-old earning $5,000/month with a mortgage and young children, that typically works out to $500,000–$1,000,000 in coverage. Our life insurance guide includes a step-by-step calculation framework.
Is an ILP better than buying term insurance and investing the rest?
In most cases, no. The “buy term and invest the rest” (BTIR) strategy typically outperforms ILPs over 20+ years due to significantly lower fees. ILPs charge distribution costs, insurance charges, and fund management fees that compound over time. Our investment insurance guide includes a detailed cost comparison.
Should I buy insurance through an agent or directly?
For straightforward term life insurance, Direct Purchase Insurance (DPI) through compareFIRST.sg often offers lower premiums since there’s no agent commission. For complex needs (estate planning, business insurance, large policies), an independent financial adviser can add value. Avoid captive agents tied to a single insurer.
What’s the difference between endowment plans and ILPs?
Endowment plans offer guaranteed returns plus non-guaranteed bonuses over a fixed term (typically 10–25 years). ILPs invest your premiums in sub-funds with entirely market-dependent returns and no guarantees. Endowments are lower risk but lower potential return; ILPs carry market risk plus high fees. Our investment insurance guide compares both in detail.
Do I still need insurance if I’m single with no dependants?
Life insurance primarily protects dependants, so if nobody relies on your income, you likely don’t need it yet. However, you should still have adequate health insurance (MediShield Life + Integrated Shield Plan) and may want critical illness coverage. Some people lock in whole life at a young age for lower premiums, but this ties up capital that could be invested.
Want more insurance analysis?
Browse all our insurance articles, comparisons, and brand reviews.