MediSave for Surgery in Singapore 2026: How Much Can You Claim? (TOSP Guide)
MediSave covers surgical procedures in Singapore through the Table of Surgical Procedures (TOSP) — a CPF Board and MOH classification system that assigns every operation to one of 7 complexity tables. For 2026, MediSave allows up to $5,290 per surgery (Table 7C), while MediShield Life pays up to $3,900 for the same surgery. Used together with an Integrated Shield Plan, most Singaporeans pay very little cash for complex surgery in subsidised wards.
Not financial advice. All figures are for educational reference only. MediSave and MediShield Life data sourced from CPF Board and MOH as at October 2026.
In This Guide
- What is the Table of Surgical Procedures (TOSP)?
- MediSave Surgery Withdrawal Limits 2026
- MediShield Life Surgery Claim Limits 2026
- MediSave vs MediShield Life: The Key Difference
- Worked Example: Knee Replacement Surgery
- Day Surgery vs Inpatient Surgery
- How an Integrated Shield Plan Tops Up
- Frequently Asked Questions
What is the Table of Surgical Procedures (TOSP)?
The Table of Surgical Procedures (TOSP) is a classification framework jointly maintained by the CPF Board and the Ministry of Health (MOH). It assigns every surgical procedure performed in Singapore to one of seven complexity tables, numbered 1 to 7.
The higher the table number, the more complex the surgery — and the higher the MediSave and MediShield Life payout:
- Table 1 — Minor procedures: simple skin excision, suturing of superficial wounds, drainage of superficial abscess
- Table 2 — Mildly complex: excision of benign lumps, minor orthopaedic procedures
- Table 3 — Moderately complex: appendectomy (open), tonsillectomy, simple hernia repair
- Table 4 — Intermediate: laparoscopic cholecystectomy, some knee procedures
- Table 5 — Complex: total knee replacement, selected cardiac procedures
- Table 6 — Very complex: major abdominal surgery, complex spine surgery
- Table 7 — Highly complex: coronary artery bypass grafting (CABG), major cancer resections, multi-level spine fusion
Within each table, operations are sub-classified based on the type of anaesthesia used:
- Column A — Local anaesthesia only
- Column B — Regional anaesthesia or Monitored Anaesthesia Care (MAC)
- Column C — General anaesthesia (GA)
A Table 7C operation — for example, a coronary artery bypass under general anaesthesia — is the highest payout tier under both MediSave and MediShield Life. Your surgeon or hospital will advise you of the TOSP classification before your surgery; it is also stated on your surgery consent form.
MediSave Surgery Withdrawal Limits 2026 (All TOSP Tables)
The table below shows the maximum you can withdraw from your MediSave account to pay for surgical fees in 2026. These are CPF Board withdrawal limits — separate from the hospitalisation daily limits that apply to your ward stay.
| TOSP Table | Column A (Local) | Column B (Regional/MAC) | Column C (General GA) |
|---|---|---|---|
| Table 1 | $240 | $420 | $490 |
| Table 2 | $760 | $1,120 | $1,120 |
| Table 3 | $1,390 | $1,740 | $1,920 |
| Table 4 | $2,380 | $2,440 | $2,540 |
| Table 5 | $2,610 | $2,660 | $2,770 |
| Table 6 | $3,260 | $3,610 | $3,960 |
| Table 7 | $4,340 | $4,830 | $5,290 |
Source: CPF Board, MediSave for Hospitalisation and Surgery (as at October 2026). These are per-procedure limits.
These limits apply per surgical operation. If you have two separate procedures during one hospitalisation (e.g. an appendectomy plus a diagnostic laparoscopy), each is assessed against its own TOSP table limit. For a full picture of how MediSave covers your entire hospital bill, see our guide on MediSave withdrawal limits for hospitalisation 2026.
MediShield Life Surgery Claim Limits 2026
MediShield Life is Singapore’s mandatory national health insurance. It pays a fixed claim for each surgical procedure — on top of, and separate from, your MediSave withdrawal. The claim limits below were last updated by MOH on 3 June 2026.
| TOSP Table | Column A | Column B | Column C |
|---|---|---|---|
| Table 1 | $240 | $420 | $490 |
| Table 2 | $760 | $1,120 | $1,120 |
| Table 3 | $1,390 | $1,740 | $1,920 |
| Table 4 | $2,310 | $2,370 | $2,460 |
| Table 5 | $2,700 | $3,270 | $3,270 |
| Table 6 | $3,540 | $3,540 | $3,540 |
| Table 7 | $3,900 | $3,900 | $3,900 |
Source: MOH, MediShield Life Benefits Table (last updated 3 June 2026). Maximum claim per admission: $200,000/year, no lifetime limit.
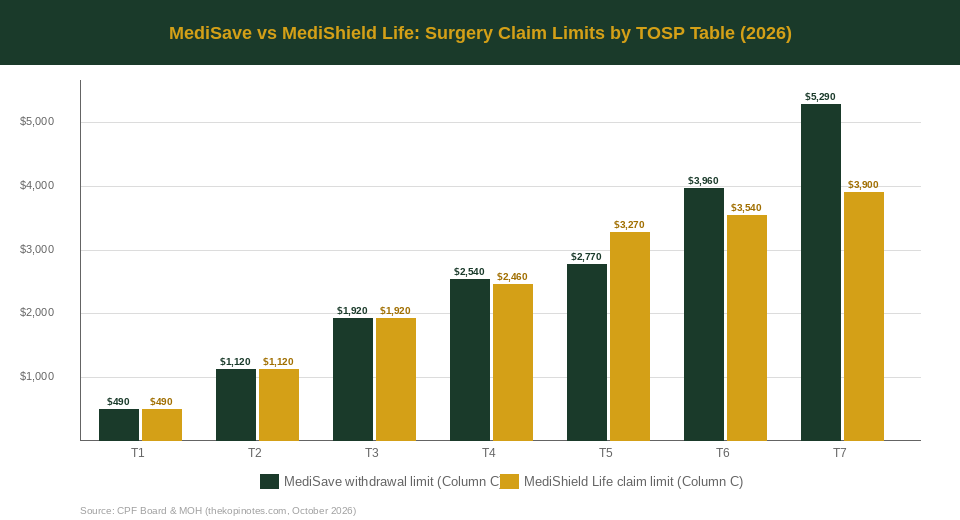
Key observation: For Tables 1–3, MediShield Life and MediSave surgery limits are identical. From Table 4 onwards, the two systems diverge. Most notably, MediShield Life caps Table 7 operations at $3,900 across all sub-classes (A, B, C), while MediSave allows up to $5,290 for a Table 7C operation. This $1,390 difference is significant — for the most complex surgeries, your MediSave can actually contribute more than MediShield Life for the surgical fee alone.
MediSave vs MediShield Life: The Key Difference for Surgery
Many Singaporeans assume MediSave and MediShield Life are interchangeable — they are not. Here is how the two systems compare when it comes to paying for surgery:
| MediSave | MediShield Life | |
|---|---|---|
| What it is | Your personal CPF healthcare savings | Mandatory national health insurance |
| How it pays | Withdrawals from your own CPF account | Insurance claim payout |
| Max surgery payout (Table 7C) | $5,290 | $3,900 |
| Can both be used together? | Yes — MediShield Life pays first; MediSave tops up deductible and co-insurance | |
| Annual payout limit | Capped by your MediSave balance | $200,000/year, no lifetime cap |
Source: CPF Board & MOH (October 2026)
In practice, when you have surgery in a Singapore hospital, the payment sequence works like this:
- MediShield Life pays first — covering the TOSP claim amount (e.g. $3,900 for a Table 7 surgery). This directly reduces your bill.
- MediSave withdrawals top up the rest — you can use MediSave to pay the remaining deductible (typically $3,500 for B1/A/private wards) and co-insurance (10% of the eligible bill after deductible), up to the MediSave withdrawal limit.
- For complex surgeries (Tables 4–7), MediSave withdrawal limits exceed MediShield Life claim limits. The difference — up to $1,390 for Table 7C — can be applied towards your deductible or co-insurance from MediSave.
Worked Example: Knee Replacement Surgery (Table 7C)
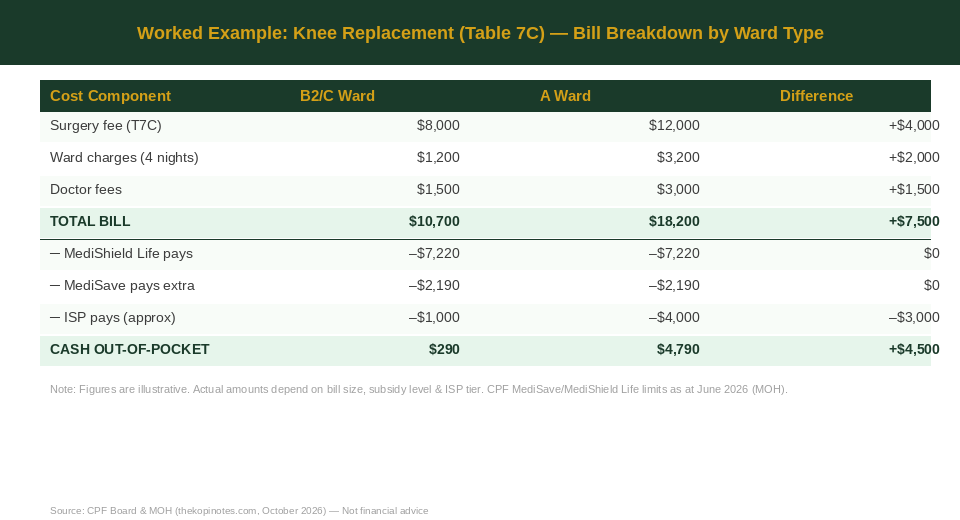
Let us walk through how MediSave and MediShield Life pay for a total knee replacement — classified as Table 7C under the TOSP system. This is one of the most common major surgeries among Singaporeans aged 50 and above. Assume a 4-night hospital stay including the day of surgery.
B2/C Ward (Subsidised): Cash out-of-pocket ~$290
In a B2/C subsidised ward, the total bill for a knee replacement (surgery, 4 nights’ ward stay, surgeon and anaesthetist fees) is approximately $10,700 before government subsidies reduce it further. MediShield Life contributes $7,220 (surgery claim $3,900 + ward $830/night × 4 nights = $3,320). MediSave adds another $2,190 (surgery balance $1,390 + ward co-payment ~$800). The remaining cash out-of-pocket is approximately $290 — or near zero with even a basic ISP.
A Ward (Unsubsidised): Cash out-of-pocket ~$4,790 without ISP
In an A-class ward, the total bill rises to approximately $18,200. MediShield Life and MediSave still pay the same fixed TOSP-based amounts. Without an ISP, the cash out-of-pocket is roughly $4,790. With a comprehensive ISP rider that covers A-ward charges, this could be reduced to a small copayment or zero.
These figures are illustrative. Actual amounts depend on your specific procedure, hospital, surgeon’s fees, and ISP coverage. MediSave and MediShield Life limits verified from CPF Board and MOH (October 2026).
If you do not yet have an ISP, or are comparing plans before your next renewal, browse the Integrated Shield Plans comparison section on TKN. While waiting for a claim to process, having a liquid emergency fund also helps — a MariBank Savings Account (referral code 2DCT80WQ) offers competitive rates for your short-term cash reserves.
Day Surgery vs Inpatient Surgery: Are the Limits Different?
A common question is whether the TOSP surgical claim limits are different for day surgery (you go home the same day) compared to inpatient surgery (you stay at least one night). The answer: the surgical procedure limits are the same. A Table 5C procedure is a Table 5C procedure whether it is performed as day surgery or inpatient.
What differs is the ward charge component:
- Day surgery ward rate: MediSave and MediShield Life both cover up to $830/day for day surgery admissions.
- Inpatient ward rate (normal ward): MediSave covers up to $1,130/day for the first 2 days, then $400/day thereafter. MediShield Life pays $830/day + an additional $800 for the first 2 days (effectively $1,630/day for days 1 and 2), reducing to $830/day from day 3 onwards.
- ICU ward: MediShield Life covers up to $5,140/day for intensive care, reflecting the higher cost of ICU-level nursing and monitoring.
For most day surgeries (Tables 1–4), the $830/day ward rate is sufficient since day surgery facility fees are typically lower than inpatient ward charges. If your operation is reclassified from day surgery to inpatient due to complications, the inpatient rates automatically apply.
How an Integrated Shield Plan Tops Up Your Surgery Coverage
An Integrated Shield Plan (ISP) is a private health insurance plan sold by five approved insurers (AIA, Singlife, Great Eastern, NTUC Income, and Prudential) on top of MediShield Life. It provides additional surgical and hospitalisation coverage — most meaningfully by covering the deductible and co-insurance that MediShield Life leaves behind.
What an ISP adds to surgery coverage
- Deductible coverage: MediShield Life has an annual deductible of $3,500 for B1 wards and above. An ISP rider can waive or reduce this to a small fixed co-payment (e.g. $3,000 or even $0 for some rider tiers).
- Co-insurance: After the deductible, MediShield Life pays 90% of the eligible bill; you pay 10%. An ISP full rider can cover this 10%, leaving you with near-zero cash out-of-pocket.
- Ward class upgrade: An A-ward ISP extends coverage to A-class hospital rooms, where bills are substantially higher.
- Private hospital coverage: Premium ISP plans cover private hospitals. Surgeon fees at private hospitals regularly exceed TOSP limits, so ISP coverage of “as-charged” surgeon fees is valuable for private hospital care.
For complex Table 6 or Table 7 surgeries — where bills can reach $30,000–$80,000 or more in private hospitals — the difference between having a full ISP rider and not having one is often $20,000–$50,000 in out-of-pocket costs. If you are reviewing your ISP options, consider an independent financial planning platform like Endowus (referral code 2V343) for a holistic view of your healthcare and financial planning.
Browse the TKN Integrated Shield Plans section for detailed reviews and comparisons across all five ISP insurers.
Frequently Asked Questions: MediSave for Surgery Singapore
How do I find out which TOSP table my surgery falls under?
Your surgeon or hospital case manager will advise you of the TOSP classification before your operation — it is also stated on your surgery consent form. You can also search the MOH MediShield Life Benefits table online, which lists TOSP classifications for hundreds of specific procedures. If you are planning elective surgery, ask your specialist at your pre-op consultation — it allows you to plan your MediSave and cash resources in advance.
Can I use MediSave for all types of surgery in Singapore?
MediSave can be used for all surgical procedures classified under the TOSP system and performed at a licensed Singapore hospital or day surgery centre. This includes both emergency and planned elective surgeries. Exclusions apply to cosmetic procedures that are not medically necessary, and certain experimental treatments. The full list of approved MediSave uses is published by the CPF Board on its website.
What if my surgeon's fee is higher than the TOSP claim limit?
If the actual surgeon’s fee exceeds the TOSP withdrawal or claim limit, the excess is not covered by MediSave or MediShield Life. You would pay this from cash, or it could be covered by your ISP rider if your plan covers “as-charged” or “benefit schedule” surgeon fees. Private hospital surgeons in particular often charge above TOSP limits. This is one of the key reasons ISP holders at private hospitals should ensure their rider covers the surgeon fee component, not just the hospitalisation charges.
Does MediShield Life cover surgery at a private hospital?
Yes — MediShield Life covers surgery at both public and private hospitals in Singapore, but the claim amounts are fixed by TOSP table regardless of hospital type. Since private hospital bills are significantly higher, MediShield Life typically covers a smaller proportion of the total bill at a private hospital. A private hospital ISP top-up is usually needed to avoid large out-of-pocket expenses for private hospital surgery.
Is the MediSave surgery withdrawal limit per surgery or per year?
The TOSP-based MediSave withdrawal limit applies per surgical procedure, not per year. If you have two separate operations in the same year, each surgery is assessed against its own TOSP table limit. However, your total MediSave usage during a hospitalisation episode is also subject to the Medisave Withdrawal Limit (MWL), which applies across all MediSave-approved charges — ward charges, surgical fees, implants — for a single admission episode.
How do the 2026 MediShield Life surgery limits compare to previous years?
MOH last updated the MediShield Life benefit tables effective 3 June 2026. The update raised claim limits for Tables 4–6 compared to the prior schedule, reflecting increases in medical costs. Table 7 surgeries remain capped at $3,900 across all columns. The MediSave TOSP withdrawal limits (CPF Board) are a separate schedule and were not revised for 2026 at the time of writing. Always verify the current figures at the CPF Board and MOH official websites before making any healthcare financing decisions.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.