Starhill Global REIT (P40U) Investment Review 2026: 6.9% Yield, P/NAV Discount & S$0.65 Analyst Target
A complete analysis of Starhill Global REIT’s FY2026 results, Orchard Road portfolio, balance sheet, and whether the current share price represents a buying opportunity for Singapore income investors.
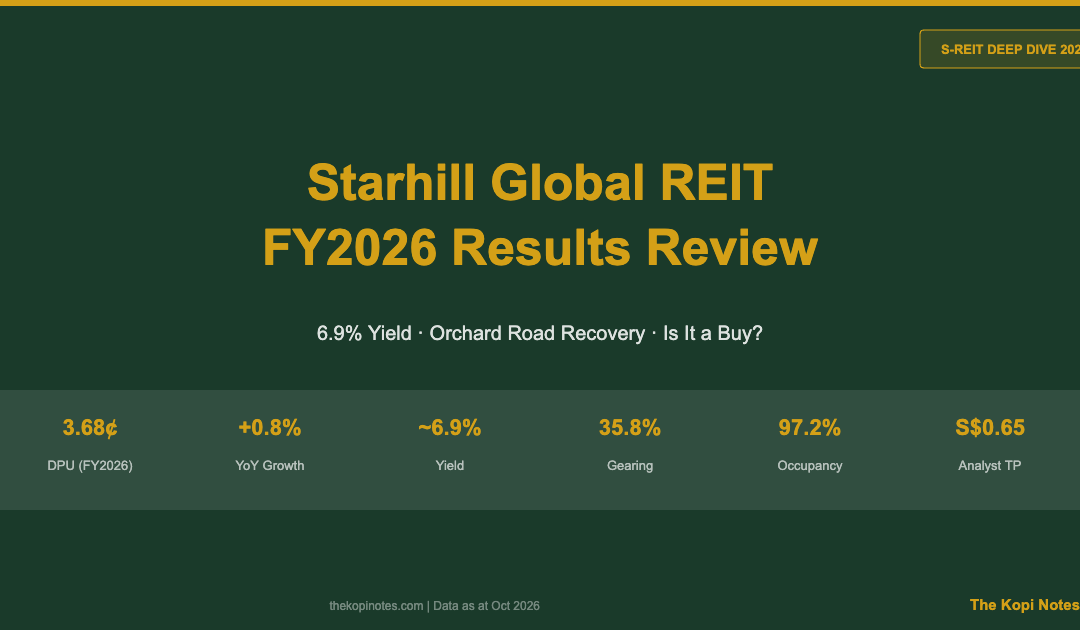
Starhill Global REIT (SGX: P40U) is a Singapore-listed retail and office REIT anchored by Wisma Atria and Ngee Ann City on Orchard Road. For FY2025/26, the REIT delivered a full-year DPU of 3.68 cents (+0.8% YoY), with portfolio occupancy recovering to 97.2%. At S$0.53, the unit trades at a meaningful discount to analyst targets of S$0.65, offering an implied yield of approximately 6.9%.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
What Is Starhill Global REIT?
Starhill Global REIT (SGX: P40U) is one of Singapore’s oldest listed REITs, established in 2005 and managed by YTL Starhill Global REIT Management Limited. The REIT owns a diversified portfolio of retail and office assets across Singapore, Malaysia, Australia, and China, with a total asset value of approximately S$2.9 billion as at June 2026.
The Singapore portfolio — anchored by Wisma Atria and Ngee Ann City on prime Orchard Road — forms the core of the REIT’s earnings, contributing the majority of net property income. Both properties benefit from long master leases and strong anchor tenants including Takashimaya Department Store at Ngee Ann City. Internationally, the REIT holds Lot 10 and Starhill Gallery in Kuala Lumpur, Myer Centre Adelaide in Australia, and retail assets in China.
For Singapore income investors, Starhill Global REIT offers exposure to Orchard Road’s long-term recovery, a portfolio occupancy that has recovered to 97.2%, and a defensive dividend yield of approximately 6.9% as at October 2026. The REIT distributes income semi-annually and operates a Distribution Reinvestment Plan (DRP) for unitholders who prefer to receive new units in lieu of cash.
FY2026 Financial Highlights
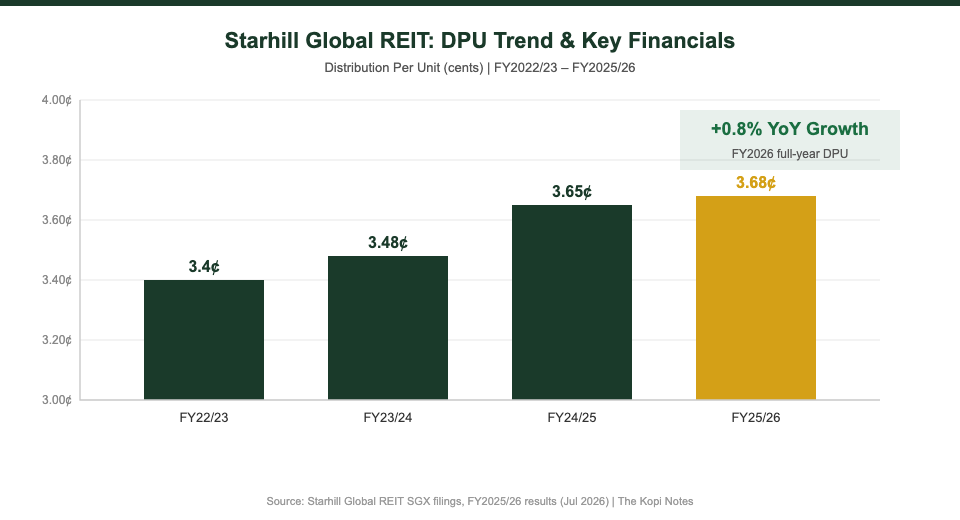
Starhill Global REIT reported its FY2025/26 (year ended 30 June 2026) results on 29 July 2026. The headline figures showed modest but steady growth, with the full-year DPU rising 0.8% year-on-year to 3.68 cents. The second-half performance was stronger, with 2H DPU of 1.88 cents representing +1.6% growth — an acceleration from the 1H pace.
| Metric | 2H FY2025/26 | 2H FY2024/25 | YoY Change |
|---|---|---|---|
| Gross Revenue | S$96.2M | S$95.8M | +0.4% |
| Net Property Income (NPI) | S$75.3M | S$74.6M | +1.0% |
| Income Available for Distribution | S$46.1M | S$44.5M | +3.6% |
| Income to be Distributed | S$43.7M | S$42.6M | +2.7% |
| Distribution Per Unit (DPU) | 1.88 cents | 1.85 cents | +1.6% |
Source: Starhill Global REIT FY2025/26 Media Release, SGX announcement, July 2026
Notably, income available for distribution grew 3.6% — faster than the NPI growth — driven in part by cost discipline and the favourable resolution of the Myer arbitration case. The manager applied the DRP to the January–June 2026 distribution, issuing new units at approximately a 2% discount to VWAP.
Orchard Road Portfolio Analysis
The Singapore portfolio remains the crown jewel of Starhill Global REIT, with Wisma Atria and Ngee Ann City sitting at one of the world’s premier retail corridors. A key structural advantage for unitholders: no new retail supply is expected on Orchard Road in 2026 or 2027, providing a supply-constrained environment that supports rental reversions and occupancy.
The FY2026 results showed a divergence within the Singapore portfolio. Ngee Ann City delivered stronger contributions YoY, benefiting from Takashimaya’s robust footfall and the recovery in tourist spend from China and Southeast Asia. Wisma Atria’s retail contribution, however, came in slightly weaker, reflecting ongoing tenant remixing as the manager repositions certain sections of the mall for higher-yielding tenants.
For Singapore investors focused on passive income in Singapore, the Orchard Road assets provide a relatively defensive income stream. The long master lease structure at Ngee Ann City (anchored by Takashimaya) insulates a significant portion of NPI from short-term retail volatility, a meaningful risk buffer compared to single-tenanted retail REITs.
| Singapore Property | Type | Key Tenant/Anchor | FY2026 Performance |
|---|---|---|---|
| Ngee Ann City | Retail + Office | Takashimaya | Stronger YoY contribution |
| Wisma Atria | Retail | Multi-tenant fashion/F&B | Slightly weaker; remixing underway |
Source: Starhill Global REIT FY2025/26 results presentation, July 2026
Overseas Portfolio & Currency Tailwinds
Beyond Singapore, Starhill Global REIT’s overseas assets contributed positively to FY2026 distributions, helped by favourable currency movements. The Malaysian ringgit and Australian dollar both appreciated against the Singapore dollar during the year, boosting the translated NPI contribution from these markets.
Lot 10 in Kuala Lumpur — a flagship lifestyle mall in Bukit Bintang — delivered stronger contributions alongside Singapore’s Ngee Ann City. Starhill Gallery, the luxury retail component in KL, remained steadier given its more niche positioning.
The Australian portfolio, centred on Myer Centre Adelaide, faced headwinds from weaker office contributions. A significant positive development in FY2026 was the favourable award in the Myer arbitration case, which provided a one-time income uplift and resolved a key source of uncertainty that had weighed on the REIT. Going forward, the Adelaide office component remains a drag, though the retail floors continue to stabilise.
The China retail portfolio continues to face structural headwinds from slower consumer spending and e-commerce competition. While this remains a small portion of the portfolio, it warrants monitoring as a source of NPI drag.
Balance Sheet & Debt Management
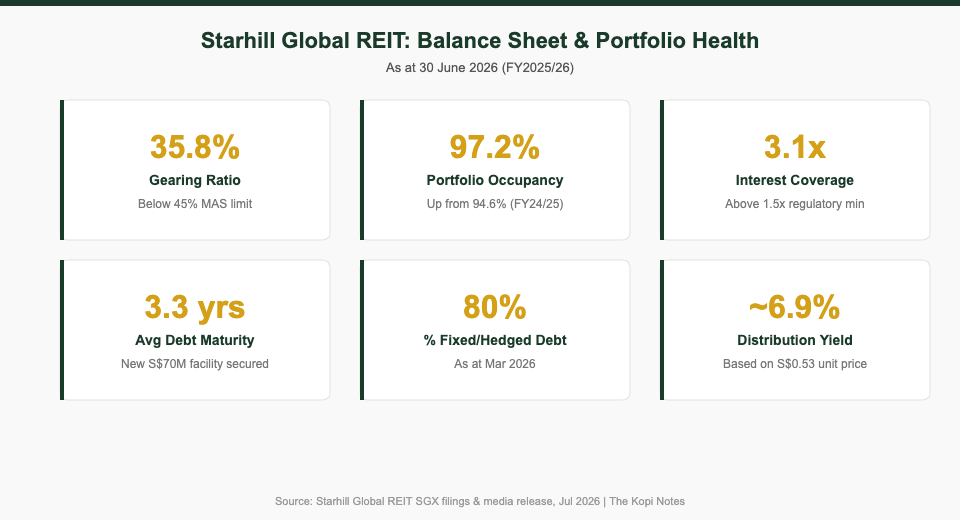
One of the more constructive aspects of Starhill Global REIT’s FY2026 story is its balance sheet management. With gearing at 35.8% — well below the MAS regulatory ceiling of 45% — the REIT has meaningful debt headroom of approximately S$370–400M at current asset values. This provides a buffer should asset valuations soften and positions the REIT to pursue accretive acquisitions if compelling opportunities arise.
Interest coverage of 3.1x comfortably exceeds the 1.5x regulatory minimum. Importantly, approximately 80% of the REIT’s total debt is on fixed rates or hedged, providing income stability even in an environment where short-term interest rates remain elevated versus pre-2022 levels.
In April 2026, the manager secured two new sustainability-linked credit facilities — a S$70 million six-year unsecured revolving credit facility and an A$70 million equivalent facility — to proactively refinance upcoming maturities. The S$70 million facility will be drawn in October 2026 to repay medium-term notes maturing that month, while the A$ facility addresses Australian debt maturing in FY2027/28. The result: no significant refinancing cliff through FY2028/29, which meaningfully de-risks the near-term outlook for income investors interested in building a portfolio of the best S-REITs in Singapore.
| Balance Sheet Metric | FY2025/26 (Jun 2026) | Assessment |
|---|---|---|
| Aggregate Leverage (Gearing) | 35.8% | Comfortable — 9.2ppt below MAS ceiling |
| Interest Coverage Ratio | 3.1x | Healthy — 2x above regulatory minimum |
| Average Debt Maturity | 3.3 years | Well-laddered; no near-term cliff |
| Fixed/Hedged Debt | ~80% | Good income visibility |
| Portfolio Committed Occupancy | 97.2% | Up from 94.6% — strong recovery |
Source: Starhill Global REIT FY2025/26 Interim Financial Statements and Media Release, SGX, July 2026
Valuation & Investment Thesis
At a share price of approximately S$0.53 (as at August 2026), Starhill Global REIT offers a forward distribution yield of approximately 6.9% based on the FY2026 DPU of 3.68 cents. This compares favourably against the broader S-REIT sector, where Orchard Road retail assets typically command a premium given their defensive positioning and supply constraints.
Analysts remain constructive on the stock. GrowBeanSprout initiated with a BUY and S$0.65 price target in August 2026, implying upside of approximately 22.6% from the then-prevailing price. RHB raised its target to S$0.66 (from S$0.60) following the 1H results, also maintaining a BUY call. The S$0.65–0.66 analyst target range implies the market has yet to fully price in the occupancy recovery and the resolution of the Myer arbitration overhang.
For Singapore income investors seeking passive income with a retail REIT angle, the combination of a 6.9% yield, improving occupancy (97.2%), and no new Orchard Road supply through 2027 presents a credible investment case. Those using platforms like Syfe or FSMOne can access SGX-listed REITs efficiently. Investors also making use of their Endowus account for SRS or CPF funds should note that Starhill Global REIT is not CPF-investable, though it can be purchased through a regular brokerage account with SRS funds for tax-deferred accumulation.
Pairing Starhill Global REIT with other income-generating assets — such as Singapore Savings Bonds or T-bills — can help smooth portfolio volatility. Investors can explore a retirement planning calculator to model how a REIT allocation fits their income needs.
Risks to Consider
No REIT investment is without risk. For Starhill Global REIT, the key considerations as at October 2026 include:
Orchard Road rental reversion risk: While occupancy has recovered to 97.2%, the pace of positive rental reversions depends on consumer sentiment and tourist arrivals. Any macro slowdown — particularly in Chinese tourist spend — could dampen Wisma Atria retail reversions.
Adelaide office weakness: Myer Centre Adelaide’s office segment continues to face subdued demand, reflecting the structural shift in Australian office markets post-pandemic. The manager has not provided a clear timeline for occupancy recovery here.
China portfolio headwinds: The China retail assets face structural pressure from e-commerce and slower domestic consumption growth. While a small portion of NPI, sustained underperformance could weigh on overall distribution.
Interest rate sensitivity: With approximately 20% of debt on floating rates, further rate movements could impact finance costs. However, the 80% fixed/hedged ratio significantly limits this exposure.
Currency risk: A reversal of MYR/AUD strength against SGD could reverse the FY2026 translation tailwinds. This is an inherent feature of a multi-geography REIT.
Frequently Asked Questions
What is Starhill Global REIT and what properties does it own?
Starhill Global REIT (SGX: P40U) is a Singapore-listed REIT that owns retail and office properties in Singapore, Malaysia, Australia, and China. Its flagship Singapore assets are Wisma Atria and Ngee Ann City, both located on Orchard Road. The REIT was listed in 2005 and is managed by YTL Starhill Global REIT Management Limited.
What was Starhill Global REIT's DPU for FY2026?
Starhill Global REIT declared a full-year DPU of 3.68 cents for FY2025/26 (the financial year ended 30 June 2026), up 0.8% year-on-year. The second half DPU was 1.88 cents (+1.6% YoY). Income available for distribution grew 3.6% in 2H, reflecting stronger NPI and cost discipline. Results were announced on 29 July 2026.
What is Starhill Global REIT's current dividend yield?
Based on the FY2026 DPU of 3.68 cents and a share price of approximately S$0.53 (as at August 2026), Starhill Global REIT offers a distribution yield of approximately 6.9%. This yield compares attractively to other Orchard Road retail REITs. Note that unit prices fluctuate, so the actual yield at time of purchase may differ.
What is the analyst price target for Starhill Global REIT?
Following the FY2026 results, GrowBeanSprout maintained a BUY rating with a 12-month price target of S$0.65, implying approximately 22.6% upside from the then-prevailing price of S$0.53 (as at 7 August 2026). RHB’s Vijay Natarajan also held a BUY call with a S$0.66 target following 1H results. These are analyst views and not financial advice — actual returns may differ.
Is Starhill Global REIT suitable for CPF or SRS investment?
Starhill Global REIT (P40U) is not on the CPF Investment Scheme (CPFIS) approved list, so CPF Ordinary Account funds cannot be used to purchase it. However, investors can purchase P40U through their SRS (Supplementary Retirement Scheme) account via a brokerage that supports SRS trading, such as DBS Vickers or POEMS, allowing for tax-deferred income accumulation.
How does Starhill Global REIT's gearing compare to the MAS limit?
As at 30 June 2026, Starhill Global REIT’s aggregate leverage (gearing) stood at 35.8%, well below MAS’s regulatory ceiling of 45%. This leaves approximately S$370–400 million in debt headroom before reaching the regulatory limit. The REIT also secured new sustainability-linked credit facilities in April 2026 to proactively manage upcoming debt maturities, with no significant refinancing cliff expected through FY2028/29.
Start Building Your S-REIT Portfolio
Access Singapore REITs cost-effectively through our partner platforms. Use referral codes for exclusive sign-up bonuses.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.