Coast FIRE in Singapore: The Short Version
Coast FIRE means saving a lump sum early, then stopping—letting compound growth carry you to retirement while you only earn enough to cover today’s bills. In Singapore, CPF LIFE’s guaranteed payout from age 65 acts as a built-in income floor, which significantly reduces the private portfolio you need to coast on.
The four FIRE variants for Singapore:
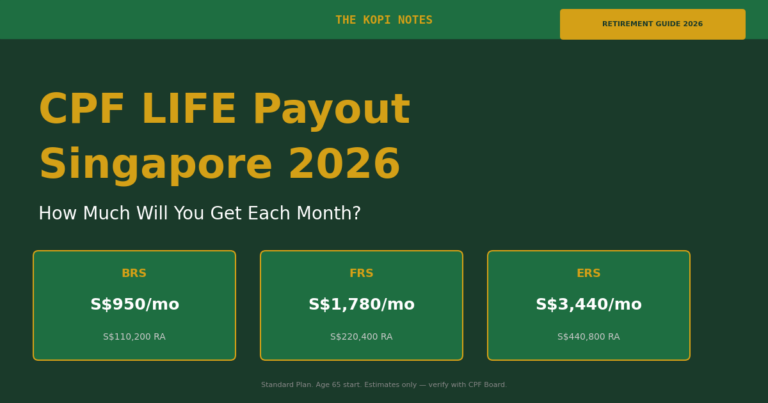
- Lean FIRE — CPF LIFE BRS (~S$950/mo) + paid-off HDB only. Bare-bones but achievable with minimal savings.
- Coast FIRE — Save your Coast Number by a target age, then coast. Private portfolio supplements CPF LIFE.
- Barista FIRE — Semi-retire with light part-time work (~S$800–1,500/mo) to bridge the CPF LIFE gap.
- Fat FIRE — CPF LIFE ERS (~S$3,440/mo) + large investment portfolio for S$5,000+/mo lifestyle.
If your HDB is fully paid off and you hold CPF LIFE at the Full Retirement Sum (FRS), your private portfolio needs to cover roughly S$1,420/mo gap for a Comfortable tier retirement. At age 35, that Coast Number is approximately S$74,000.
What Is Coast FIRE — And Why Singapore Is Different
FIRE in Singapore usually starts with working out The Number — the portfolio that, at a 3.5–4% withdrawal rate, funds your lifestyle indefinitely. But Coast FIRE flips the question: instead of “how large does my portfolio need to be at retirement?”, it asks “how much do I need to save right now so compound interest reaches The Number by itself?”
Once you hit your Coast Number, you are free to stop directing income into investments. You still work — but only enough to pay today’s bills. Your existing savings do the heavy lifting from here to age 65.
This matters in Singapore for three reasons:
- CPF LIFE is your income floor. Unlike in the US, where a retiree must self-fund 100% of spending from their portfolio, Singapore’s CPF LIFE guarantee pays S$950–3,440/mo from age 65 depending on which retirement sum you reach. That income floor shrinks the private portfolio you need — and shrinks your Coast Number with it.
- Your HDB does most of the heavy lifting on housing. A fully paid-off HDB flat eliminates rent, Singapore’s largest household expense. Most HDB owners are mortgage-free before 55. That changes your retirement math completely.
- Your CPF contributions keep coming even when you “coast.” If you remain employed, CPF contributions (employer + employee) continue accumulating in your OA and SA until age 55. That’s additional involuntary retirement savings every month — even while you’re “only” covering living expenses.
The 4% rule in its pure US form — sell 4% of your portfolio per year and assume no guaranteed income — does not translate directly to Singapore. Always adjust for CPF LIFE’s floor before calculating how much you need in private investments.
The Four FIRE Variants in Singapore Context
1. Lean FIRE
Lean FIRE targets the Essential spending tier — around S$1,800–2,200/mo for a single person in an HDB flat. At this level, CPF LIFE at the Basic Retirement Sum (BRS payout ~S$950/mo as at Sep 2026) combined with a modest private portfolio can cover the gap.
This works best if your HDB is fully paid off, you have no dependants, and your healthcare is MediShield Life + MediSave. It is achievable, but leaves very little buffer for medical emergencies or unexpected costs. Most Singaporeans who pursue Lean FIRE are choosing freedom from employment over lifestyle comfort.
2. Coast FIRE
Coast FIRE — the focus of this article — targets a Comfortable tier retirement (S$3,000–3,200/mo) funded partly by CPF LIFE FRS (S$1,780/mo) and partly by private investments. You save until you hit your Coast Number, then coast. This is the variant most people who earn a median Singapore salary can realistically reach before 40.
3. Barista FIRE
Named for the US barista who works part-time for employer health insurance, Barista FIRE Singapore means semi-retiring to part-time or freelance work. The income — S$800–1,500/mo in a low-stress role — covers your current expenses while your investments continue to grow undisturbed. CPF LIFE at 65 and your private portfolio later replace that part-time income entirely.
This variant suits people with valuable but burnout-inducing careers who want to step back earlier than 65 without fully withdrawing from productive work.
4. Fat FIRE
Fat FIRE in Singapore means a Comfortable-Plus lifestyle of S$5,000–5,500/mo, often with a condo, overseas holidays, and significant dining out. CPF LIFE at the Enhanced Retirement Sum (ERS payout ~S$3,440/mo as at Sep 2026) covers a meaningful portion. The private portfolio needed to bridge the remaining S$1,500–2,000/mo gap is larger, but still far smaller than a pure self-funded Fat FIRE in most Western countries.
How to Calculate Your Coast FIRE Number in Singapore
Your Coast FIRE number is the lump sum you need today for compound growth to deliver your full retirement portfolio by age 65 — with no further contributions.
Step 1 — Find your annual retirement spending gap above CPF LIFE
Take your target monthly retirement spending and subtract your expected CPF LIFE payout. The remainder is your annual private portfolio withdrawal.
Example (Comfortable tier, FRS CPF LIFE):
Target S$3,200/mo − CPF LIFE FRS S$1,780/mo = Gap S$1,420/mo = S$17,040/year
Step 2 — Calculate the portfolio you need at age 65
Divide the annual gap by a conservative withdrawal rate. We use 4% here as a round number; for Singapore’s cost environment and shorter typical portfolio duration (65–85 = 20 years), 3.5–4.5% is reasonable depending on your asset mix.
S$17,040 ÷ 4% = S$426,000 target portfolio at age 65
Step 3 — Discount back to today
Use a conservative nominal return assumption (6% for a diversified Singapore-listed and global ETF portfolio) to find today’s Coast Number:
Coast Number = S$426,000 ÷ (1.06)years to 65
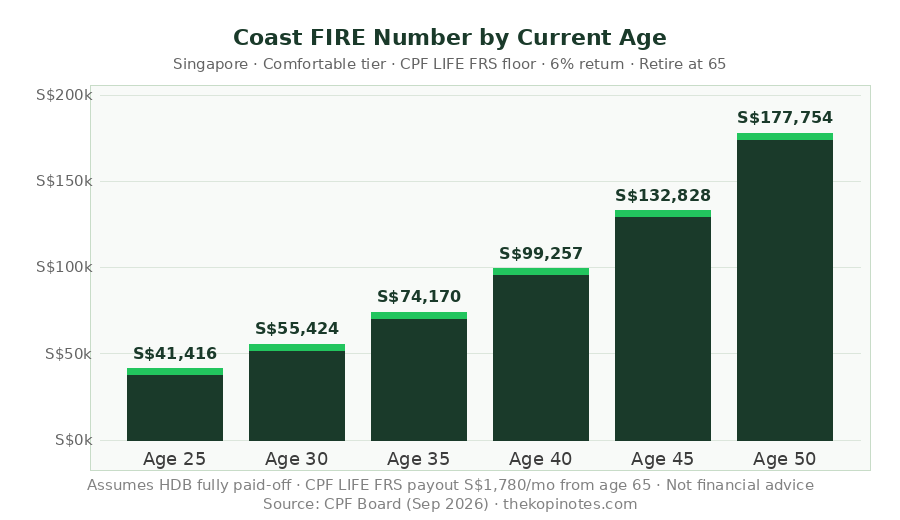
| Current Age | Years to 65 | Coast FIRE Number | CPF LIFE FRS floor |
|---|---|---|---|
| 25 | 40 | S$41,400 | S$1,780/mo |
| 30 | 35 | S$55,400 | S$1,780/mo |
| 35 | 30 | S$74,200 | S$1,780/mo |
| 40 | 25 | S$99,300 | S$1,780/mo |
| 45 | 20 | S$132,800 | S$1,780/mo |
| 50 | 15 | S$177,800 | S$1,780/mo |
Assumptions: HDB fully paid off; CPF LIFE Standard Plan FRS payout S$1,780/mo from age 65 (CPF Board, Sep 2026); 6% nominal annual return on private investments; 4% withdrawal rate; single person. Not financial advice.
Worked Example: Reaching Coast FIRE by 35 in Singapore
Profile: Hui Lin, 28, software engineer at a mid-size tech firm. She earns S$6,500/mo. Her HDB BTO in Punggol is on a 25-year mortgage. She wants to stop actively saving for retirement at age 35 and coast to a Comfortable retirement at 65.
Target: Comfortable tier, S$3,200/mo in 2026 dollars.
CPF LIFE floor: FRS payout of S$1,780/mo from age 65 (she will top up to FRS by making voluntary CPF top-ups to her Retirement Account). CPF Board confirmed payout as at Sep 2026.
Gap to fund from private portfolio: S$1,420/mo = S$17,040/year.
Target portfolio at 65: S$17,040 ÷ 4% = S$426,000.
Coast Number at age 35: S$426,000 ÷ (1.06)30 = S$74,170.
From 28 to 35 — seven years — Hui Lin needs to accumulate S$74,170 in a private investment account (outside CPF). At S$850/mo invested at 6% nominal, she reaches S$74,000 by month 82 (just under 7 years). After that, she stops contributing and her mortgage continues.
At 35, Hui Lin’s monthly picture shifts:
- Income: S$6,500 (she continues working, but can take a lower-stress role or reduce hours after 40)
- Mortgage: Still running, cleared by ~45
- Monthly investment contribution: S$0 (optional — she is coasting)
Her S$74,170 at age 35 grows at 6%/year to reach approximately S$430,000 by age 65 — slightly above her target, with room for inflation variance. Meanwhile, CPF OA and SA contributions from employment continue accumulating towards her FRS top-up automatically.
This example is illustrative only. Actual returns will vary and this is not financial advice. Verify your expected CPF LIFE payout at cpf.gov.sg (as at Oct 2026).
Three Paths Once You Hit Your Coast Number
Path A: Stay employed, stop investing
The simplest approach. Keep working your current job but redirect what you used to invest into clearing your mortgage faster, enjoying life, or building a small emergency buffer. CPF contributions still flow in. When the mortgage clears, your monthly outgoings drop further. You reach 65 with a fully coasted portfolio and a paid-off HDB.
Path B: Downshift to a lower-stress role
Barista FIRE territory. Take a job that pays S$3,000–4,000/mo with low stress and good hours. You stop growing your private portfolio but cover all current expenses comfortably. This works especially well for freelancers, part-time consultants, or people who return to work they enjoy after leaving burnout careers. See our Barista FIRE Singapore guide for how the math works in the semi-retirement years.
Path C: Defer CPF LIFE for a higher payout
If you reach Coast FIRE by 40 and stop actively saving, you may find your private portfolio grows well beyond the target by 65. In that case, consider deferring CPF LIFE payouts from 65 to 70 — every year of deferral increases the monthly payout by approximately 6–7%, meaning deferring five years could raise a FRS payout from S$1,780 to roughly S$2,400/mo. Check the latest projections on the Singapore Retirement Calculator.
Common Mistakes in Singapore Coast FIRE Planning
Ignoring CPF LIFE in the calculation. The single biggest error is calculating a Coast Number without netting out CPF LIFE’s expected payout. This results in over-saving and potentially working years longer than necessary.
Assuming the 4% rule works as written. The 4% rule was designed for a 30-year portfolio with a US-weighted stock/bond allocation. For a Singapore retiree at 65 with a 20–25 year horizon and S-REITs or SSBs in the mix, 3.5–4.5% is defensible — but base your personal plan on your actual asset allocation, not a US rule of thumb.
Forgetting housing as a variable. An HDB that is still mortgaged at retirement requires either continued payment or a cash buffer. Plan your Coast Number around the scenario where your HDB is fully paid before 65 — our retirement budget guide shows how profoundly housing status shifts your monthly numbers.
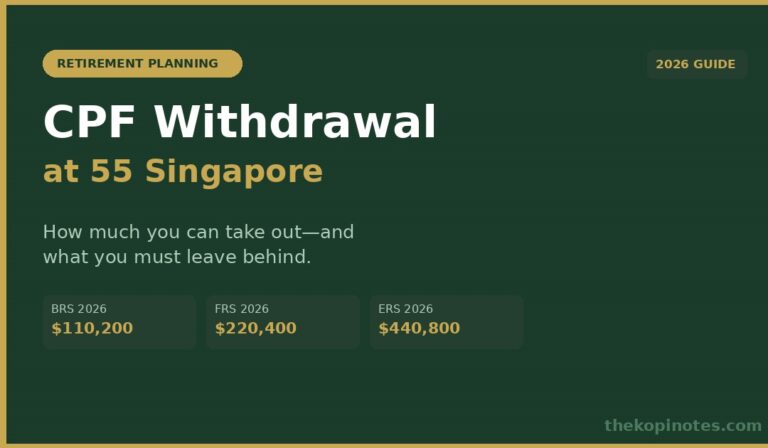
Not topping up to FRS. CPF LIFE’s income floor only reaches S$1,780/mo if you hold the FRS in your Retirement Account. If you sit at BRS (~S$950/mo), your Coast Number nearly doubles. For most Coast FIRE plans, topping up to FRS is one of the highest-return uses of investable capital — guaranteed, partially indexed to CPF interest rates. See the full CPF Retirement Sum guide for how to build towards FRS.
Frequently Asked Questions
What is the difference between Coast FIRE and Barista FIRE?
How does CPF LIFE reduce my Coast FIRE number?
Can I use my SRS account as part of my Coast FIRE portfolio?
Does my HDB status affect my Coast FIRE calculation?
What return rate should I use for my Coast FIRE calculation?
At what age is it realistic to hit Coast FIRE in Singapore?
What happens to my CPF contributions while I am coasting?
Is there a calculator I can use for my Coast FIRE number in Singapore?
Related Tools & Further Reading
- FIRE Singapore: The Number You Actually Need — The pillar guide covering the full FIRE spectrum and how to work out your total retirement number.
- Singapore Retirement Calculator — Model your CPF LIFE payouts, private portfolio target, and years to retirement.
- CPF Retirement Sum Singapore Guide — Understand BRS, FRS, and ERS and how to top up your Retirement Account.
- How Much to Retire in Singapore — The three monthly budget tiers with actual cost breakdowns for 2026.
- Coast FIRE Glossary Definition — Quick-reference definition and formula.
- Retirement Planning Calculator — Interactive tool for Singapore retirement scenarios.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.